Global Market Analysis

Delivers a timely overview of the most critical developments across global supply chains, commodity chemicals, energy, sustainability, and downstream industries. Each issue tracks key policy shifts, market disruptions, pricing trends, and corporate moves shaping the chemical and energy landscape.

Reports

Cash and Consequences: Chemical Restructuring Tests What Growth Is Worth

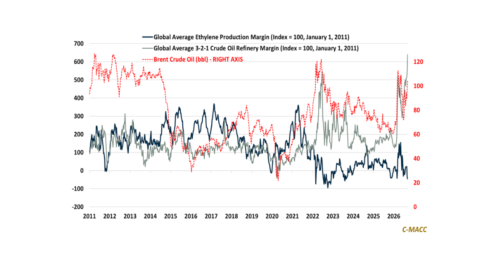
General Thoughts: Chemical restructuring should improve risk-adjusted returns without underfunding existing assets, making gains from reallocating capital a stronger guide for investment than segment margins.

Supply Chain/Commodities: European restructuring should secure competitive inputs before closing plants, or upstream savings risk undermining downstream earnings expected to fund the region’s growth.

Energy/Upstream:
Read More »

Follow the Returns: Chemical Capital Moves Closer to Customers as Feedstock Advantages Diverge

General Thoughts: Chemical producers without durable feedstock advantages are directing capital closer to customers, where qualification and application expertise can support stronger risk-adjusted returns.

Supply Chain/Commodities: Record US diesel prices are absorbing part of the crop price recovery by lowering farm gate realizations and raising delivered input costs across agriculture

Read More »

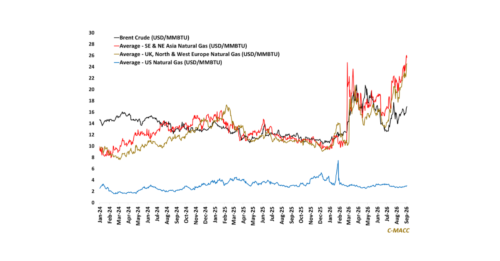
Gas Pedal: Overseas Natural Gas Outruns Oil as Industrial Cost Gaps Widen

General Thoughts: European and Asian natural gas prices are rising faster than Brent, pressuring high-cost industrial assets as input costs rise and commodity markets offer little room for pass-through.

Supply Chain/Commodities: Global olefin restructuring accelerates as producers shift assets and portfolios toward higher returns, with US ethane cutting costs and

Read More »

Current Account: Cheap Energy Is Not a Blank Check

General Thoughts: Wide energy-cost gaps are filtering capital toward projects that secure advantaged inputs and credible demand before infrastructure constraints or policy shifts materially dilute expected returns.

Supply Chain/Commodities: Ammonia pricing increasingly favors producers that pair low-cost energy with market reach, as weak phosphate demand breaks the usual link between

Read More »

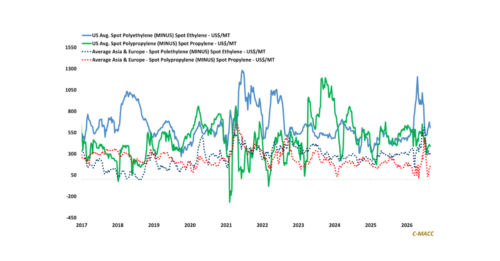
Resin To Riches: Weekly Plastic Market Insights

General Thoughts: US polymer prices remain well above monomer prices, but the retreat from 2026 highs gives strategy teams little reason to reopen broad growth capital until stronger utilization improves returns.

Polyethylene (PE): China’s PE rally reflects tighter local supply more than stronger consumption, raising the risk that new capacity

Read More »

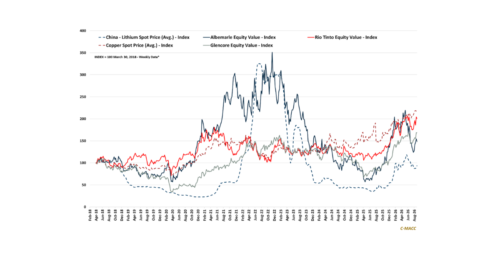
Commercial Control: Capturing Value Before Market Tightness Spreads Across The Value Chain

General Thoughts: Across copper, lithium, LNG, and AI infrastructure, the strongest economics accrue to companies that control the commercial decisions turning favorable market conditions into durable cash flow.

Supply Chain/Commodities: Copper inventories are concentrating outside the LME system, raising benchmark costs before global refined balances show comparable physical tightness elsewhere.

Read More »

Same Market, Different Margin: Location Changes What the Customer Really Pays

General Thoughts: Elevated methanol and overseas energy costs selectively improve incumbent economics, but China’s trade shift and cautious renewable spending show pricing does not yet justify broad expansion.

Supply Chain/Commodities: North American methanol’s historically wide posted-to-spot gap highlights the value of term supply and logistics, even as contractual discounts keep

Read More »