Base Chemical Global Analysis

Weekly, Data-Centric Intelligence on Core Chemical Market

Our Base Chemical & Polymer Analysis reports offer a comprehensive, data-rich snapshot of global market dynamics every week. Each edition delivers actionable insights backed by curated charts and margin models to help you stay ahead of market movements, arbitrage trends, and structural shifts.

Reports

Global Weekly Catalyst No. 352

General Thoughts: European and Asian chemical producers buying feedstocks risk output cuts as limited pricing power constrains recovery of input costs elevated by continued Middle East disruption.

Feedstocks & Energy: Diverging feedstock prices improved US liquids purchase economics and Asian LPG discounts last week but reduced European switching savings, leaving
Read More »

Global Weekly Catalyst No. 351

General Thoughts: Returning supply can cut sellers’ prices before buyers secure cheaper deliveries, so stronger trade may reflect supply rerouting rather than demand growth or margin recovery.

Feedstocks & Energy: Europe’s smaller LPG discount limits crackers’ feedstock savings, leaving margins exposed if restored Middle East deliveries weaken chemical prices before

Read More »

Global Weekly Catalyst No. 350

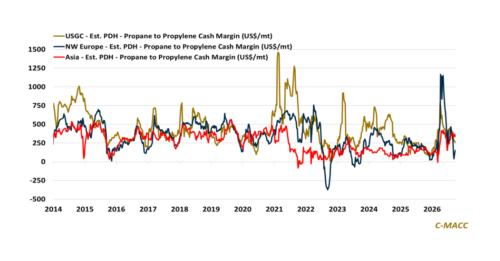
General Thoughts: Regional advantage changes with the process and the buyer; rising propane and weaker PGP have put modeled US PDH margins below Asia, even as advantaged USGC ethane favors domestic crackers.

Feedstocks & Energy: Asia’s naphtha premium widened despite flat weekly crude, but freight and cautious buyers limit arbitrage;

Read More »

Global Weekly Catalyst No. 349

General Thoughts: Softer crude and weak demand could encourage downstream customers to seek discounts before intermediate costs ease, leaving merchant producers to absorb the difference through lower margins.

Feedstocks & Energy: Asian naphtha rose as crude eased, and Rhine freight threatens European savings, leaving delivered feedstock costs slow to reflect

Read More »

Global Weekly Catalyst No. 348

General Thoughts: The current global energy shock is widening operating freedom across the value chain, allowing advantaged producers to stay active while weaker assets face earlier production cuts and rising import dependence.

Feedstocks & Energy: Crude inflation is deepening Asia’s naphtha disadvantage, while low-cost US natural gas and ethane provide

Read More »

Global Weekly Catalyst No. 347

General Thoughts: Market disruptions are widening profit gaps across regions, making cost position and operating flexibility more important as companies decide where to put their next investment dollar.

Feedstocks & Energy: Higher crude prices and constrained refinery output are keeping Asian naphtha expensive, widening the US olefin chain feedstock advantage

Read More »

Global Weekly Catalyst No. 346

General Thoughts: Across chemical markets, advantaged assets are capturing more value without gaining broad pricing power, keeping capital focused on existing capacity as localized supply constraints drive relative performance.

Feedstocks & Energy: Low-cost US natural gas and NGLs improve existing asset economics without triggering broad downstream chemical investment, as Europe

Read More »

Global Weekly Catalyst No. 345

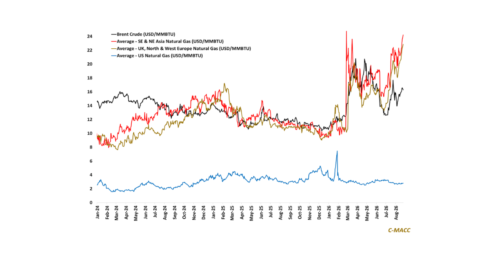
General Thoughts: Most attention remains on crude oil, but ex-US natural gas has made a more consequential move toward multi-year highs, widening regional cost gaps across chemicals, fertilizers, and energy-intensive industries.

Feedstocks & Energy: Record US propane inventories show exports have not overwhelmed domestic supply, while cheaper Asian naphtha is

Read More »

Global Weekly Catalyst No. 344

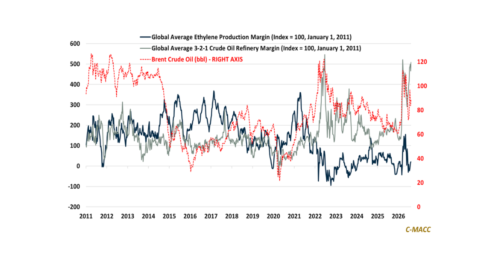
General Thoughts: Refiners are earning strong returns because fuel supply remains tight, but weak petrochemical demand keeps higher costs and outages from producing a broad recovery in margins.

Feedstocks & Energy: Energy benchmarks moved faster than chemical feedstocks last week, showing that headline energy volatility changed regional cost positions less

Read More »