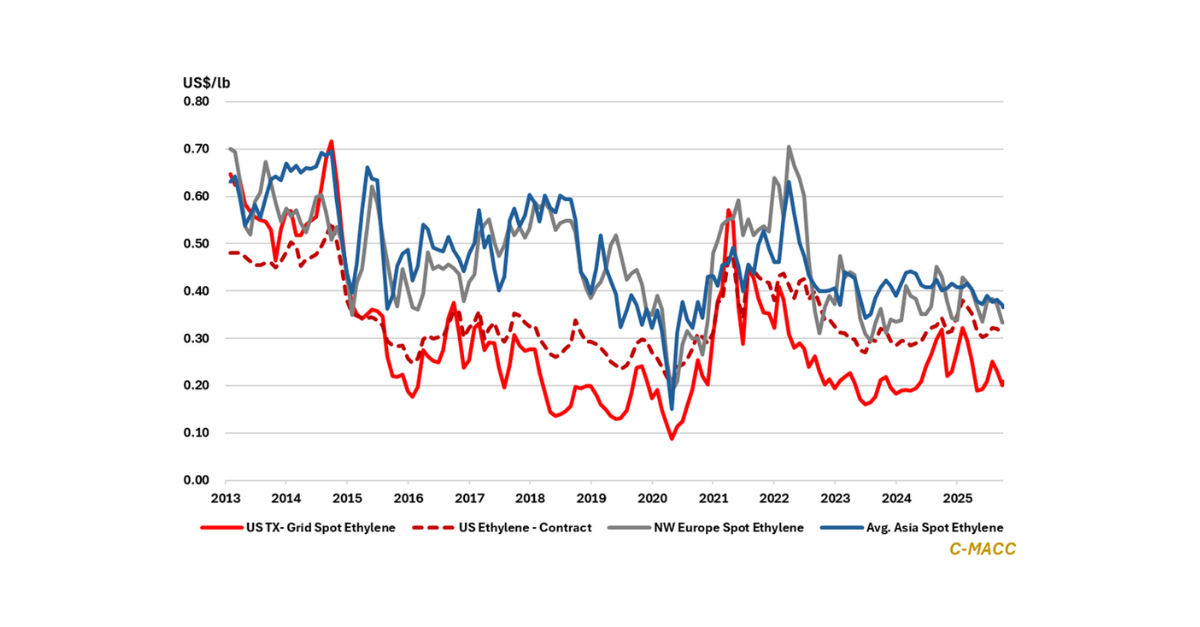
Base Chemical Global Analysis
General Thoughts: Shifting energy costs, tighter margins, and policy uncertainty redraw the global chemicals map, favoring integrated, flexible producers but pressuring most in a demand-

General Thoughts: Shifting energy costs, tighter margins, and policy uncertainty redraw the global chemicals map, favoring integrated, flexible producers but pressuring most in a demand-

General Thoughts: Global commodity chemical markets remain margin-compressed, oversupplied, and policy-sensitive, with investors watching for stabilization yet hesitating to pivot toward a 2026 improvement story.

2025 increasingly appears to mark the cyclical and structural bottom in construction materials, as collapsing completions and tightening inventories set the stage for affordability-driven recovery
