Global Market Analysis
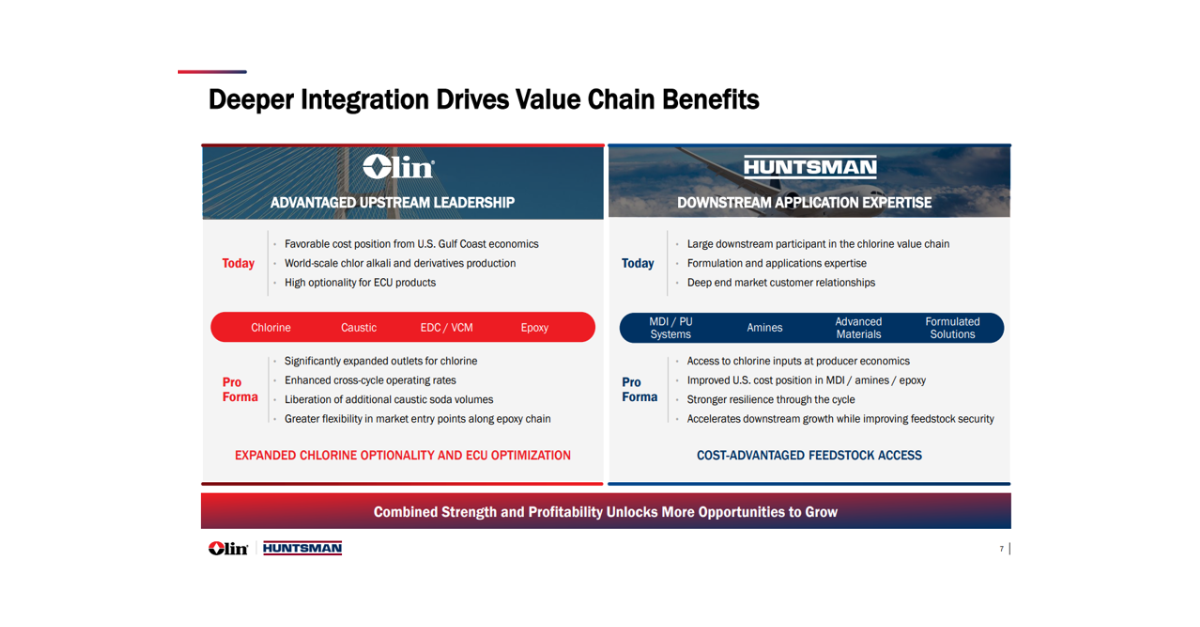
General Thoughts: Weak returns are forcing strategic repair as producers separate, combine, or reposition assets to improve risk-adjusted returns rather than wait for cleaner demand,

General Thoughts: Weak returns are forcing strategic repair as producers separate, combine, or reposition assets to improve risk-adjusted returns rather than wait for cleaner demand,
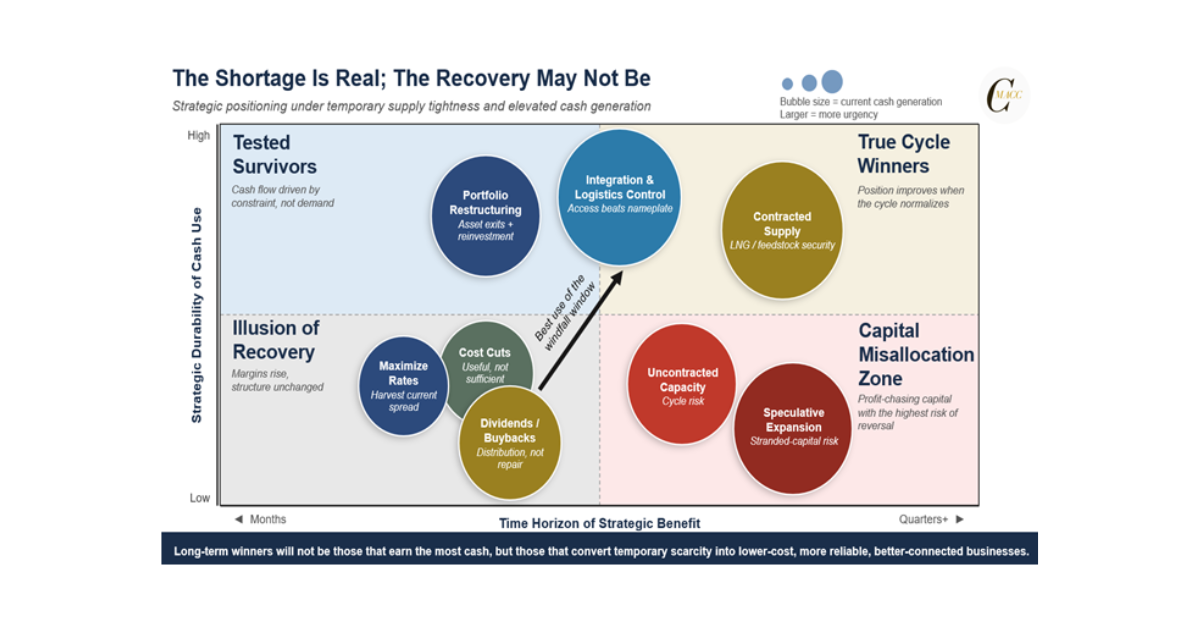
Contract pricing is emerging as the governing signal in constrained markets, embedding access, timing, and supply assurance, while spot pricing reflects residual, uncommitted liquidity pools.
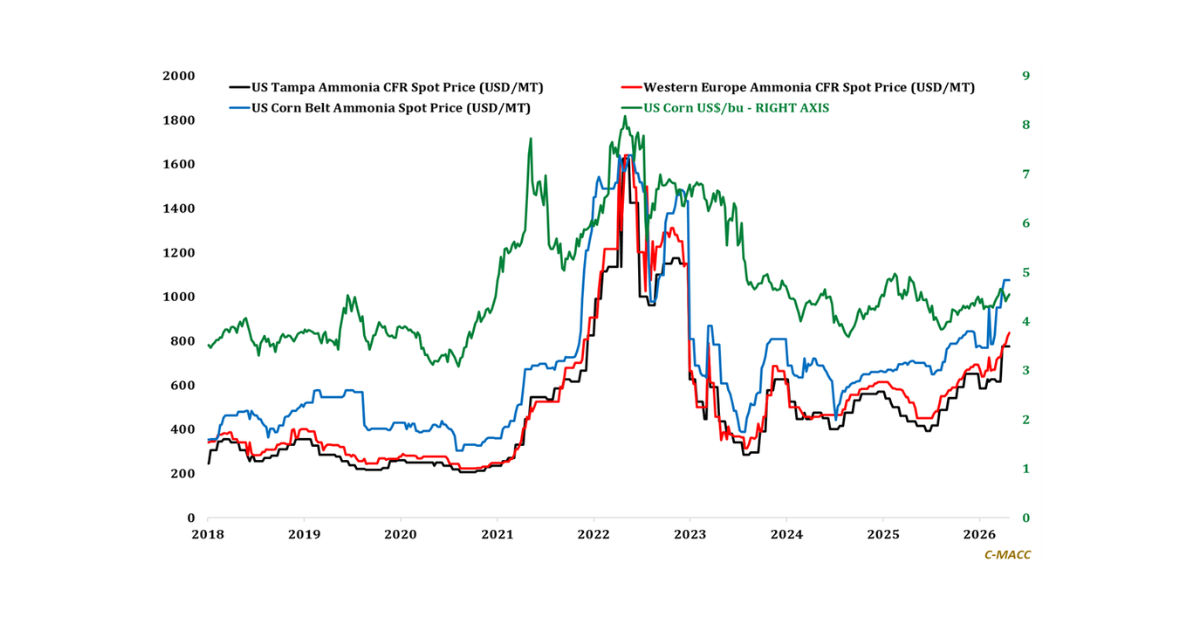
General Thoughts: Downstream industries face acute input inflation, as price-driven outcomes and selective policy support delay adjustment, leaving many exposed despite rising upstream and infrastructure
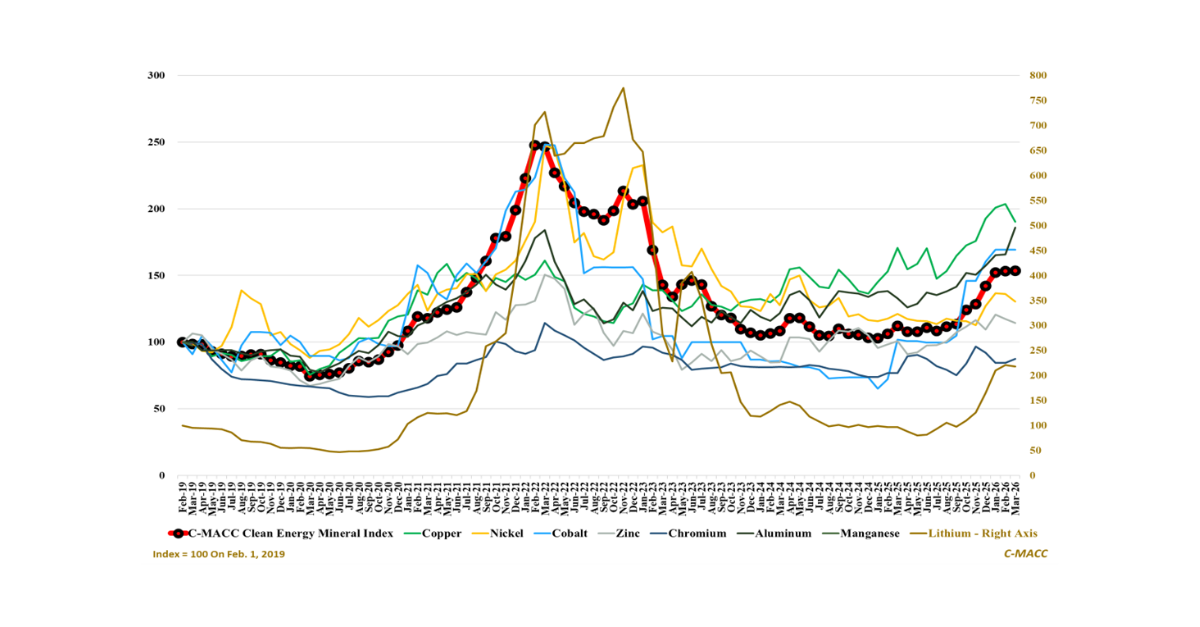
Critical minerals diverge as electrification costs fall structurally, confirming inputs are no longer the binding constraint and decisively shifting advantage toward systems that deliver reliable
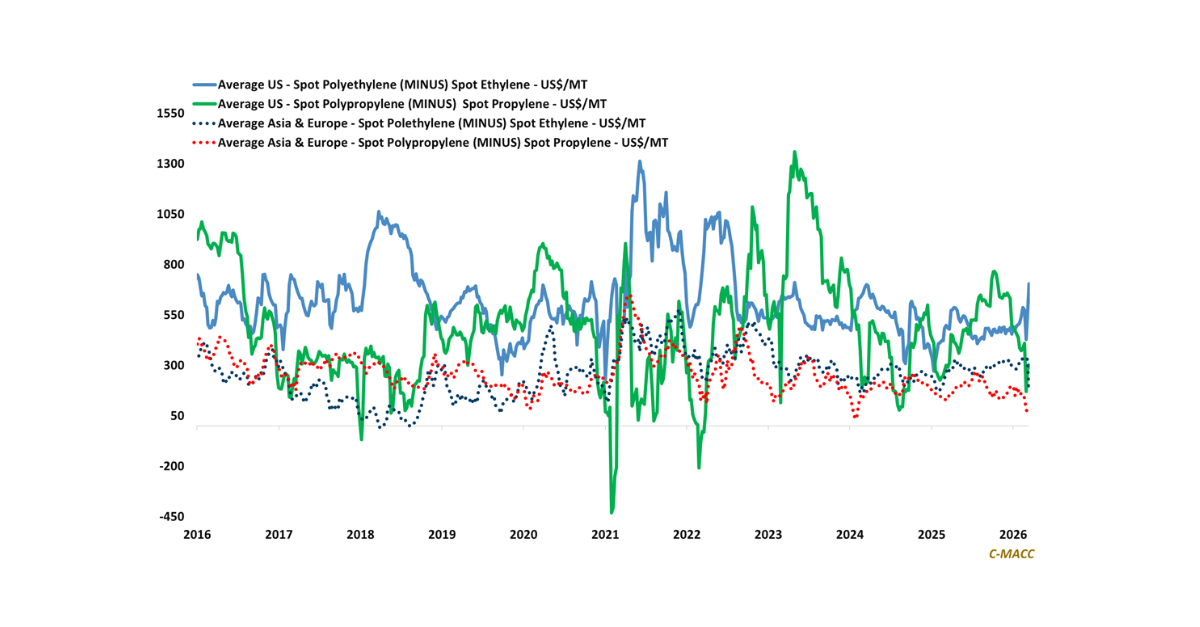
Dependable operations now define competitive advantage, with non-integrated assets losing ground as fragility disrupts throughput, raises risk, and weakens returns under stress.
Oil-linked feedstock systems
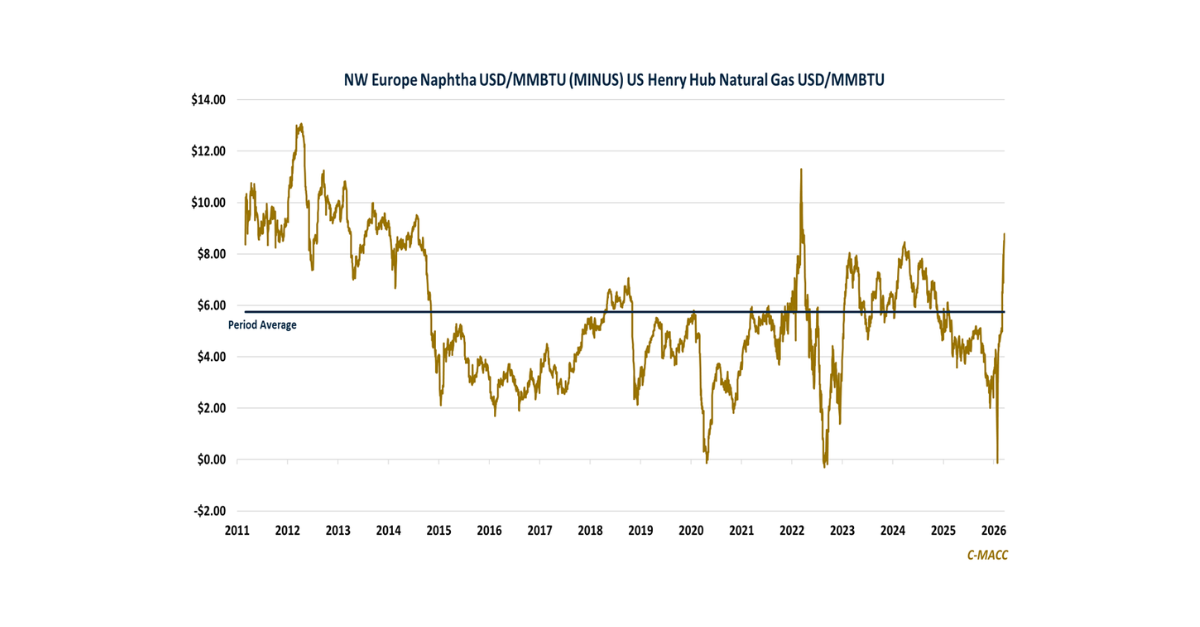
General Thoughts: Escalating Middle East disruption scale is reducing system flexibility faster than it can be restored, shifting pricing power, capital allocation, and competitive positioning
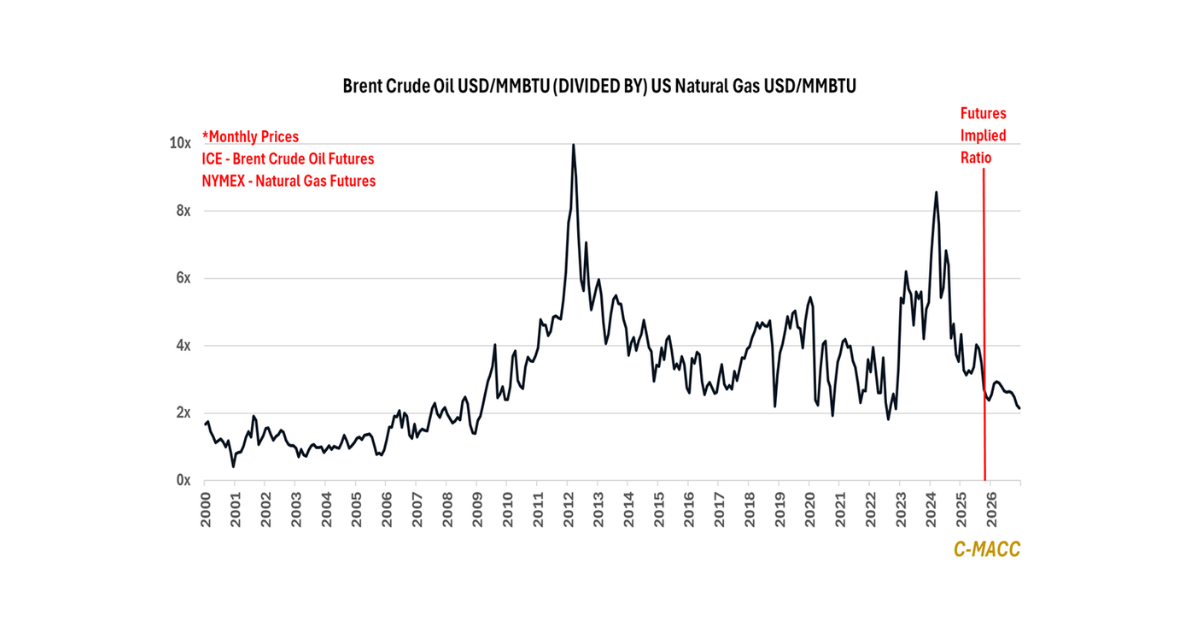
Depressed oil-to-gas ratios and elevated soy-to-corn prices shift chemical-sector risk profiles: commodity chemical underperformers in 2025 face low expectations in 2026, whereas agriculture faces the
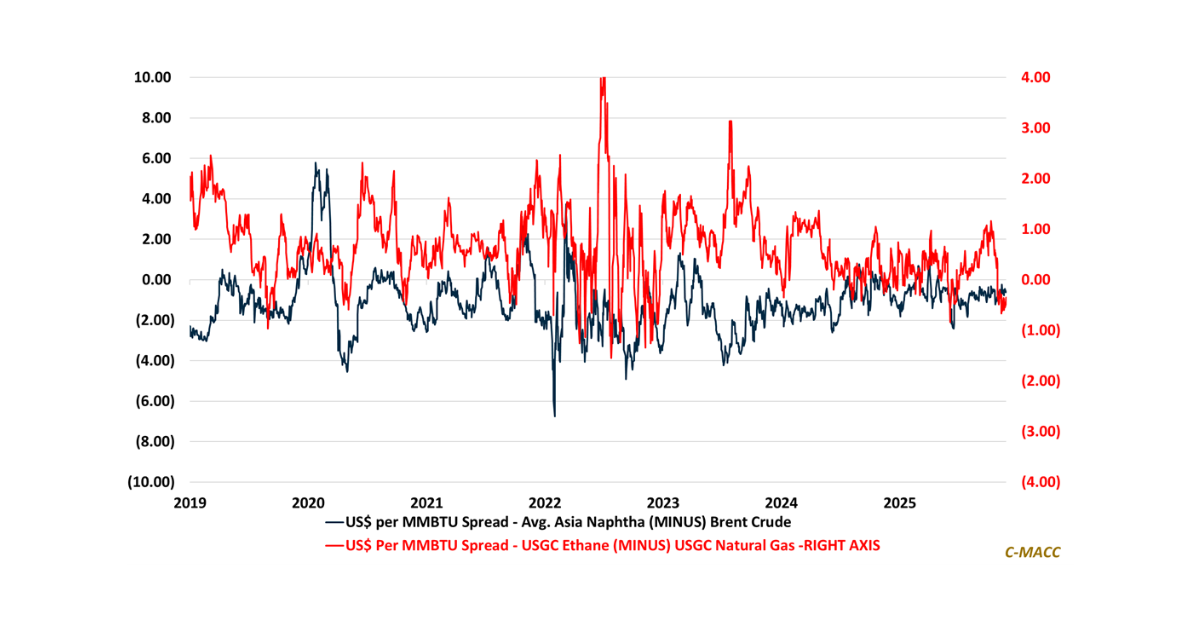
General Thoughts: Feedstock convergence, rising USGC ethane risk, and disappearing European carbon buffers accelerate petrochemical restructuring, squeezing INEOS Project One and advantaged Asian ethane importers.
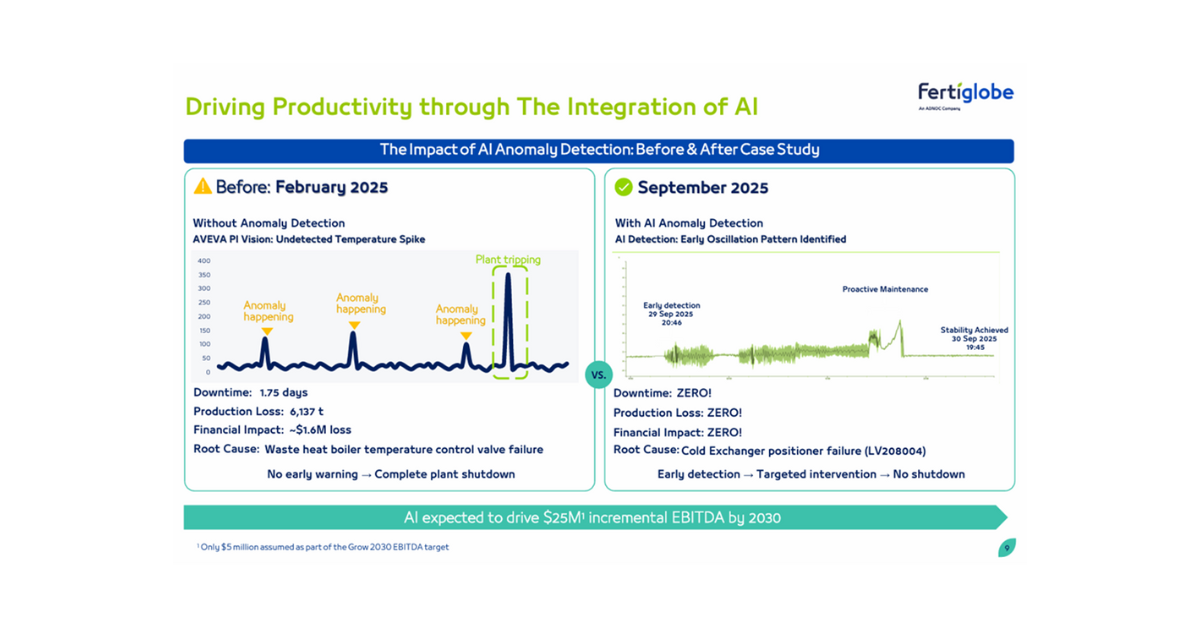
General Thoughts: AI-driven optimization converts operational noise into margin clarity, embedding predictive reliability, capital sequencing, and digital decision velocity across complex global industrial systems.
Supply
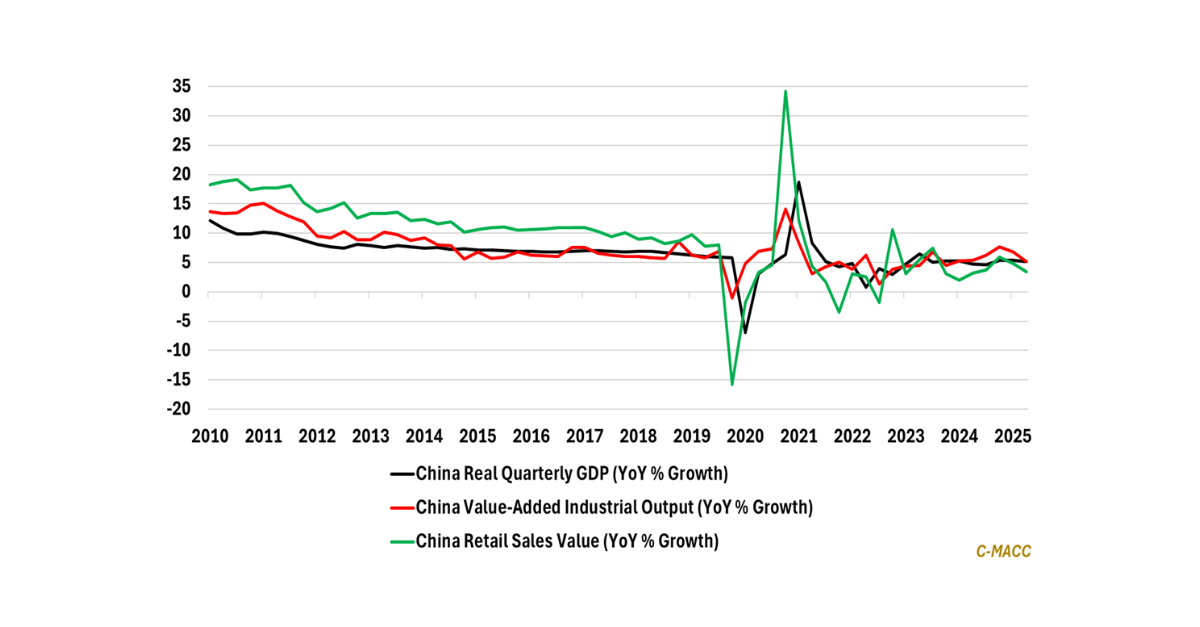
Volatility has transcended cycle theory to become global industrial gravity, where policy cadence, not demand elasticity, dictates profitability, capital sequencing, and the new tempo of
