Sunday Executive Summary
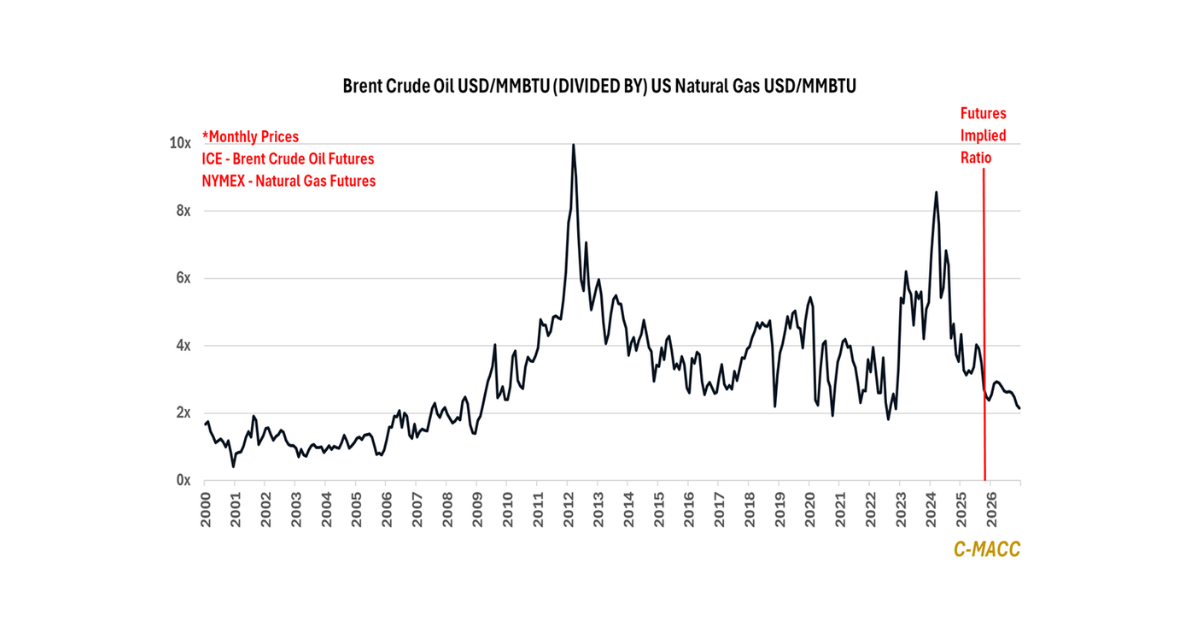
Depressed oil-to-gas ratios and elevated soy-to-corn prices shift chemical-sector risk profiles: commodity chemical underperformers in 2025 face low expectations in 2026, whereas agriculture faces the

Depressed oil-to-gas ratios and elevated soy-to-corn prices shift chemical-sector risk profiles: commodity chemical underperformers in 2025 face low expectations in 2026, whereas agriculture faces the
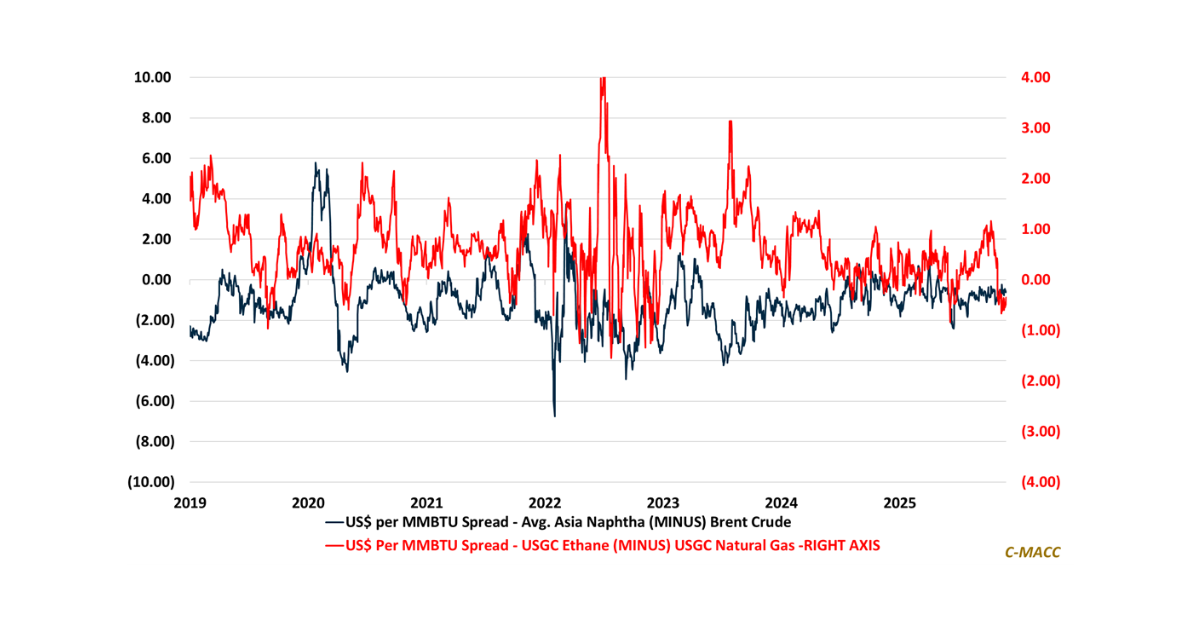
General Thoughts: Feedstock convergence, rising USGC ethane risk, and disappearing European carbon buffers accelerate petrochemical restructuring, squeezing INEOS Project One and advantaged Asian ethane importers.
