Sunday Executive Summary
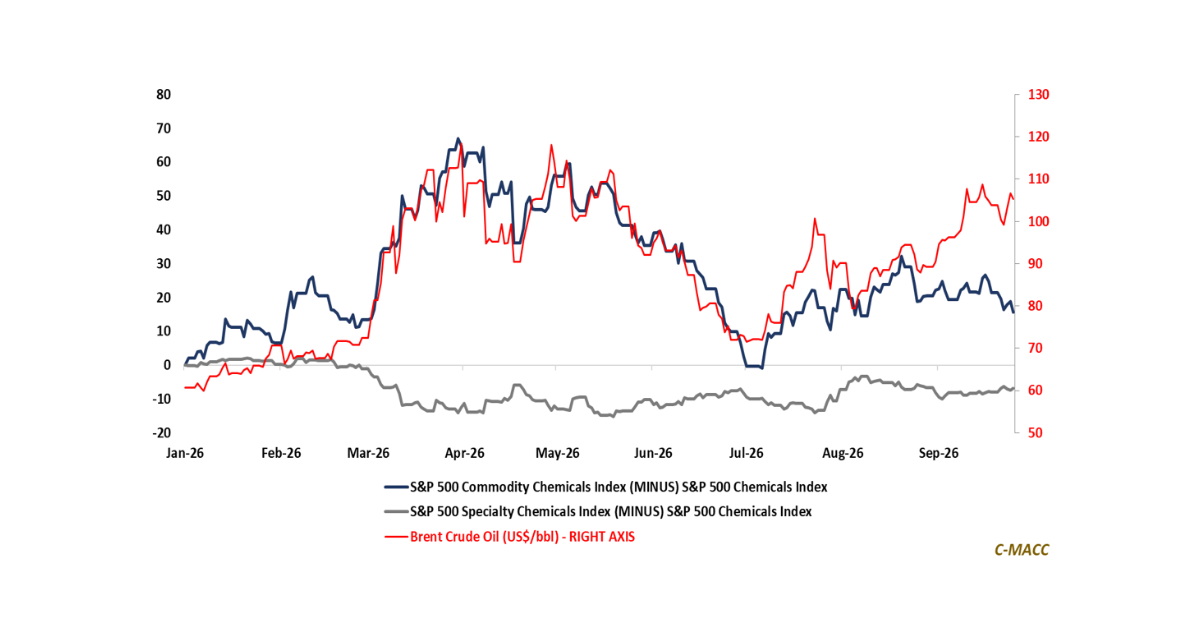
Commodity chemical shares retain their lead as selected resin grades tighten, but delayed cargoes can lift prices before producers permanently reduce the capacity available to

Commodity chemical shares retain their lead as selected resin grades tighten, but delayed cargoes can lift prices before producers permanently reduce the capacity available to
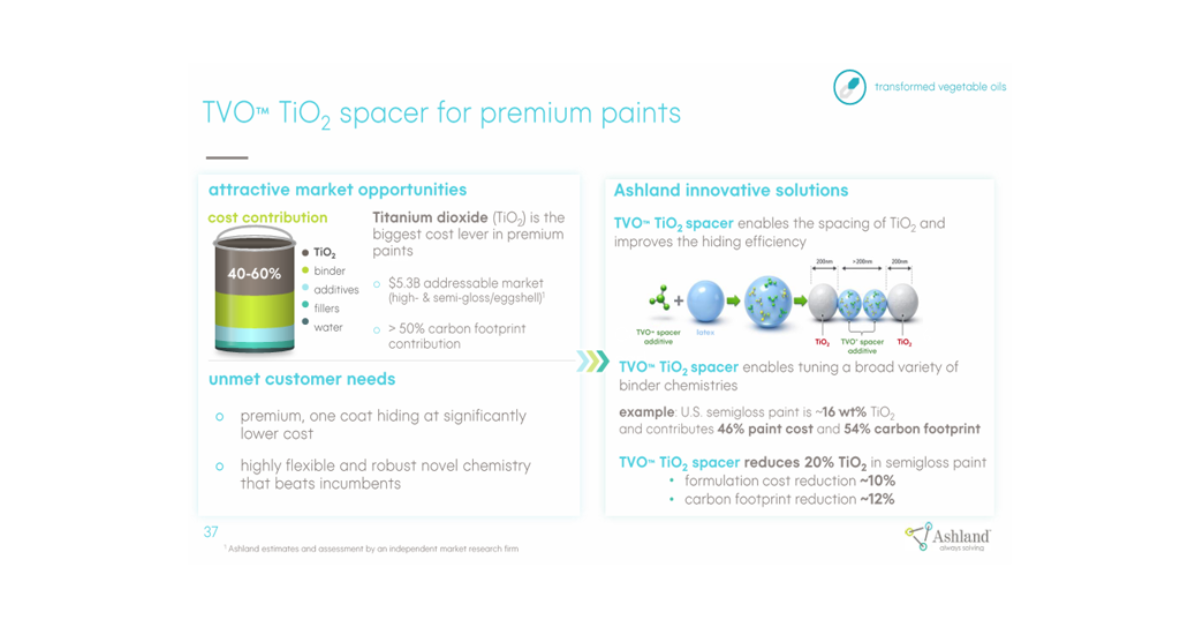
1st Topic of the Week: Lower formulation costs could strengthen paintmakers’ purchasing leverage before pigment volumes decline, leaving additive developers to prove they can retain
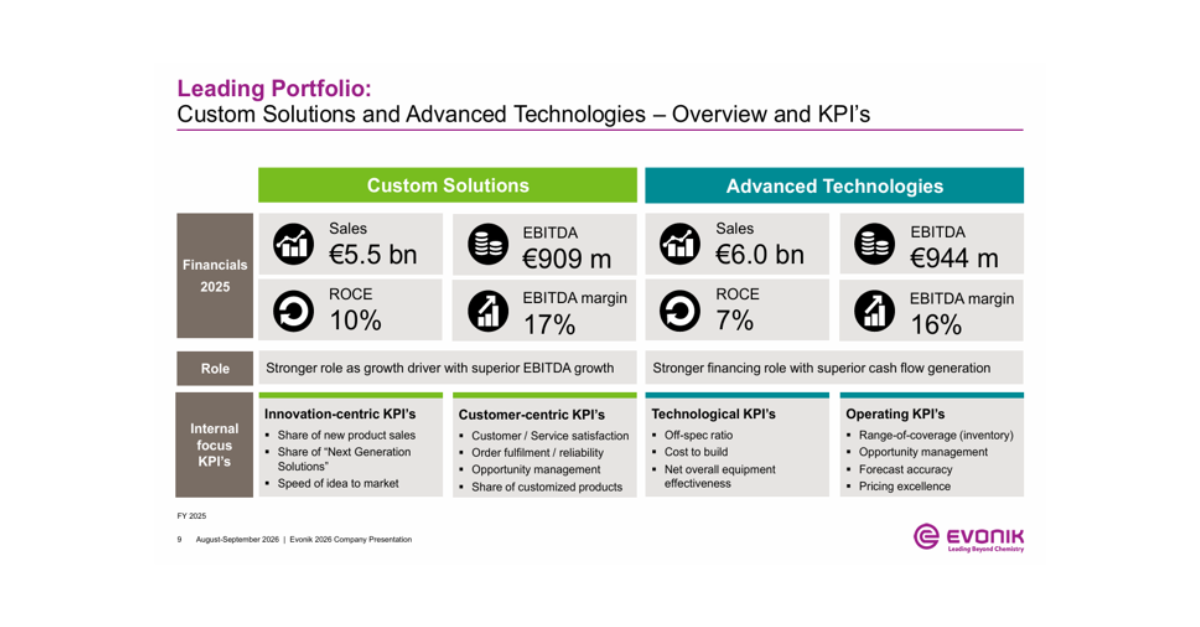
General Thoughts: Chemical restructuring should improve risk-adjusted returns without underfunding existing assets, making gains from reallocating capital a stronger guide for investment than segment margins.
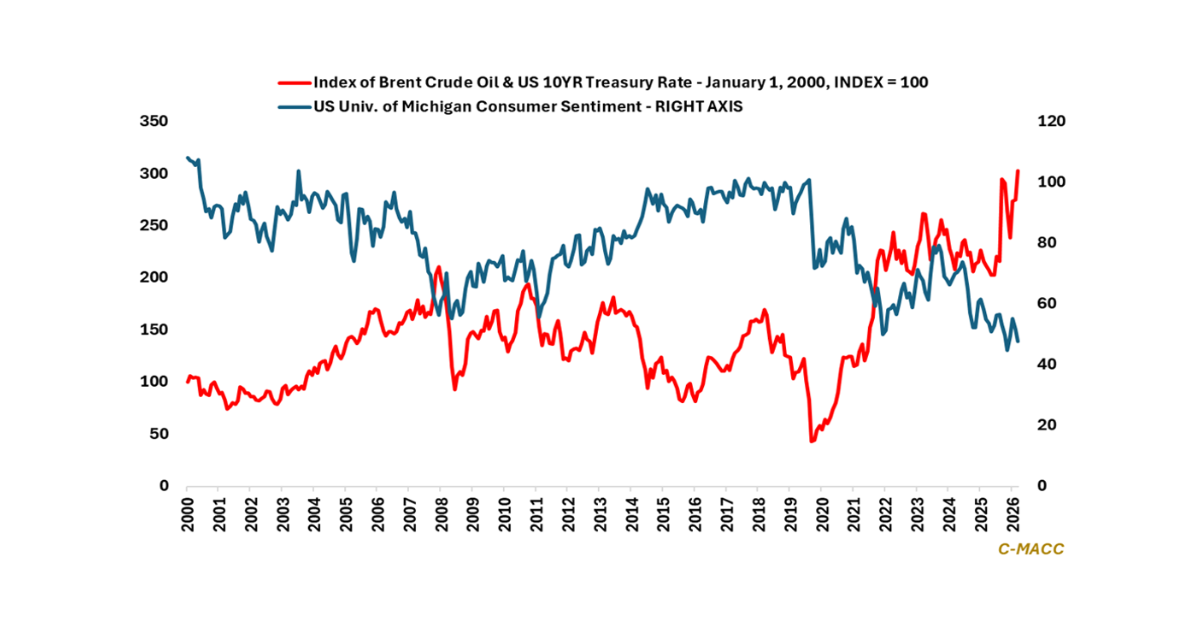
Chemical capital is separating by model, with integrated producers funding hard-to-replicate advantages and customer-facing businesses demanding clearer economics before growth spending.
Dow’s collaboration with Amcor

General Thoughts: European and Asian natural gas prices are rising faster than Brent, pressuring high-cost industrial assets as input costs rise and commodity markets offer
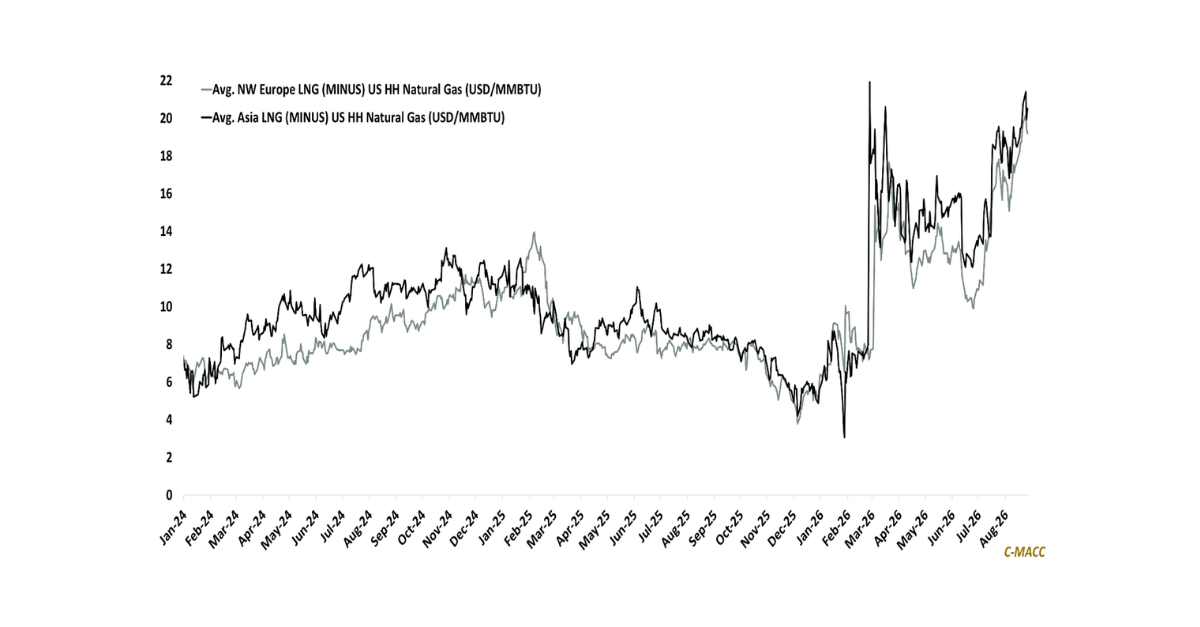
Industrial capital is clustering around power and energy infrastructure, leaving chemical producers to improve returns from existing assets as excess capacity keeps global expansion spending
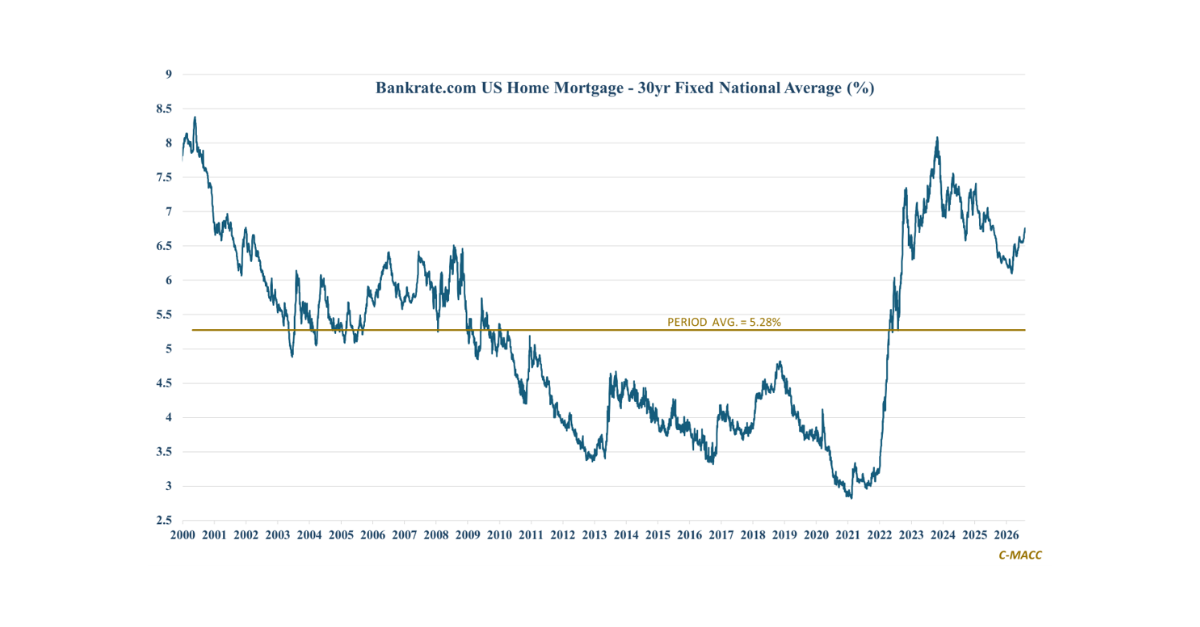
General Thoughts: Mortgage rates at a 2026 high are widening earnings gaps across construction markets, favoring businesses tied to funded infrastructure over those awaiting a
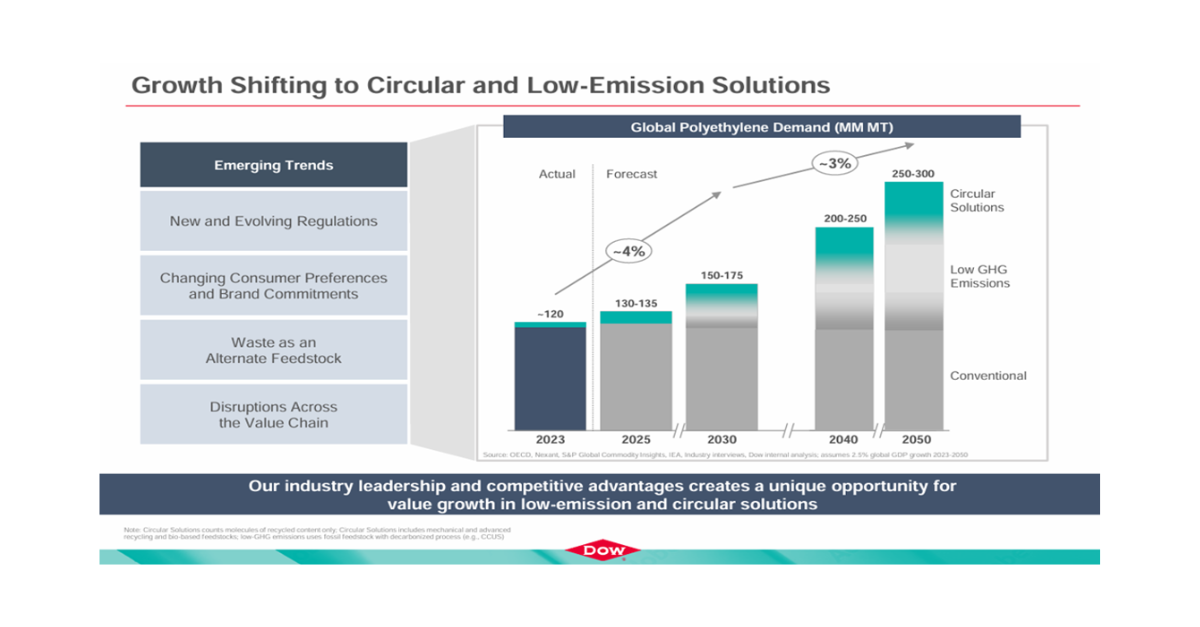
Most attention remains on near-term PE tightness, but supply growth is also becoming less dependable, leaving the medium-to-long-term outlook firmer than pre-conflict forecasts anticipated.
Middle
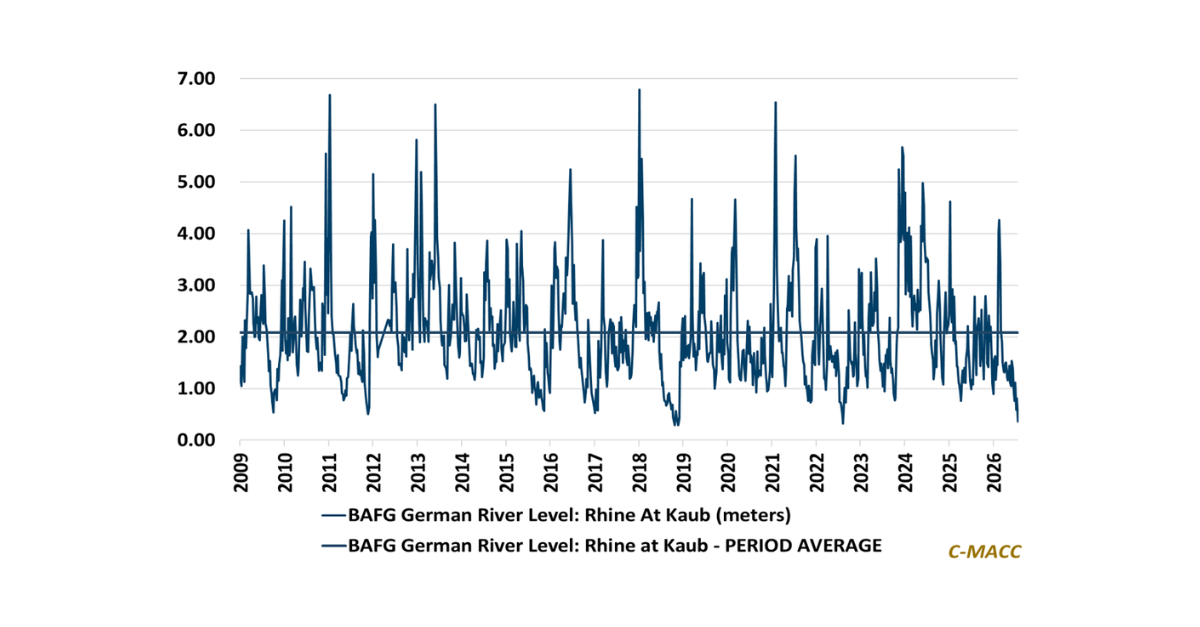
General Thoughts: Extreme heat, low Rhine levels, and elevated feedstock costs are keeping chemical prices firm, but weak customer economics are limiting producers’ ability to
Industrial companies are directing capital toward revenue that can finance continued investment without leaving the wider business exposed when customers, technologies, or regional economics change.
