Base Chemical Global Analysis
Global Weekly Catalyst No. 351
- General Thoughts: Returning supply can cut sellers’ prices before buyers secure cheaper deliveries, so stronger trade may reflect supply rerouting rather than demand growth or margin recovery.
- Feedstocks & Energy: Europe’s smaller LPG discount limits crackers’ feedstock savings, leaving margins exposed if restored Middle East deliveries weaken chemical prices before winter energy purchases become less costly.
- Olefins: Resin buyers can restock from sellers’ inventories in 4Q26, leaving olefin maintenance premiums vulnerable as returning crackers seek customers before derivative sales justify sustained output increases.
- Other Base Chemicals: Methanol faces recovering Chinese supply; European chlor-alkali carries electricity-driven curtailment risk; benzene demand depends on derivative output, not simply higher derivative prices.
- Agriculture: China’s export quotas strengthen India’s negotiating position, but a cheaper prilled award could pressure granular sellers’ asking prices without easing exposure to Middle East supply disruptions.
- Refining & Biofuels: China’s cargo cancellations favor refiners with available fuel; ethanol producers gain from cheaper corn, but returning supply could erode profits unless sales keep pace.
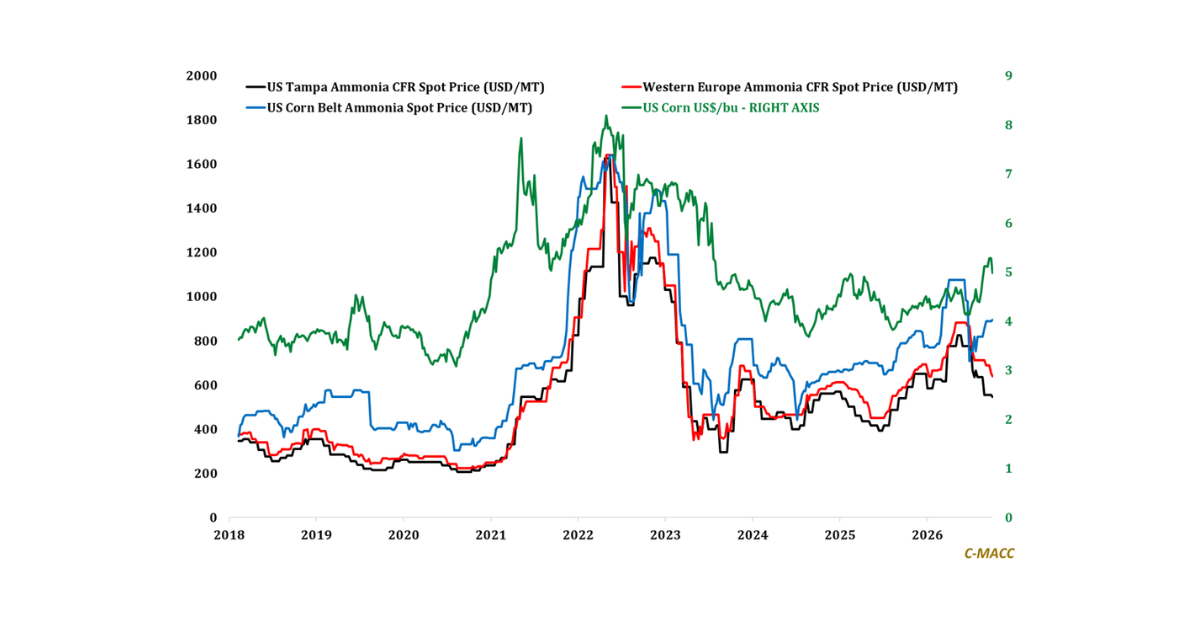
Exhibit 1 – Chart of the Day: Widening Inland Ammonia Premiums Limit Buyers’ Benefit From Lower Import Prices.
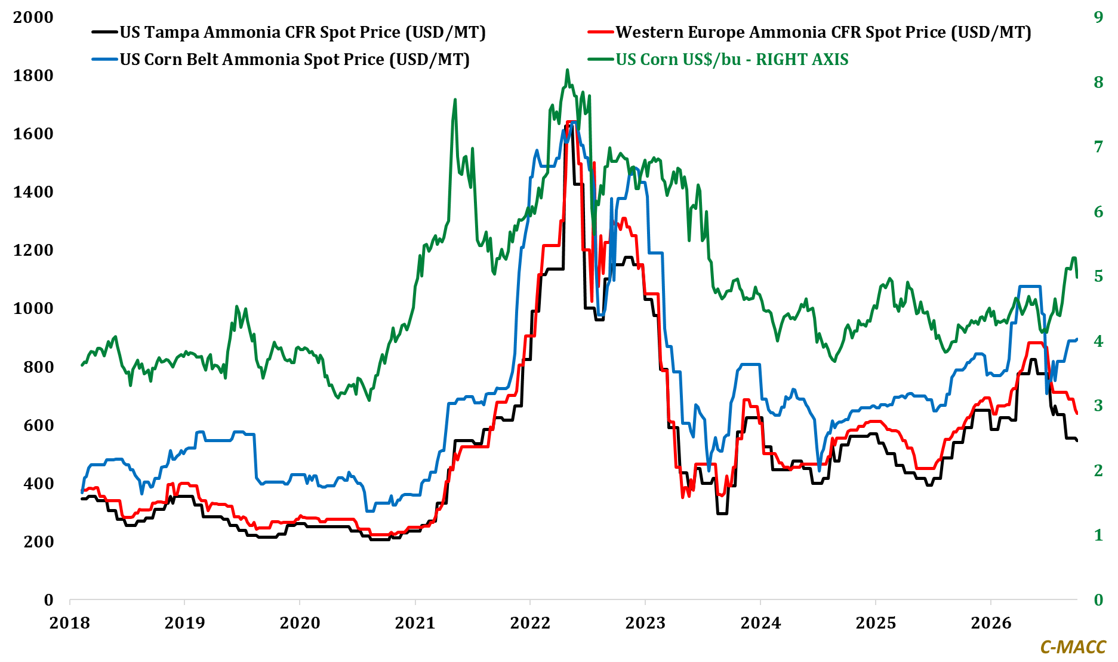
Source: Bloomberg, C-MACC Estimates, October 2026
Client Login
Learn About Our Subscriptions and Request a Trial
Contact us at cmaccinsights@c-macc.com to gain full access and experience our services!