Sunday Executive Summary
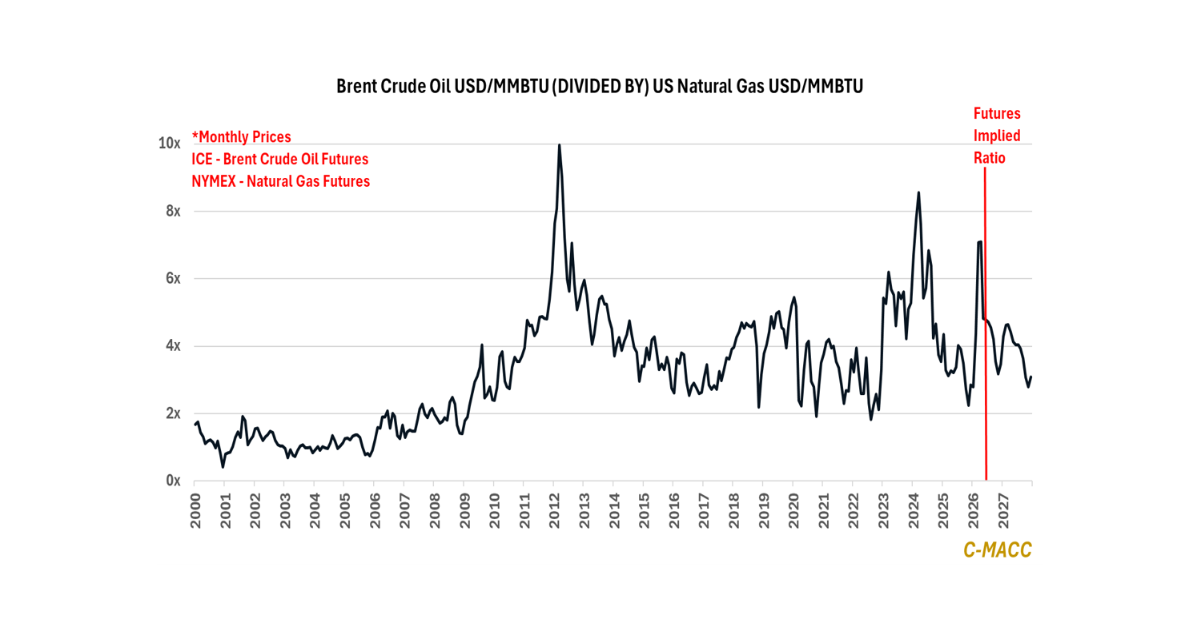
Chemical and polymer prices have retreated from peak 1H26 levels, but many remain above January levels, leaving buyers to judge whether relief is temporary or

Chemical and polymer prices have retreated from peak 1H26 levels, but many remain above January levels, leaving buyers to judge whether relief is temporary or
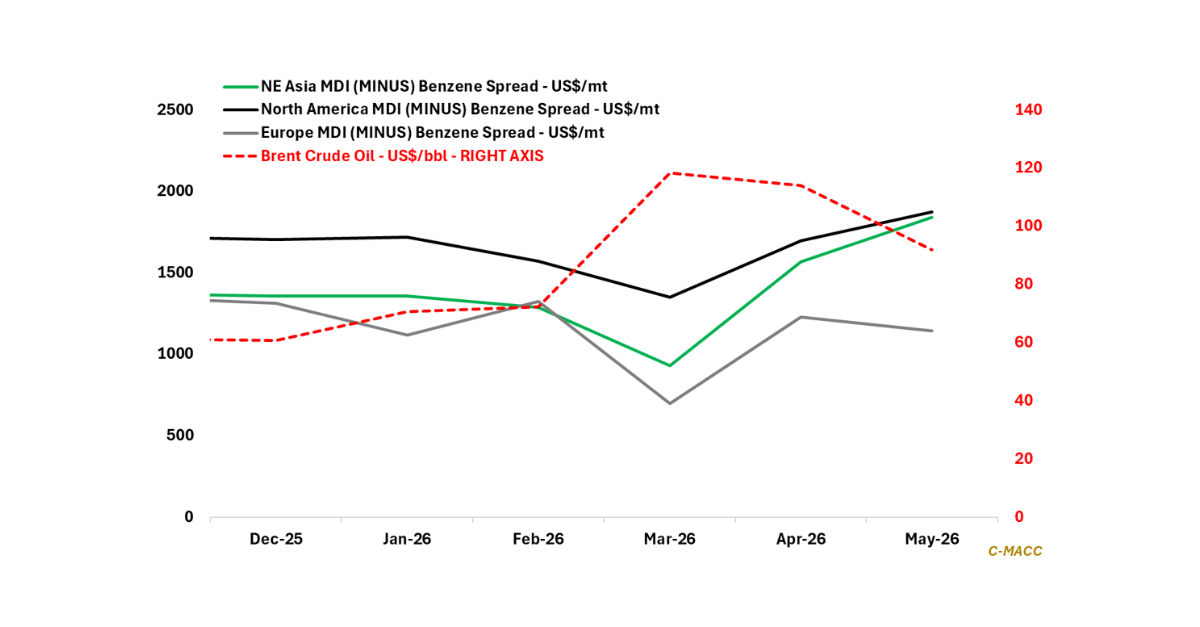
General Thoughts: Supply risk is keeping many chemical chains biased upward, with MDI markets showing how outage timing and system availability can sustain hikes even

General Thoughts: Global polymers struggle to pivot from trough to transition as trade fragmentation, regional cost asymmetry, and structural demand divergence reorder advantage, hurting laggards

Polystyrene – July Monthly Price Expectation Report

Polymer Price Expectations – June – Monthly Report # 17

Polymer Price Expectations – May – Monthly Report # 16

Polystyrene – April Monthly Price Expectation Report
Polymer Price Expectations – April– Monthly Report # 15

C-MACC Polymer Pricing Service

Polystyrene – February Monthly Price Expectation Report
