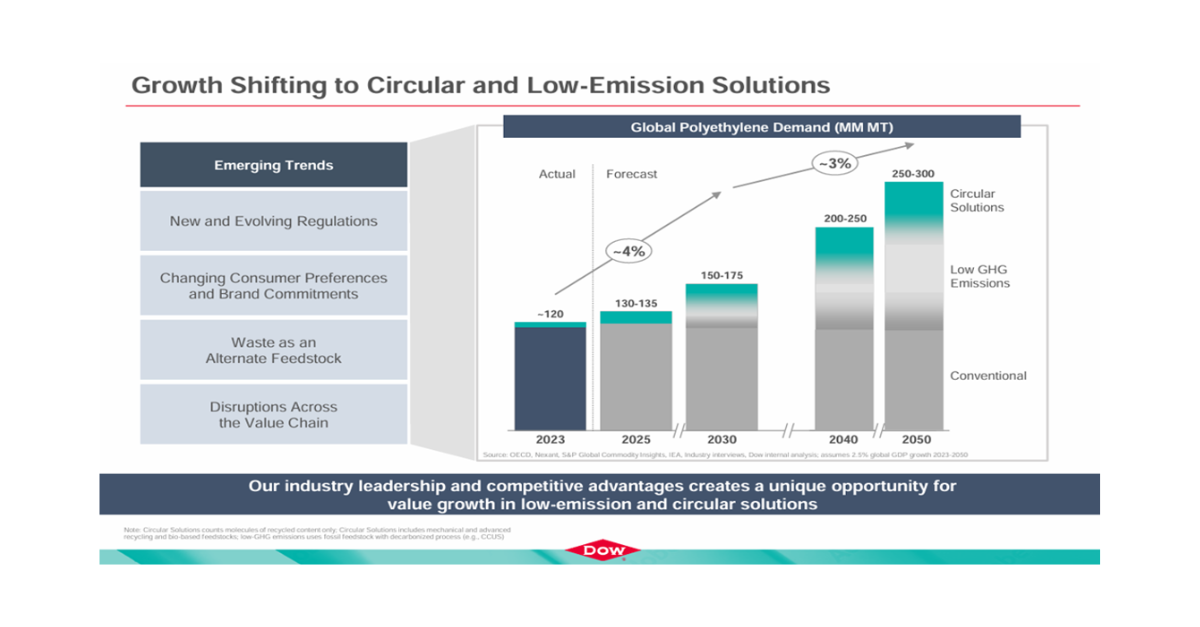
Sunday Executive Summary
Most attention remains on near-term PE tightness, but supply growth is also becoming less dependable, leaving the medium-to-long-term outlook firmer than pre-conflict forecasts anticipated.
Middle

Most attention remains on near-term PE tightness, but supply growth is also becoming less dependable, leaving the medium-to-long-term outlook firmer than pre-conflict forecasts anticipated.
Middle
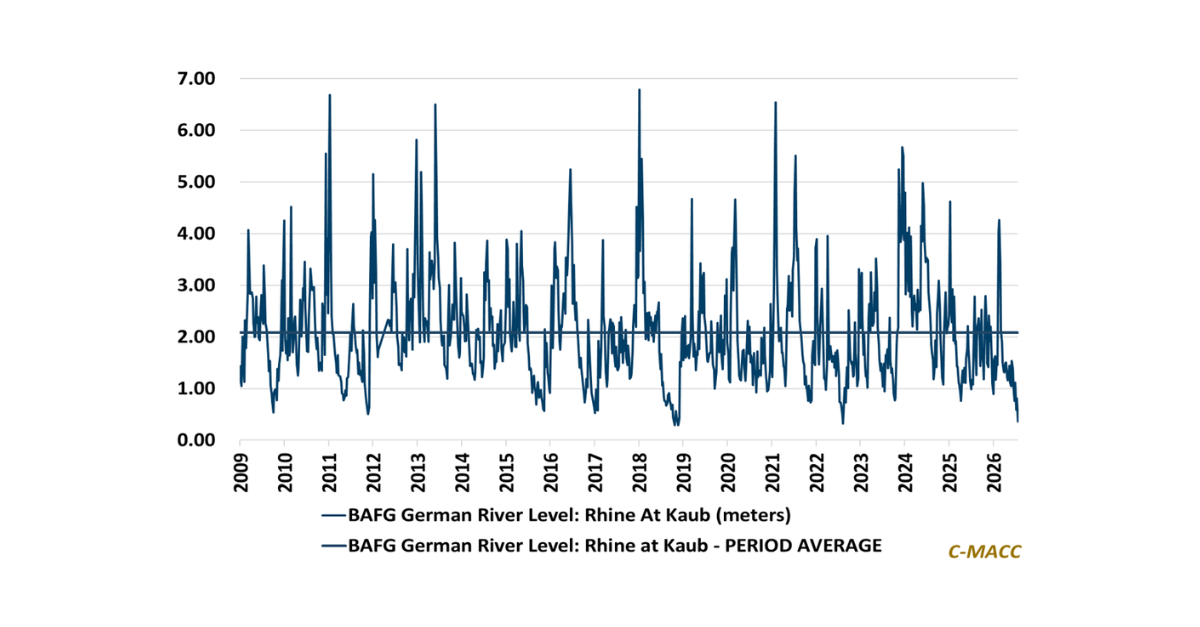
General Thoughts: Extreme heat, low Rhine levels, and elevated feedstock costs are keeping chemical prices firm, but weak customer economics are limiting producers’ ability to
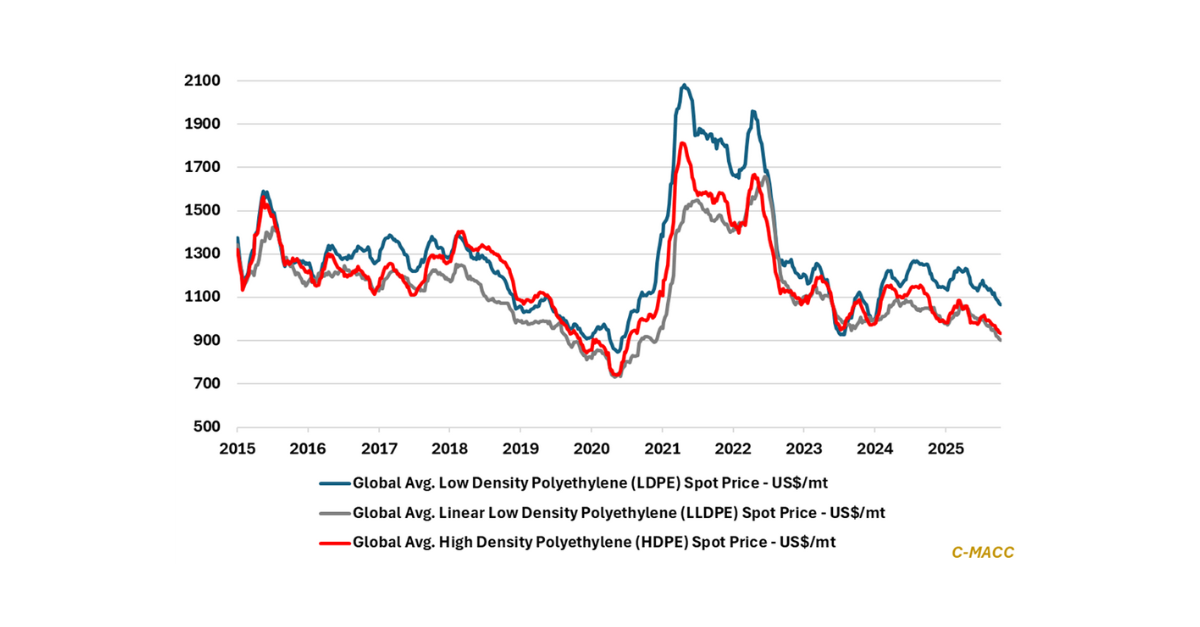
General Thoughts: Pessimism in petrochemicals is capitulation, not a signal; trough pricing, rationalizations, and capital scarcity prewire tighter conditions, as integration and customer intimacy reward
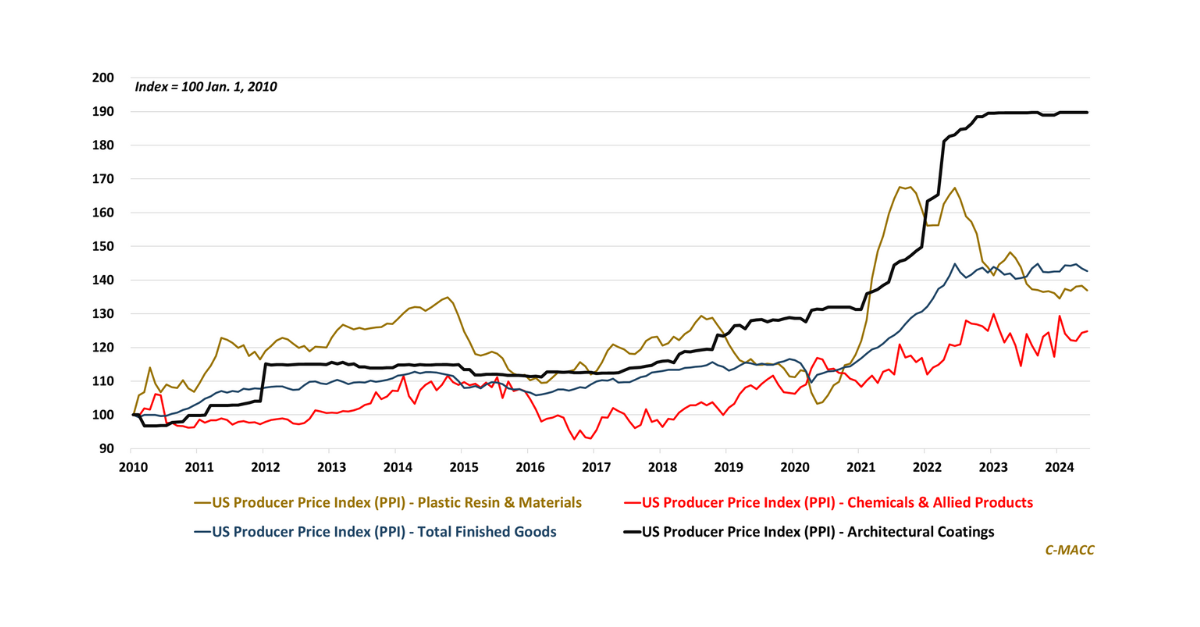
Daily Chemical Reaction Candy Paint – Global Coating Reports Show Mixed Results; Is New US Residential Construction Set to Catch a Sugar High? Key Findings
