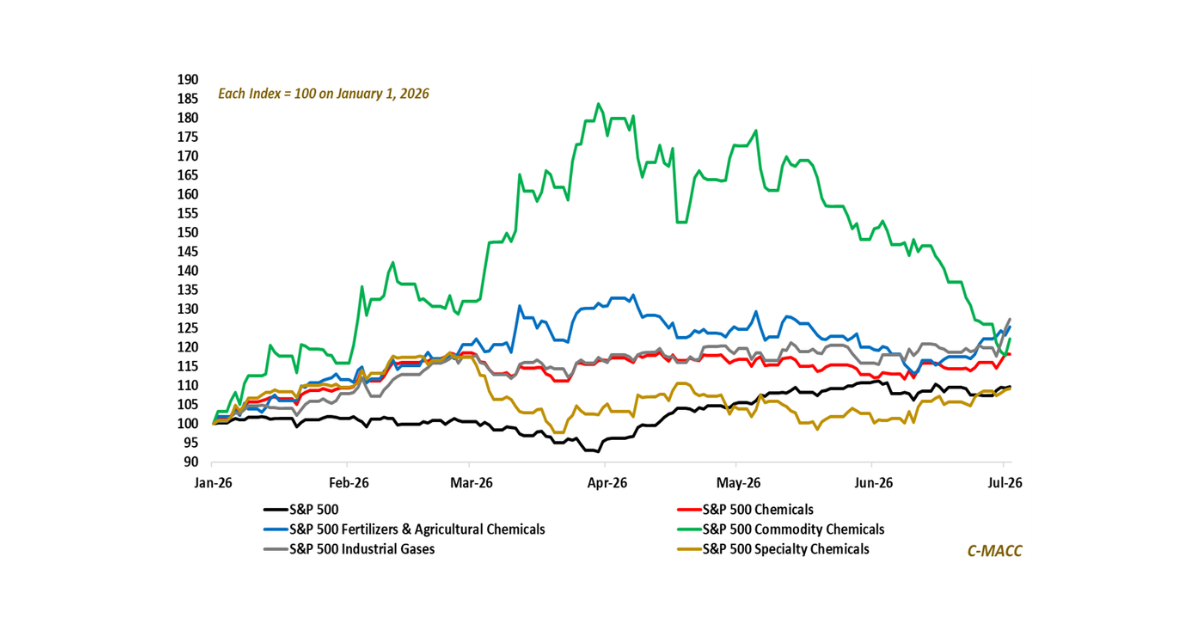
Sunday Executive Summary
Chemical equities are turning defensive again, but the split is sharper as commodity and specialty sentiment weakens while fertilizers and industrial gases retain support.
Consensus

Chemical equities are turning defensive again, but the split is sharper as commodity and specialty sentiment weakens while fertilizers and industrial gases retain support.
Consensus
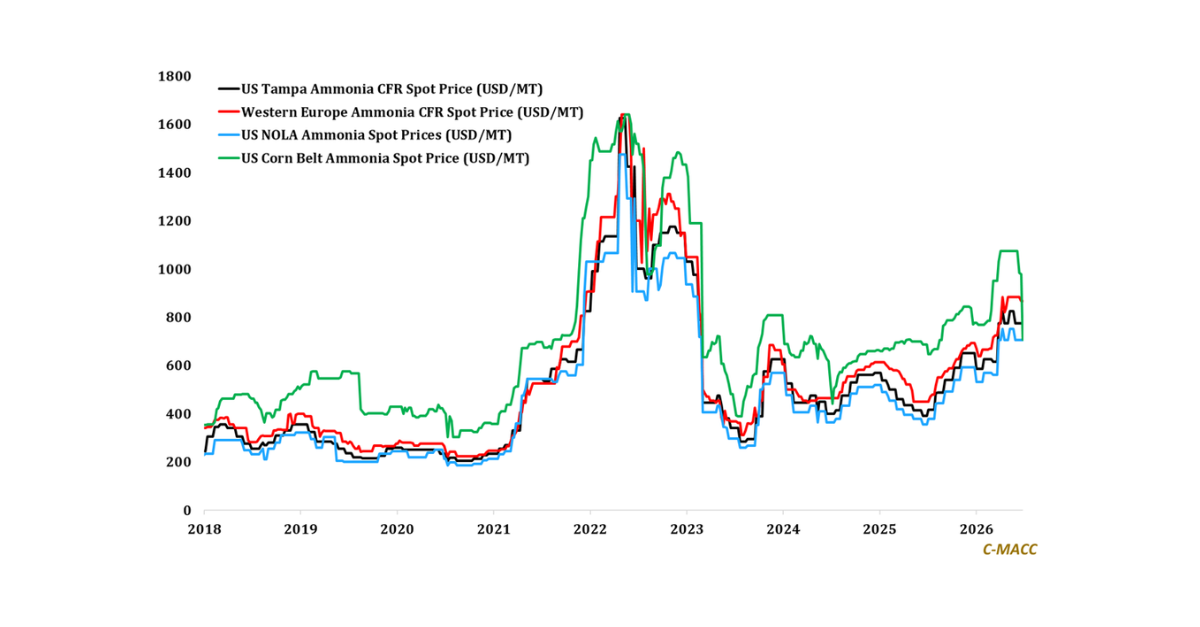
General Thoughts: Transition projects earn capital when future cash flow is visible before construction begins; high prices cannot carry weak offtake, open execution risk, or
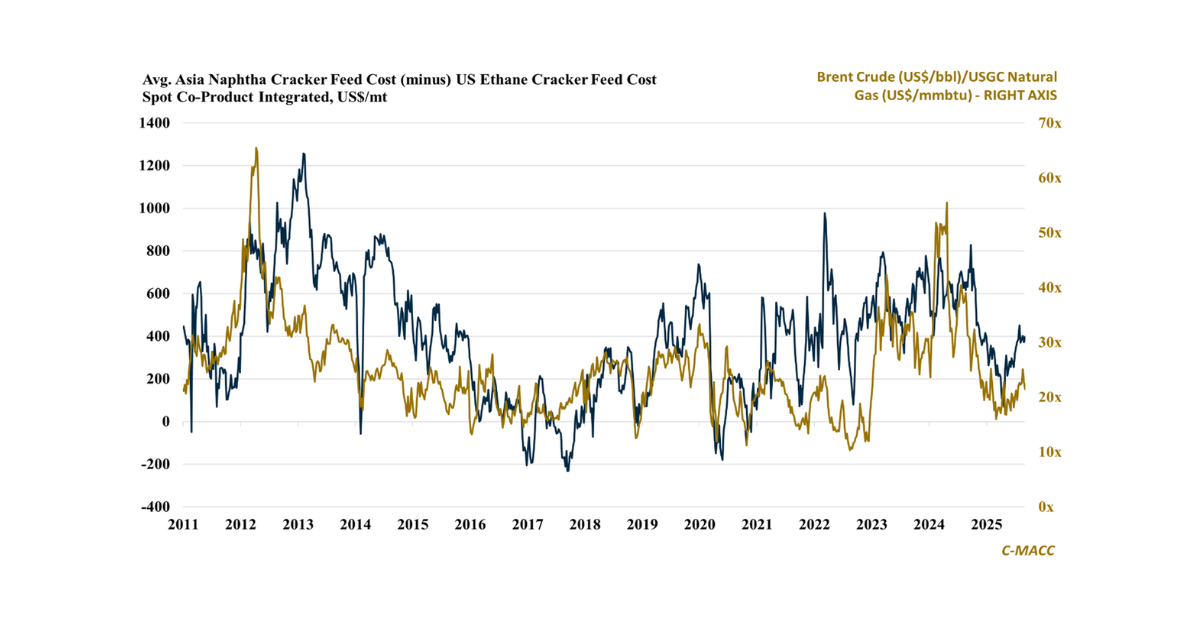
Structure, not scale, determines valuation, capital access, and resilience as oversupply, policy volatility, and higher rates punish complexity yet reward clarity, focus, optionality, disciplined execution,
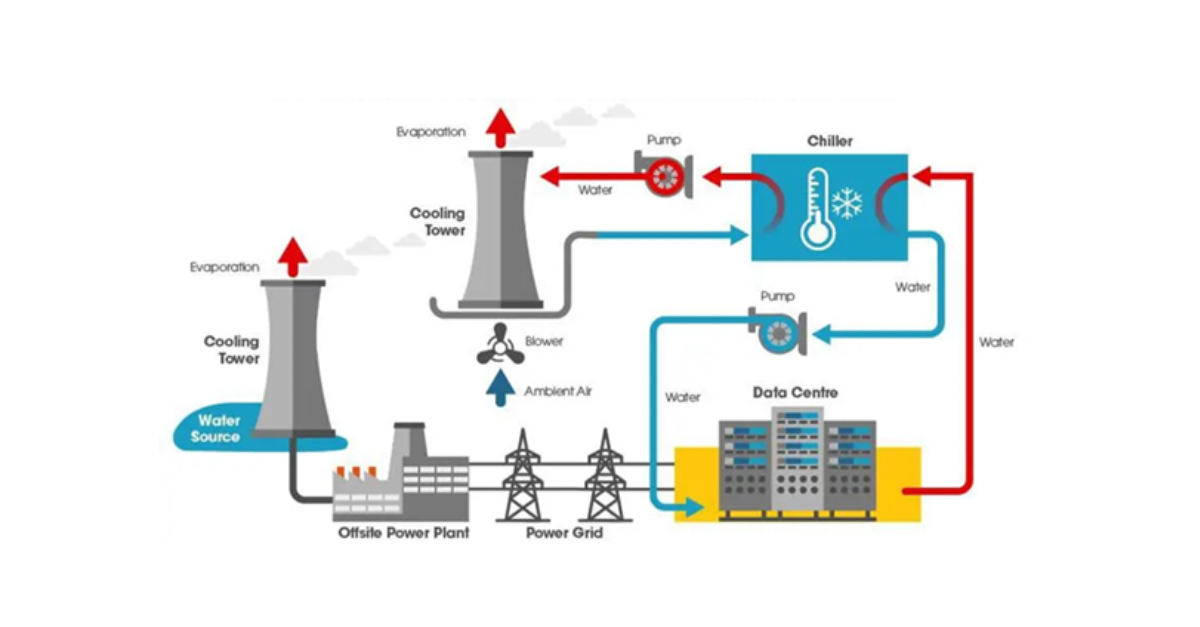
1st Topic of the Week: Water scarcity is AI’s hidden bottleneck, transforming data centers into hydrology-dependent assets. Will industry leaders secure resilient water strategies or
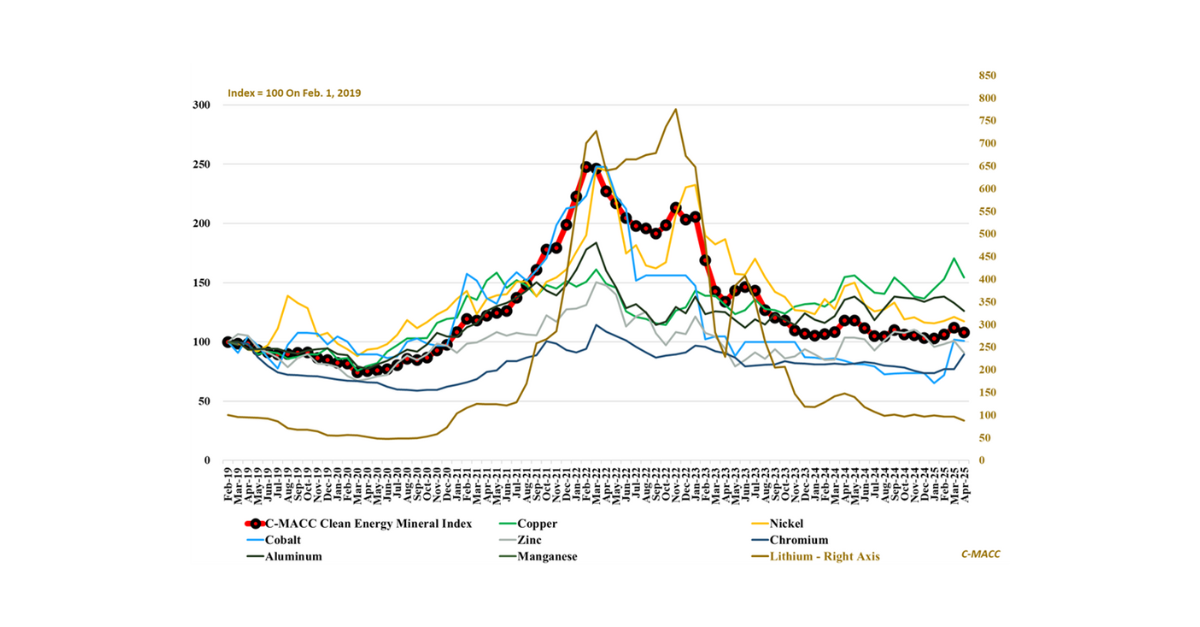
1st Topic of the Week: Global critical mineral market weakness exposes a more profound crisis: the West chases costly extraction as China solidifies its control
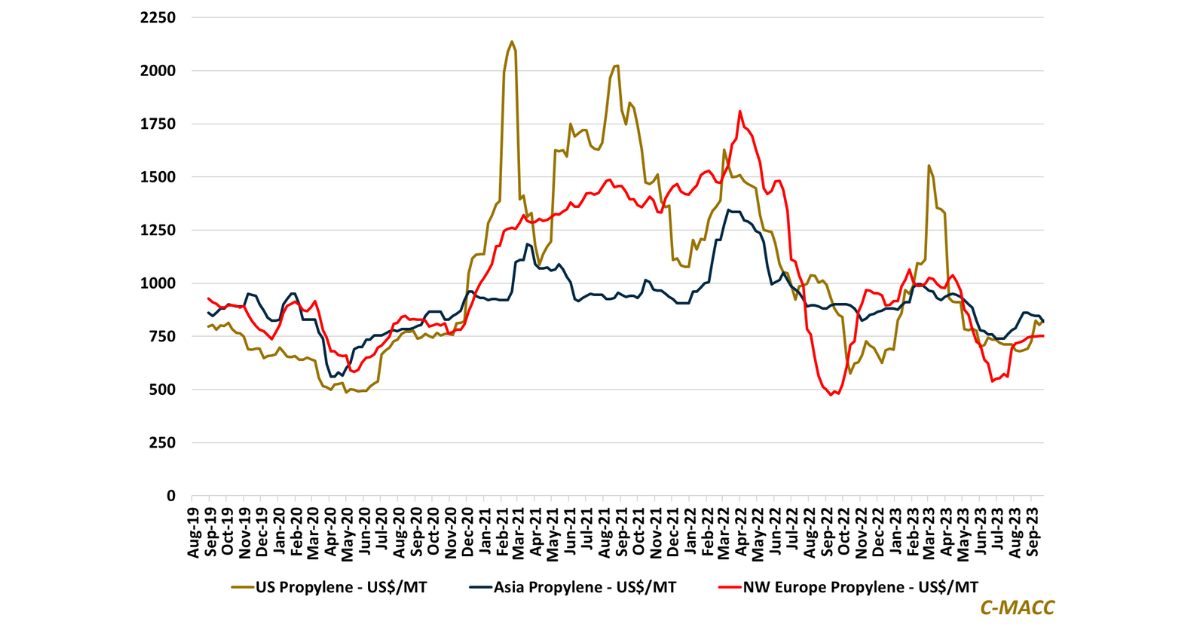
Non-integrated commodity chemical and specialty producers faced more input cost pressure in 3Q than planned mid-year due to higher feedstock costs and, in some cases,
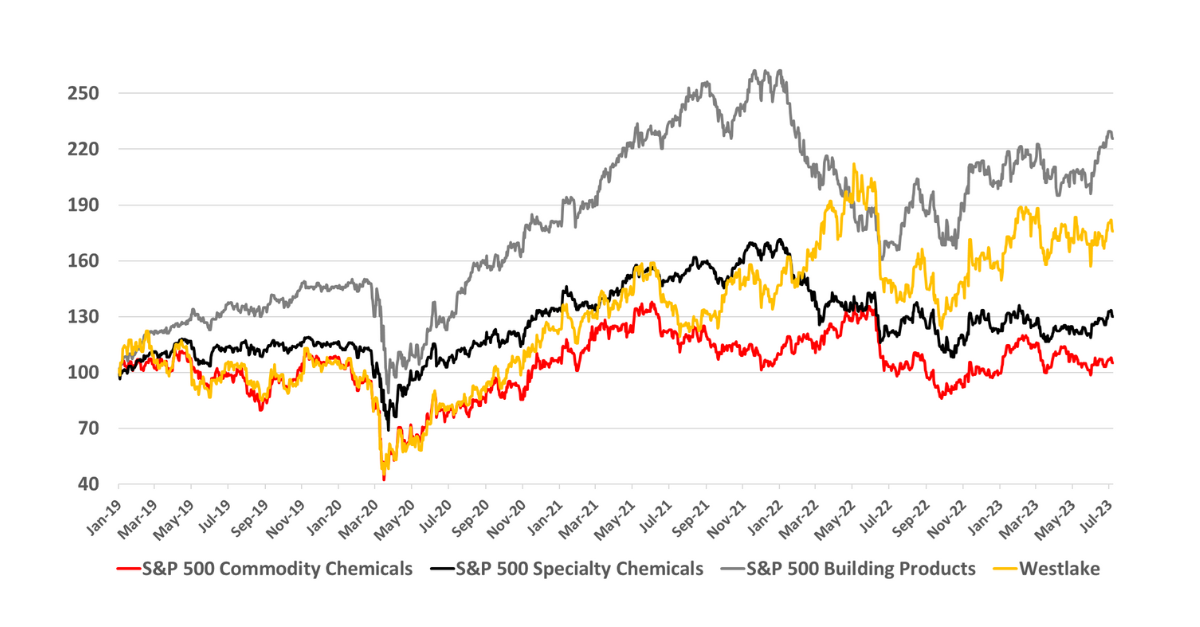
Building & construction product producers stand to benefit if the shortage of houses on the market spurs new home development, despite higher interest rates/lower buyer
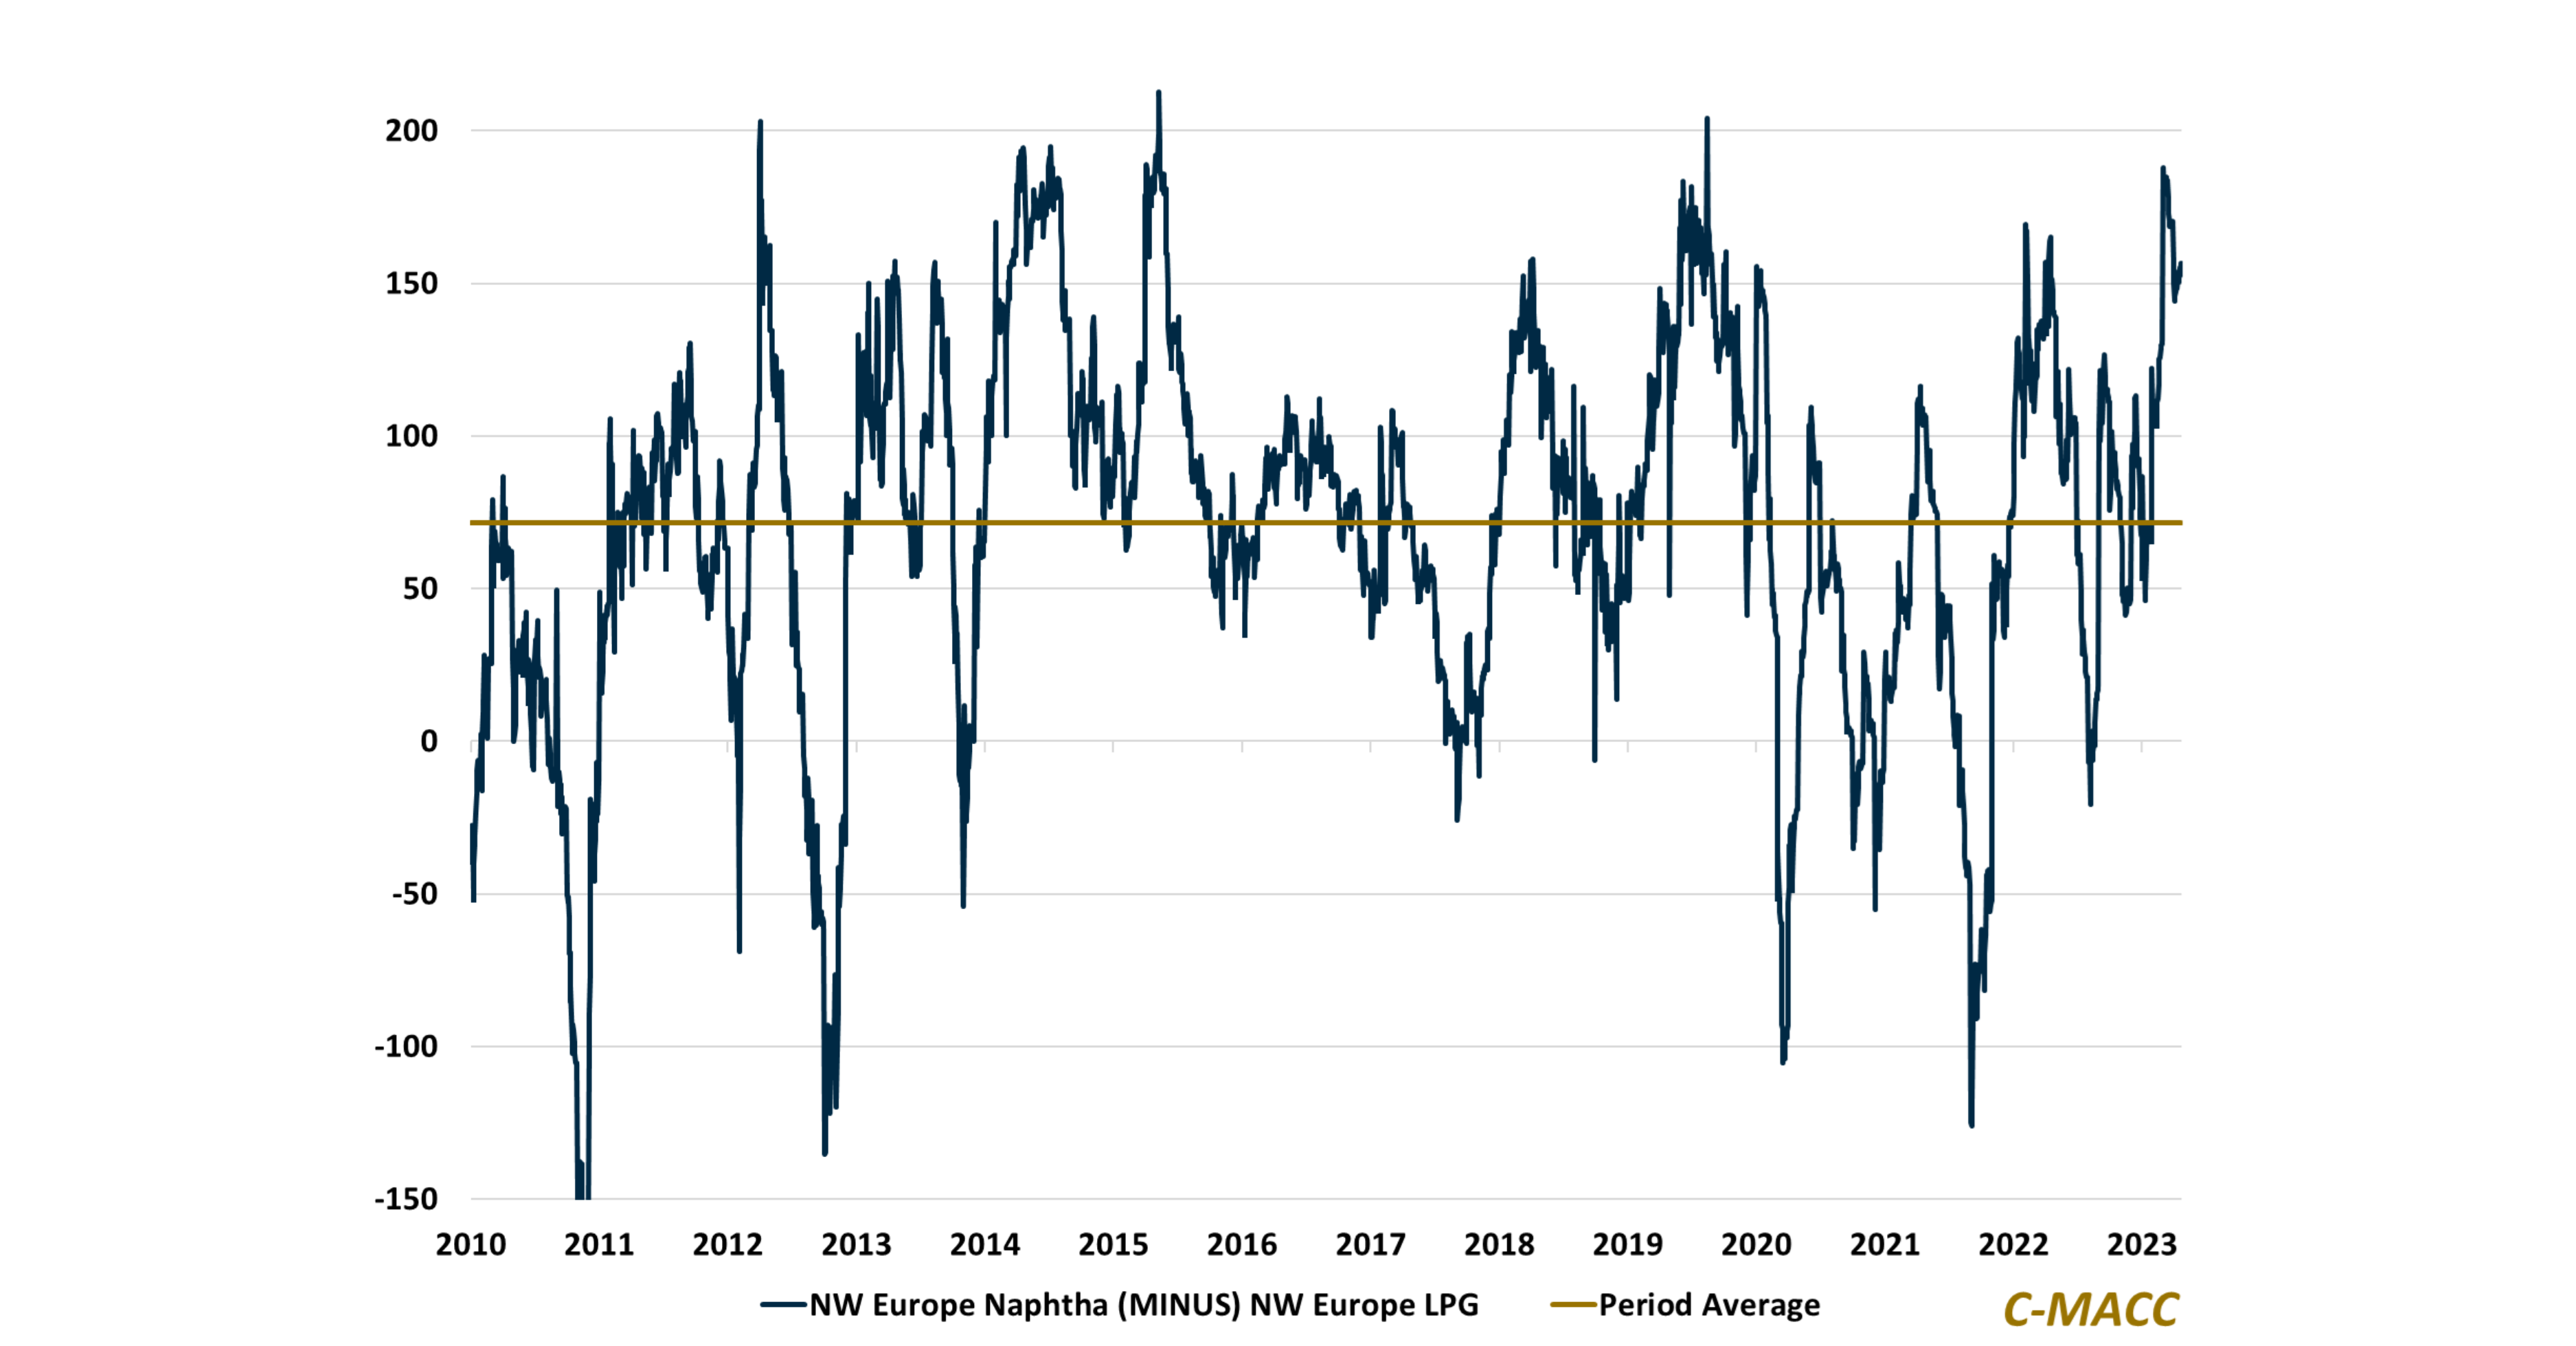
Some European chemical producers have seen costs decline YTD relative to others. However, our global market study shows Europe overall in a more difficult spot

The considerable downward pressure on global lithium prices YTD will likely push the C-MACC critical mineral index for April lower MoM, though its other components
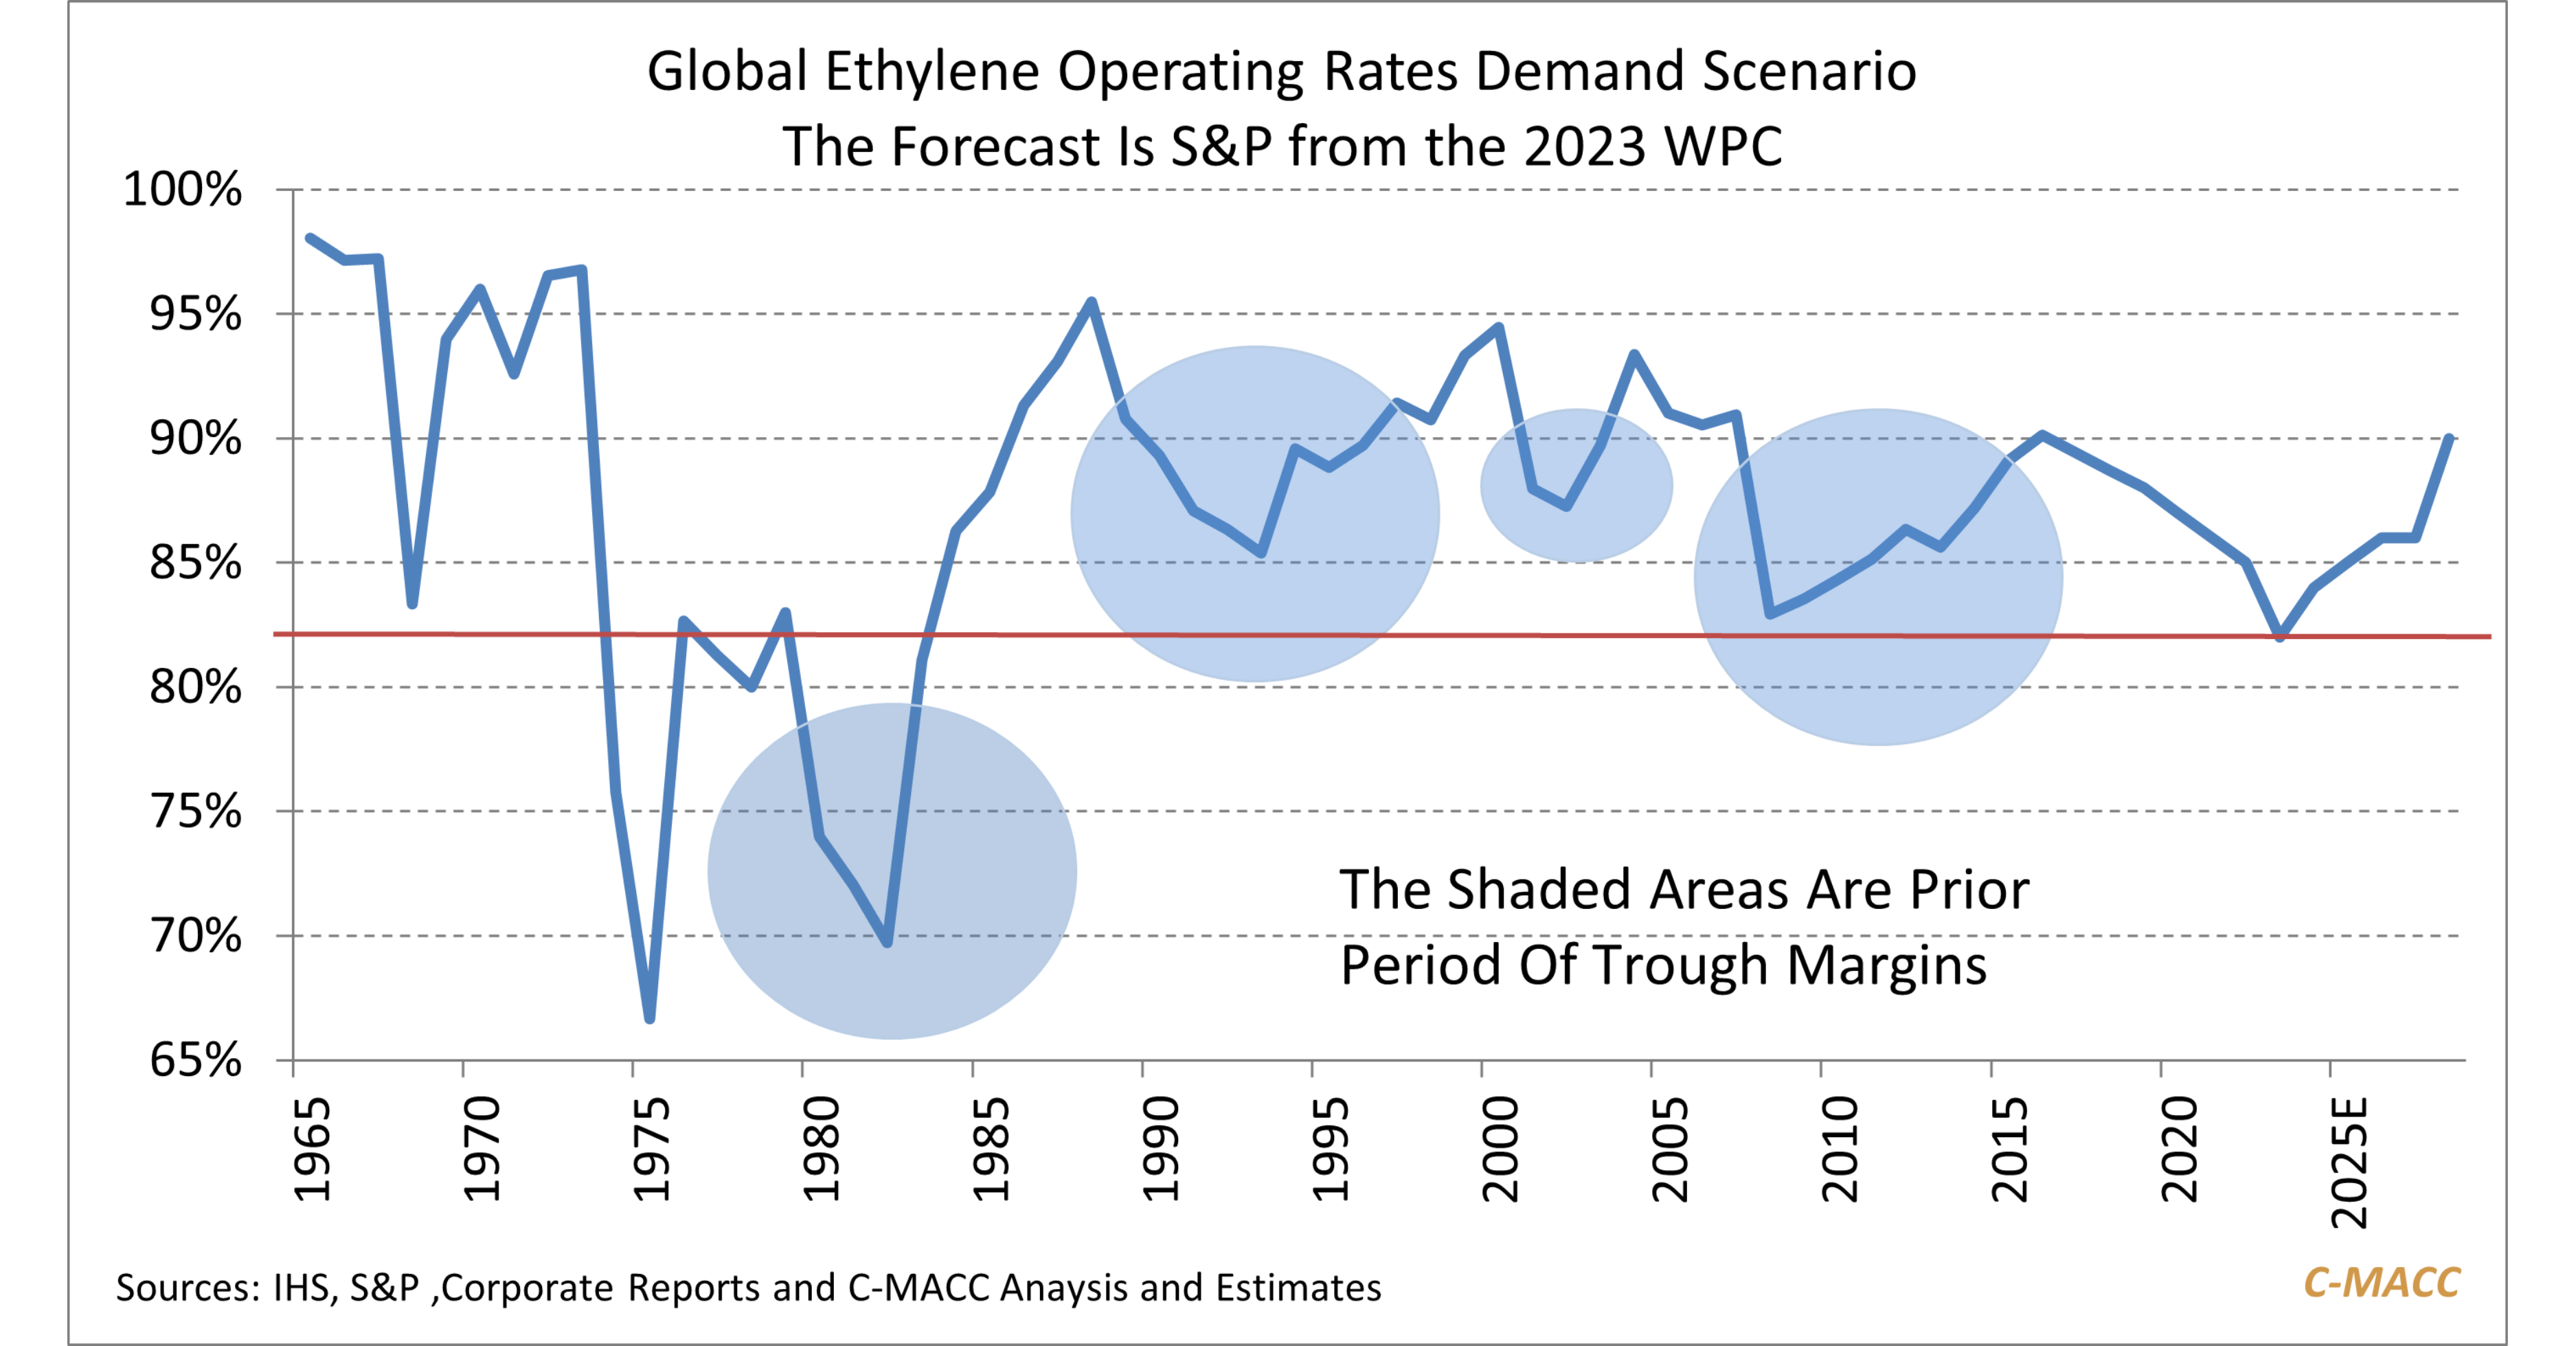
The projection at the WPC this week that polyethylene capacity will only operate at 80% rates in 2023 needs the context that this has not
