Sunday Executive Summary
Chemical capital is separating by model, with integrated producers funding hard-to-replicate advantages and customer-facing businesses demanding clearer economics before growth spending.
Dow’s collaboration with Amcor

Chemical capital is separating by model, with integrated producers funding hard-to-replicate advantages and customer-facing businesses demanding clearer economics before growth spending.
Dow’s collaboration with Amcor
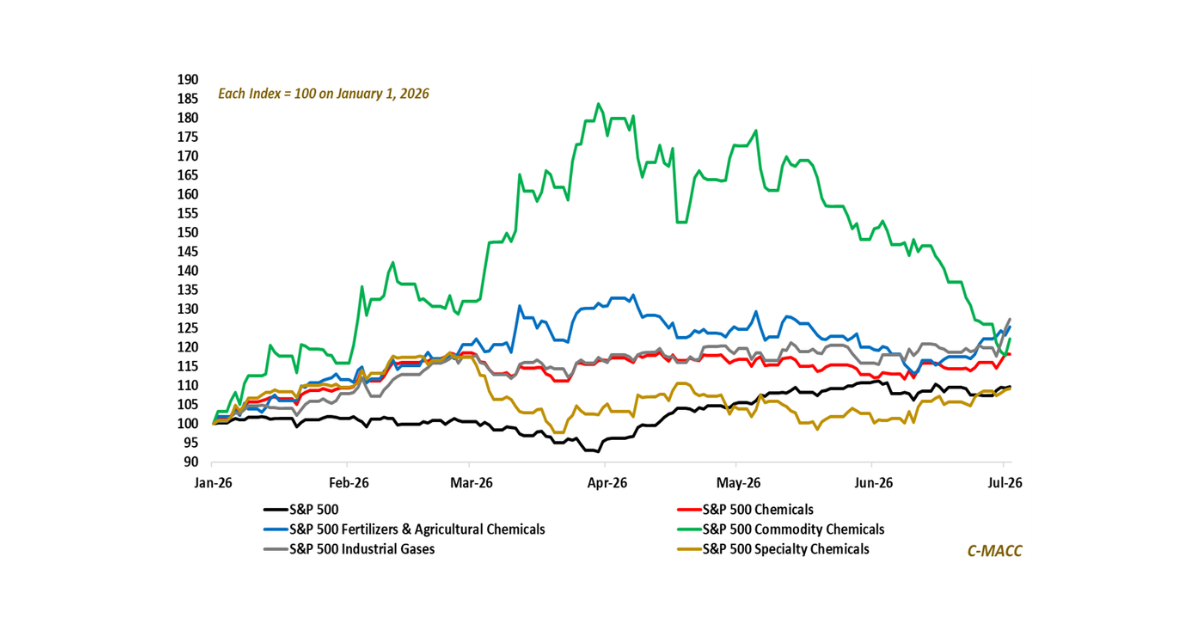
Chemical equities are turning defensive again, but the split is sharper as commodity and specialty sentiment weakens while fertilizers and industrial gases retain support.
Consensus
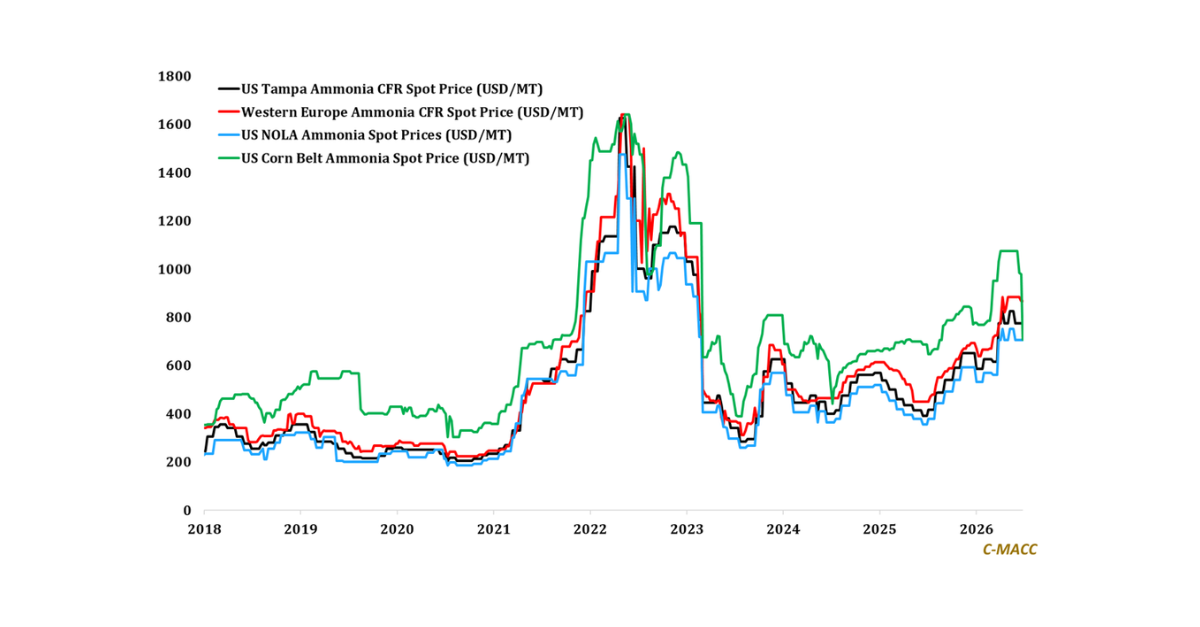
General Thoughts: Transition projects earn capital when future cash flow is visible before construction begins; high prices cannot carry weak offtake, open execution risk, or
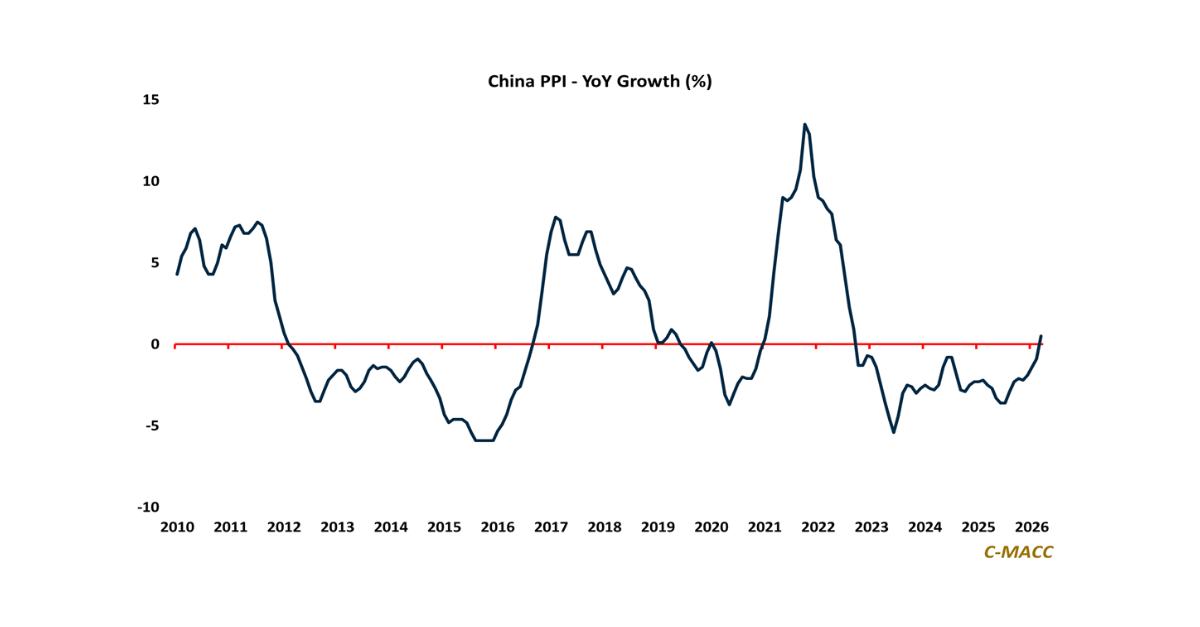
China’s 0.5% YoY factory-gate inflation in March removed a trusted global relief valve, forcing markets to underwrite firmer resin and intermediate floors, slower cost deflation,
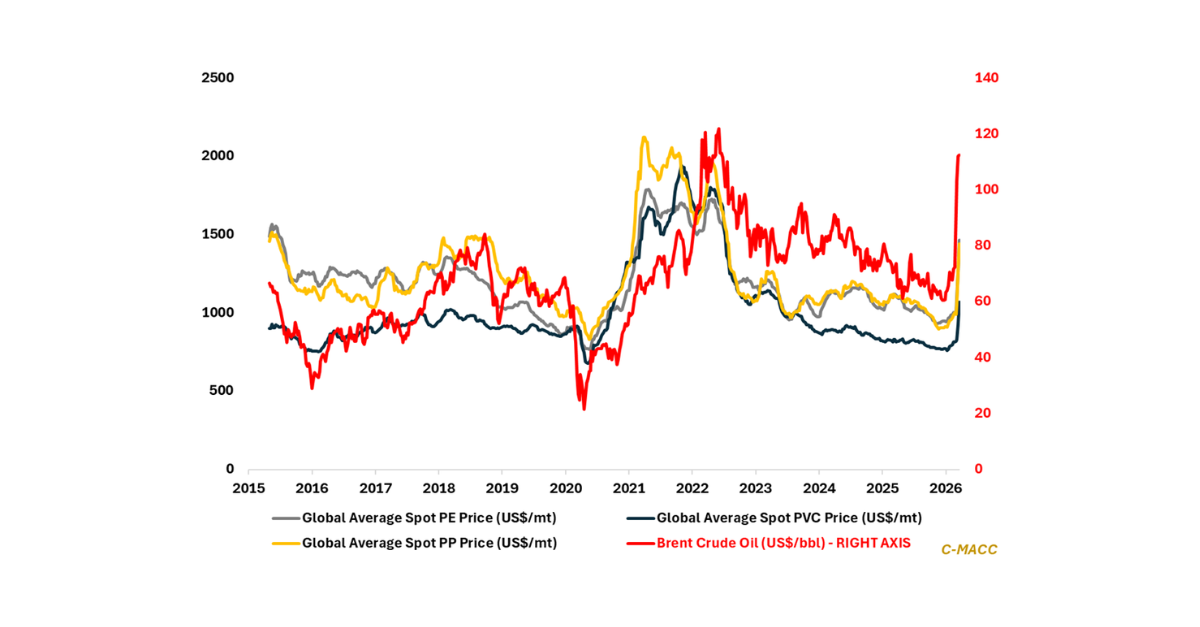
System constraints are compressing global corporate decision cycles, forcing capital into platforms that secure inputs, logistics, and execution simultaneously rather than optimizing sequentially across markets.
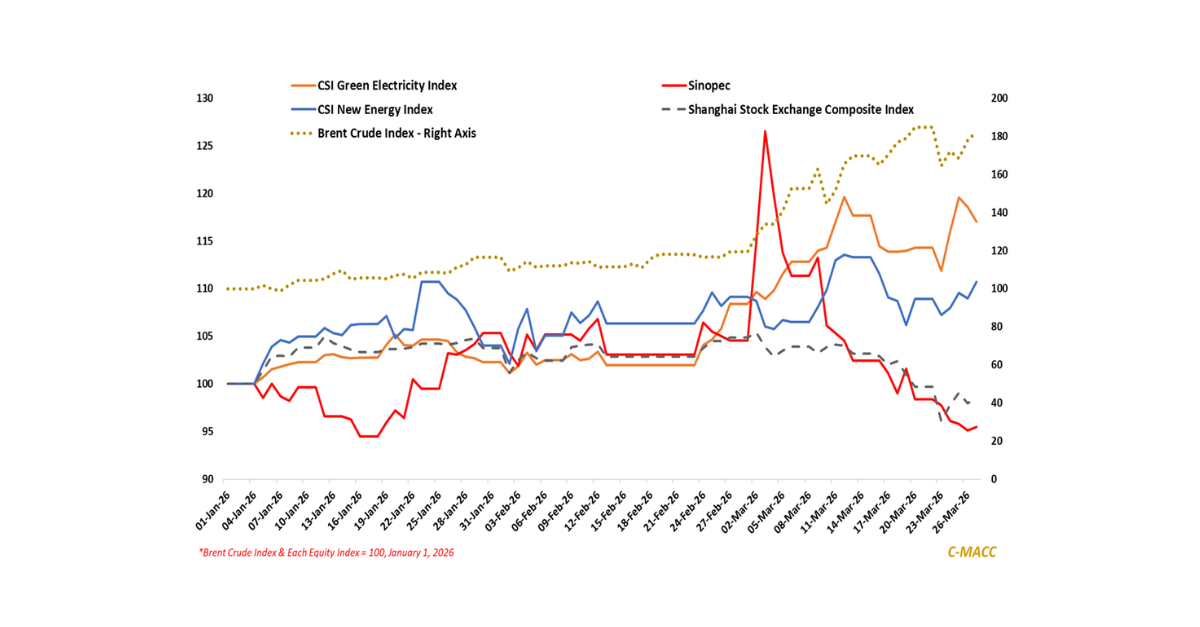
1st Topic of the Week: Capital is consolidating decisively around systems that either monetize energy scarcity or eliminate exposure to it, directing deployment decisions and
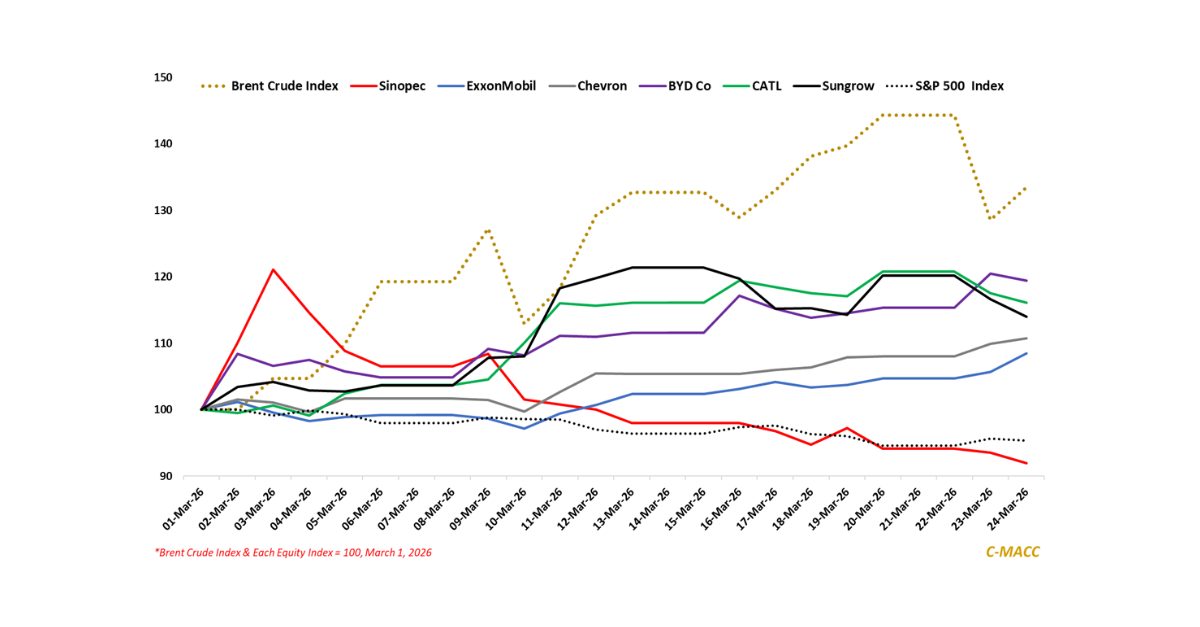
General Thoughts: Energy security is reshaping value chains, driving a bifurcation in which capital concentrates in low-cost hydrocarbons and in electrification, compressing high-cost industrial systems.
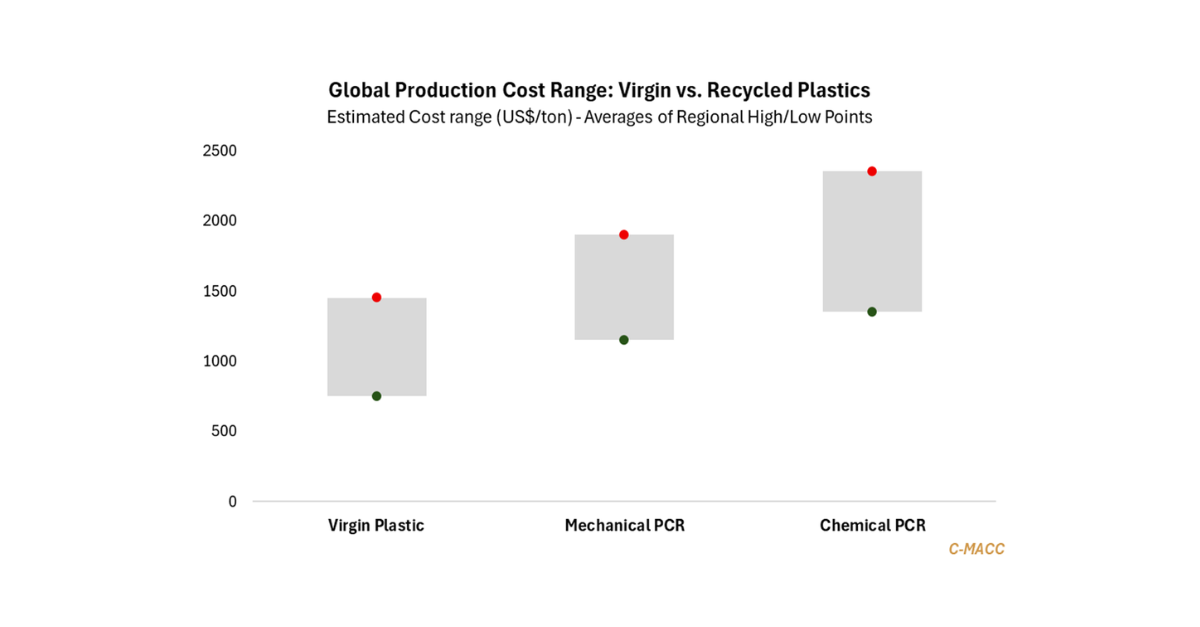
1st Topic of the Week: Energy-driven resin repricing narrows virgin-PCR gaps, benefiting circular adoption and shifting advantage toward suppliers that control feedstock, specification, and customer
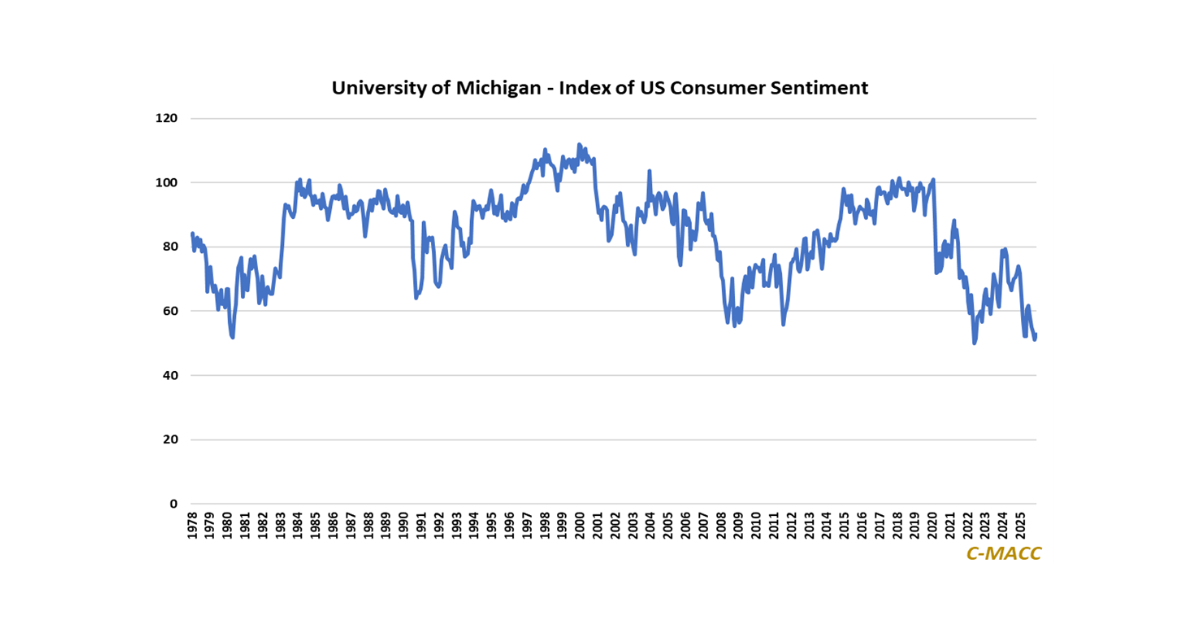
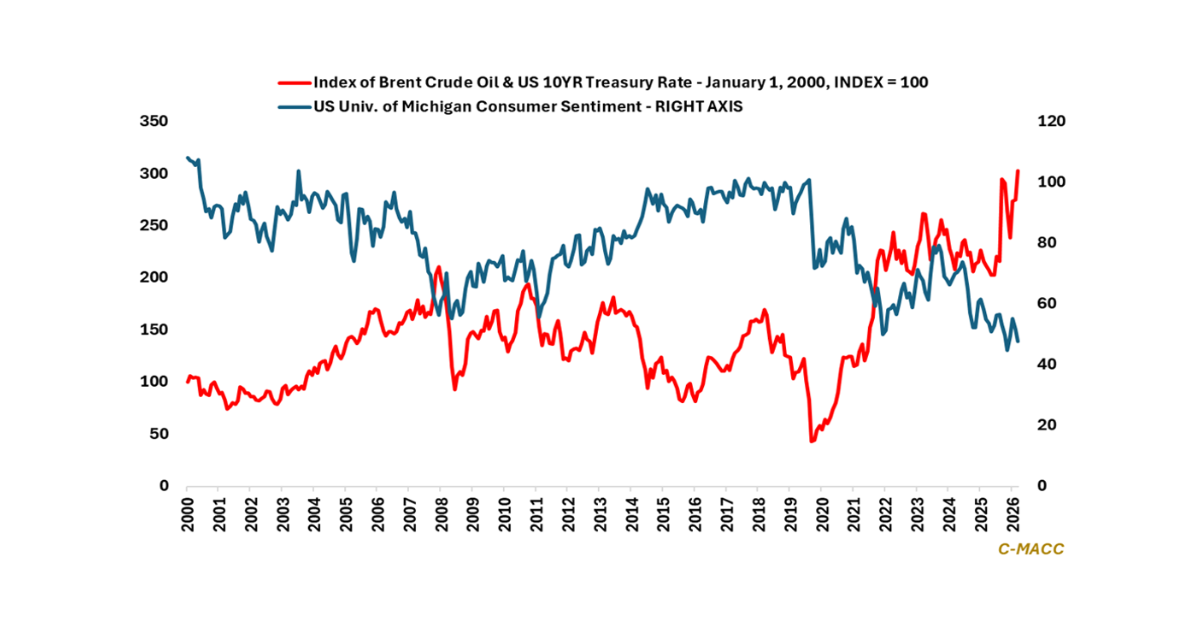
Depressed consumer sentiment and weak business expectations imply demand will not offset oversupply, with 2026 outcomes more likely to be determined by restructuring discipline rather
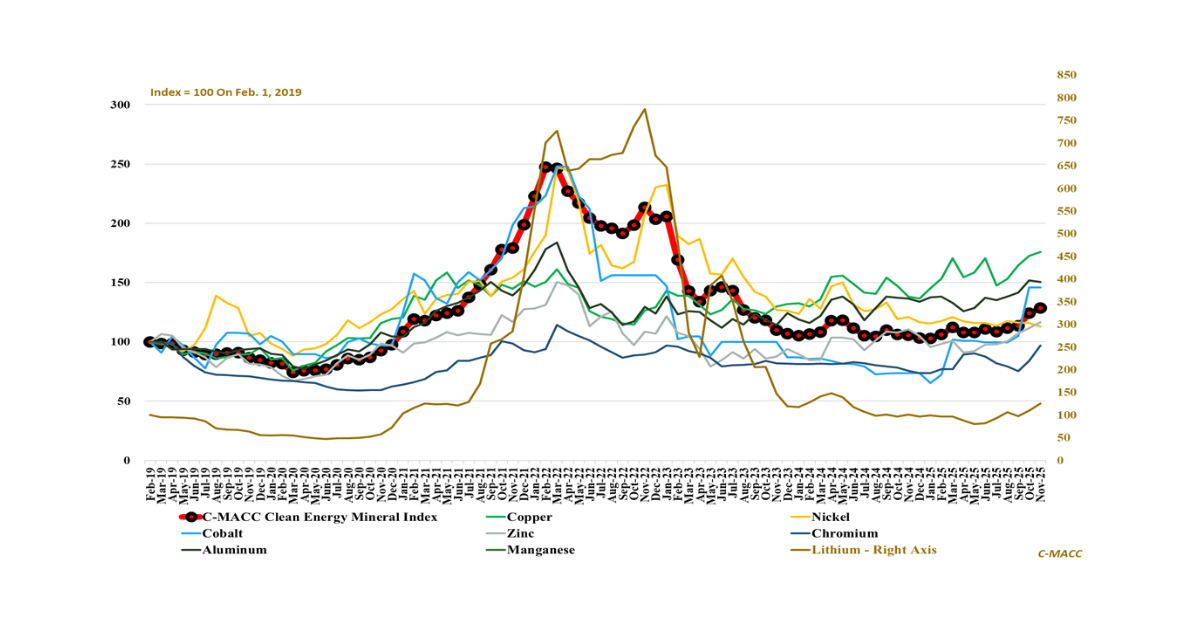
1st Topic of the Week: Recent mineral-market shifts reveal tightening copper and lithium balances, rising geopolitical risk, strategic mispricing, and more project delays; will scarcity-driven
