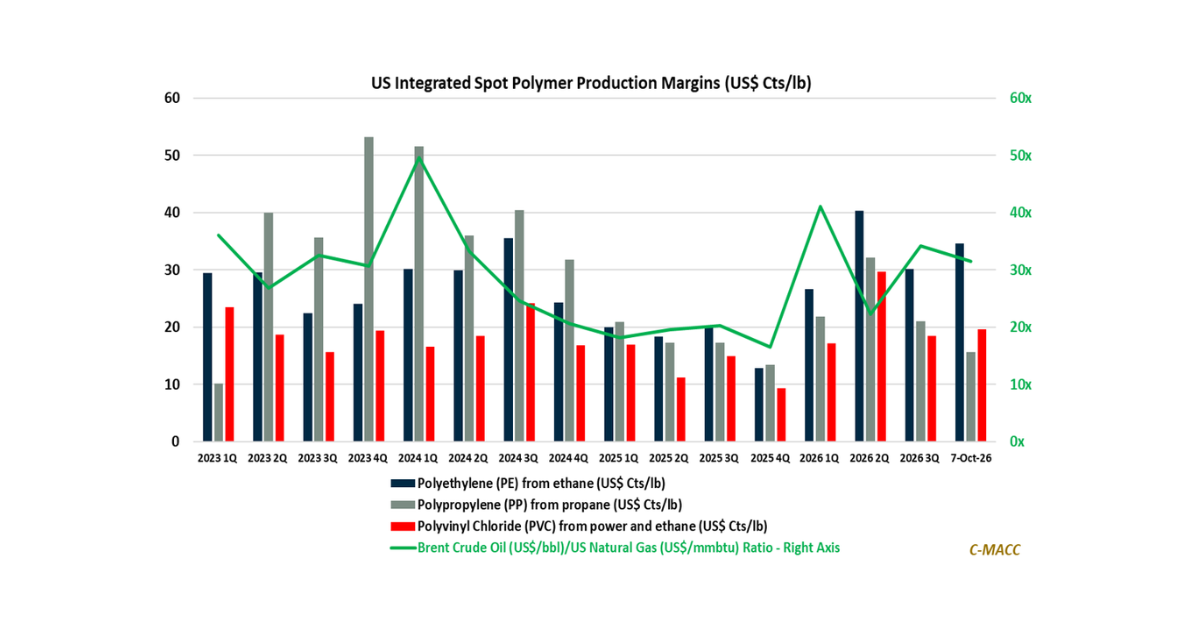
Polymer Global Analysis
General Thoughts: Analysts cutting 2026 estimates risk understating 2027 US PE and PVC earnings if supply assumptions overlook delayed capacity additions and prolonged Middle East

General Thoughts: Analysts cutting 2026 estimates risk understating 2027 US PE and PVC earnings if supply assumptions overlook delayed capacity additions and prolonged Middle East
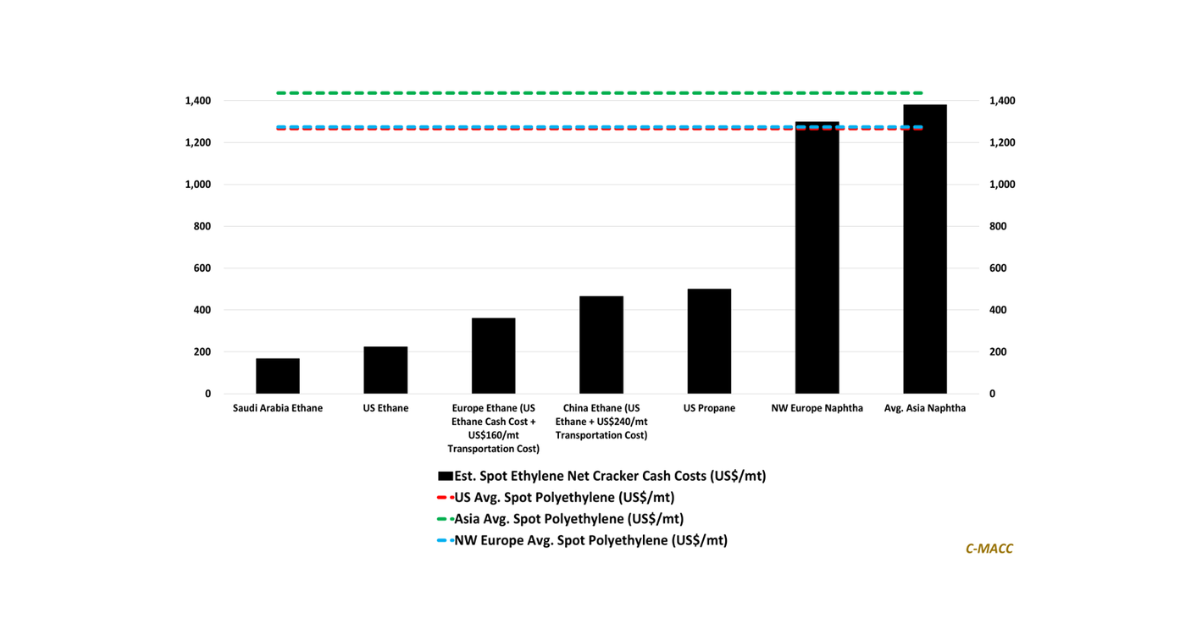
General Thoughts: Polymer supply disruptions can open customer accounts to competing suppliers, potentially extending price pressure beyond delivery constraints and limiting broad pricing gains expected
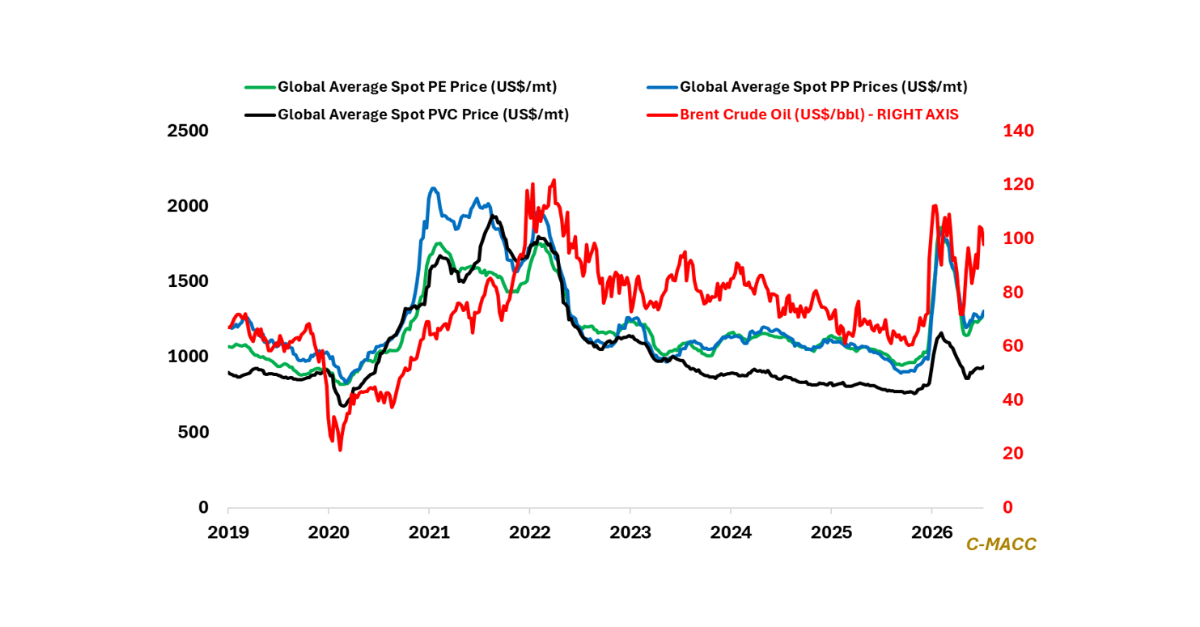
General Thoughts: Lower freight costs can erode polymer delivery premiums as cargoes arrive, while fresh financing may preserve competing output, challenging expectations that higher prices
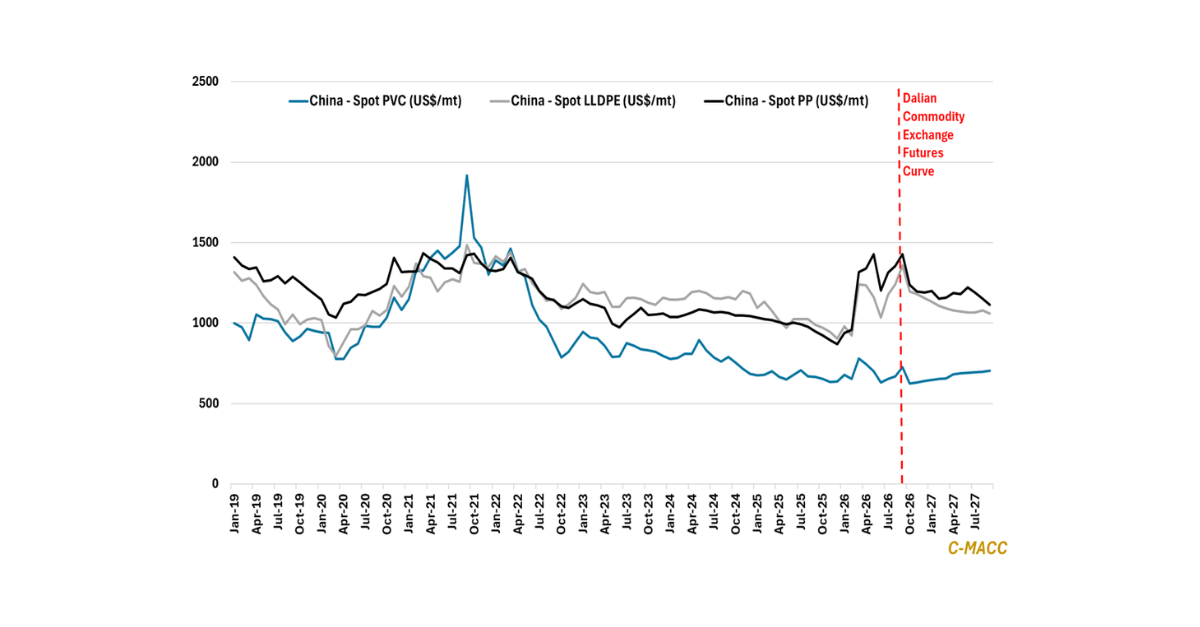
General Thoughts: Chinese PVC, PE, and PP spot prices have strengthened from midyear lows, while Dalian futures suggest steadier PVC support as PE and PP
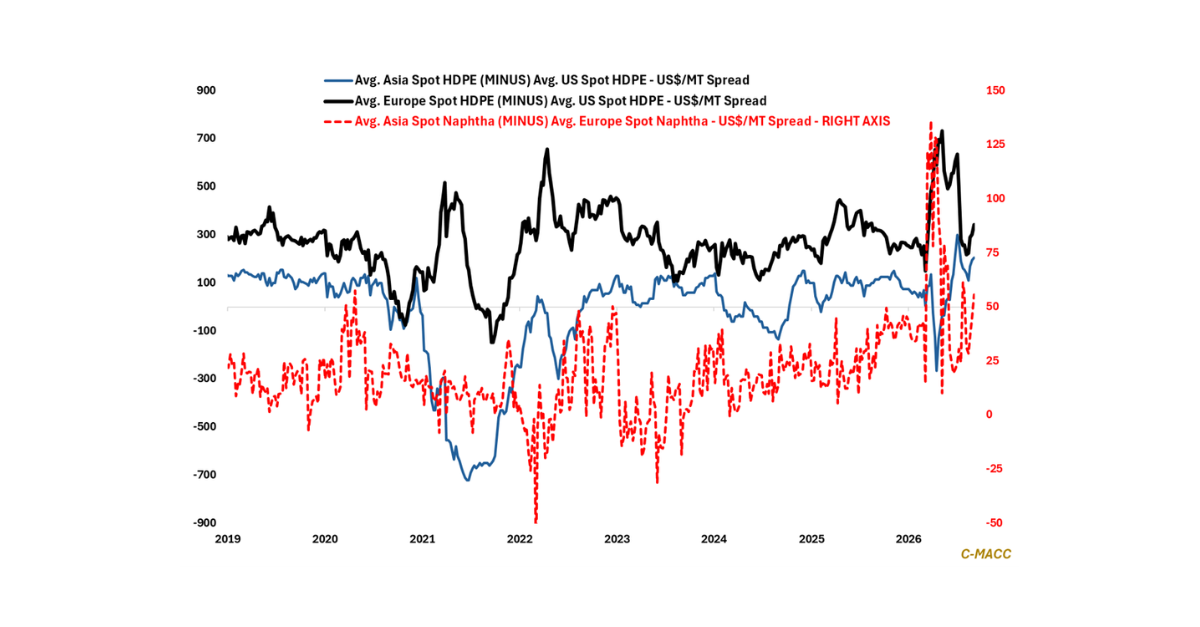
General Thoughts: Overseas HDPE premiums give US producers more export options, but growing supply will test how much of that advantage survives freight, customer access,
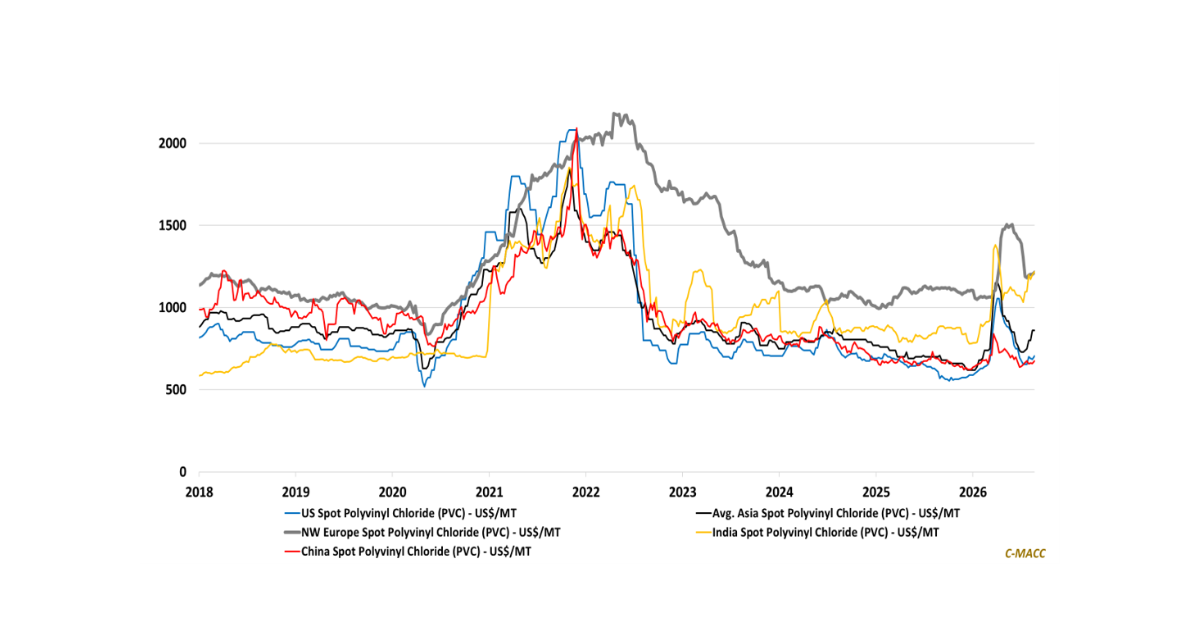
General Thoughts: Polymer markets show selective improvement, as higher costs support seller positions and regional barriers favor advantaged producers, while ample global capacity keeps broader
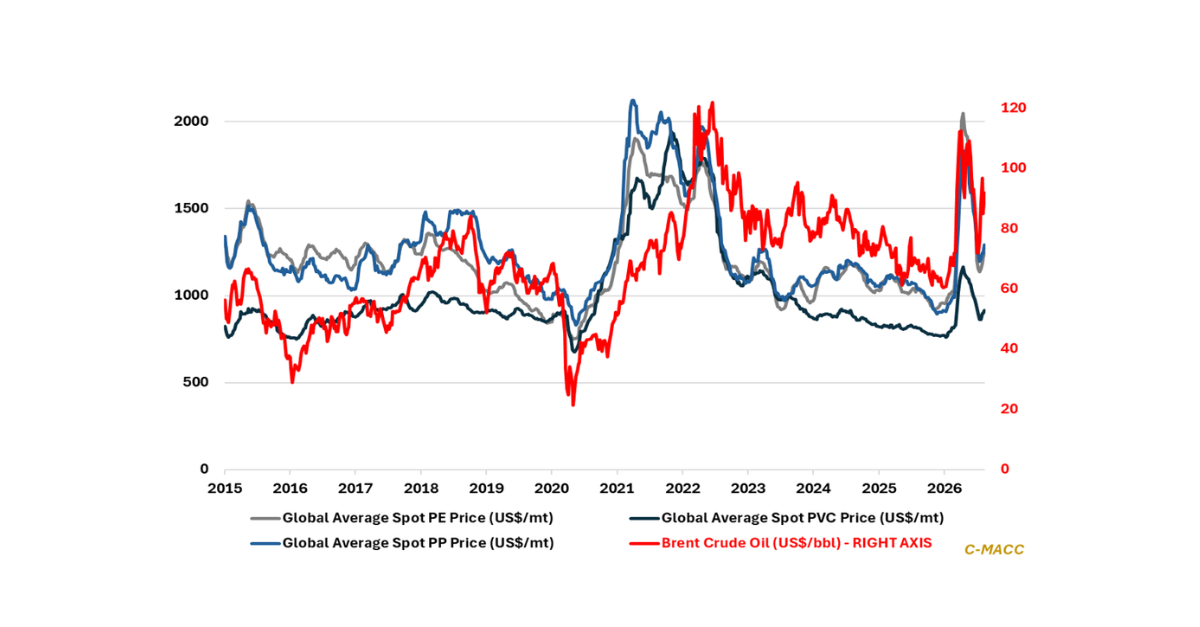
General Thoughts: Higher oil-linked feedstock costs are lifting polymer prices, but spare capacity is limiting producer leverage and increasing the strategic value of North America’s
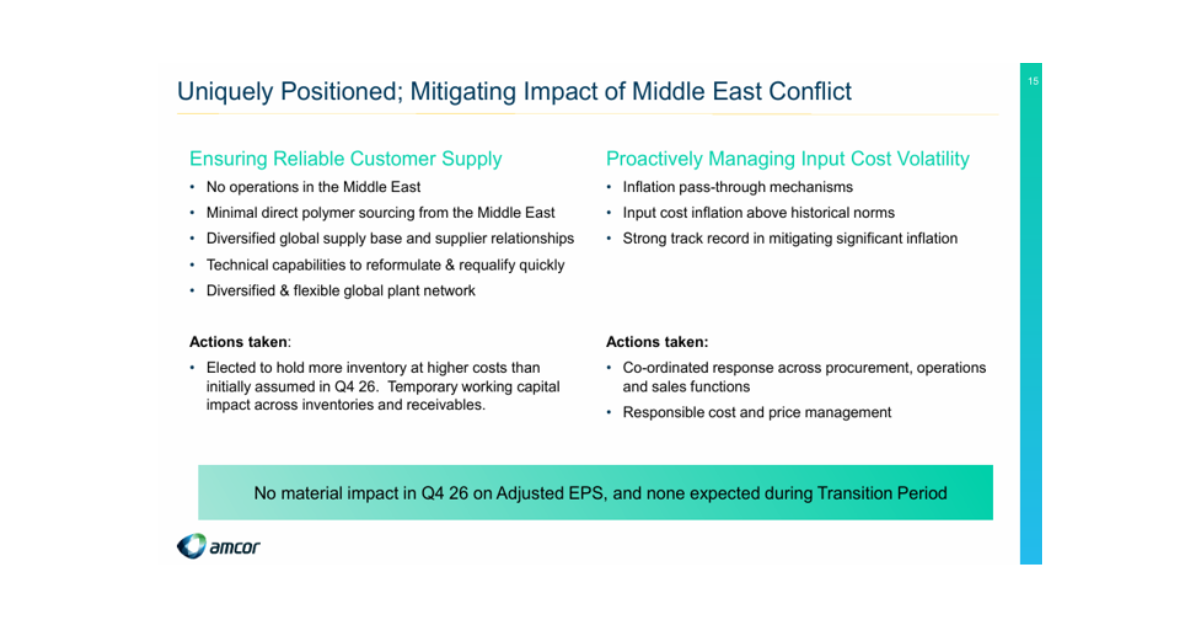
General Thoughts: Polymer volatility is exposing which business models can protect earnings without sacrificing customers, leaving cash conversion and margin quality more differentiated than headline
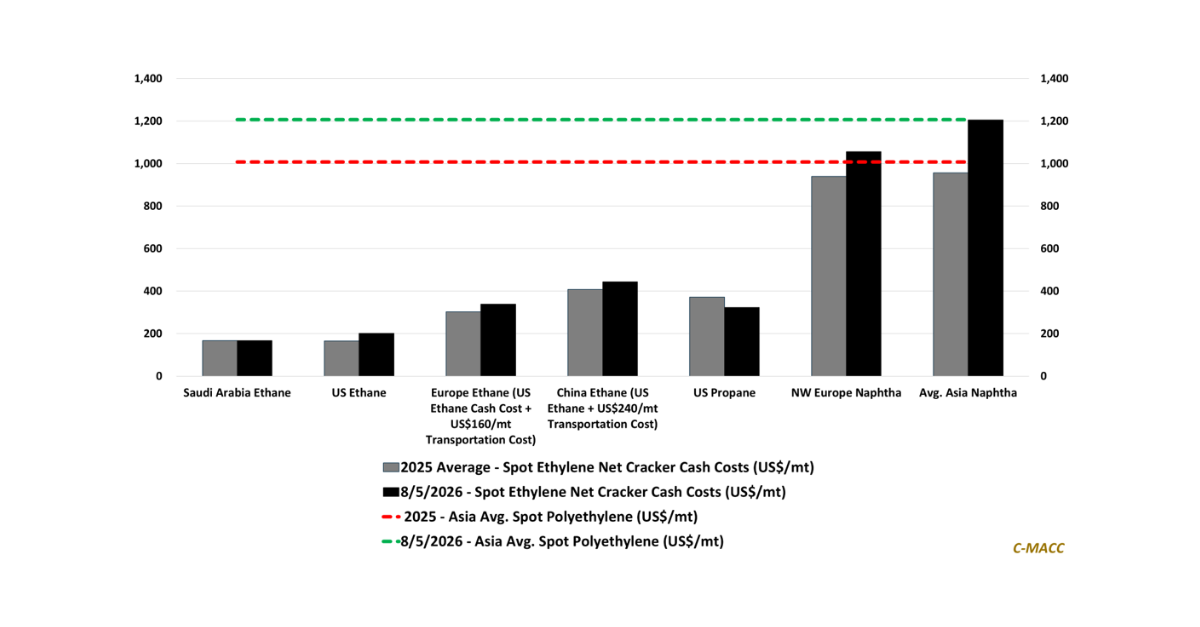
General Thoughts: Asia’s naphtha premium over Europe should persist through 2H26, supporting demand for US ethane access as softer crude lowers costs but weak polymer

General Thoughts: Middle East risk is accelerating Asia’s olefins restructuring, creating more opportunity for North American share gains than for broad pricing power as Chinese
