Base Chemical Global Analysis
Global Weekly Catalyst No. 294
- General Thoughts: Global chemical markets fracture along cost lines, as weakening US feedstock prices boost its margins while overseas chemical producers wrestle with pricier feedstock, oversupply, and restructuring needs.
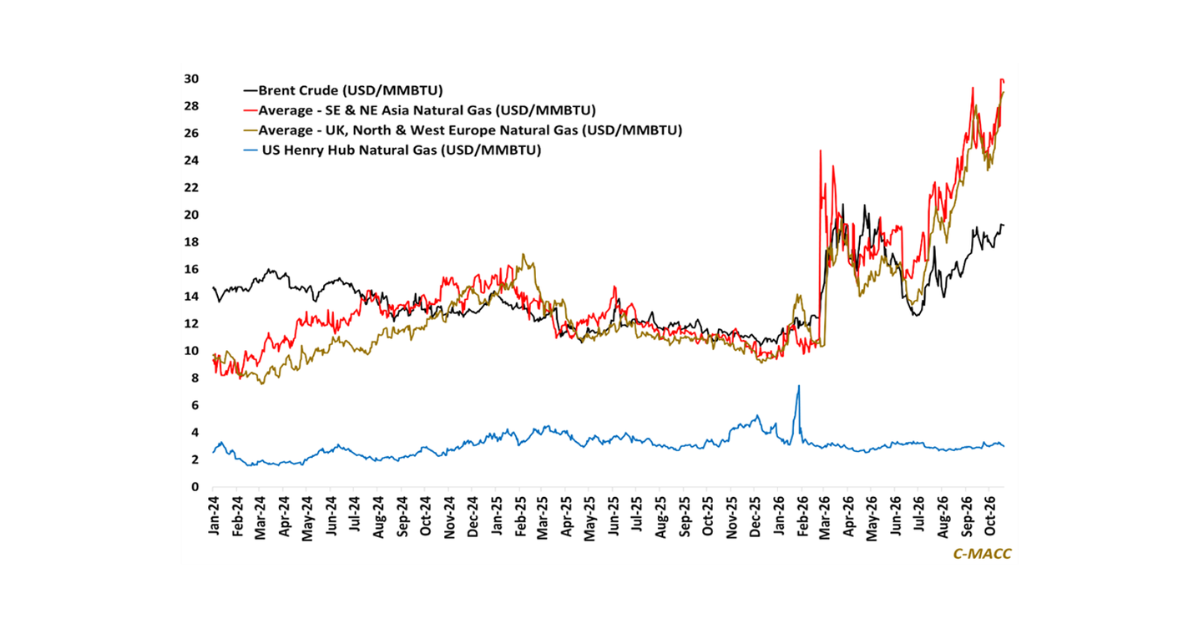
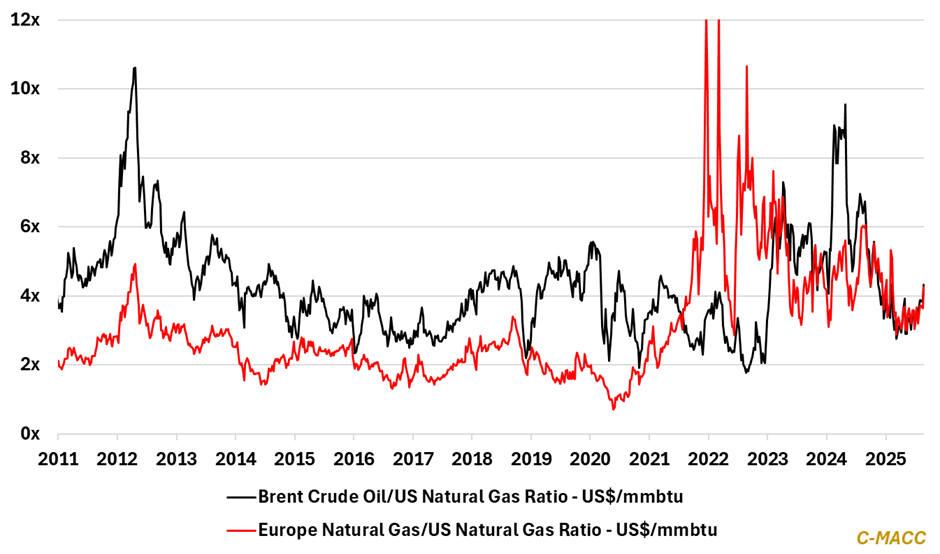
- Feedstocks & Energy: Brent crude oil and Ex-US natural gas prices have risen relative to US natural gas in 3Q25, which has steepened the global petrochemical cost curve, favoring more restructuring activity in Asia Ex-China.
- Olefins: Weak splitter economics and PDH production issues on the USGC suggest likely PGP prices support in the near-term, despite still weak derivative demand. PGP-to-derivative spreads will likely remain tight in 2H25.
- Other Base Chemicals: Benzene softness, Europe’s methanol surge, and China’s acetic acid slump highlight cost-position and integrated production supremacy as oversupply deepens margins’ seasonal fragility into late 2025.
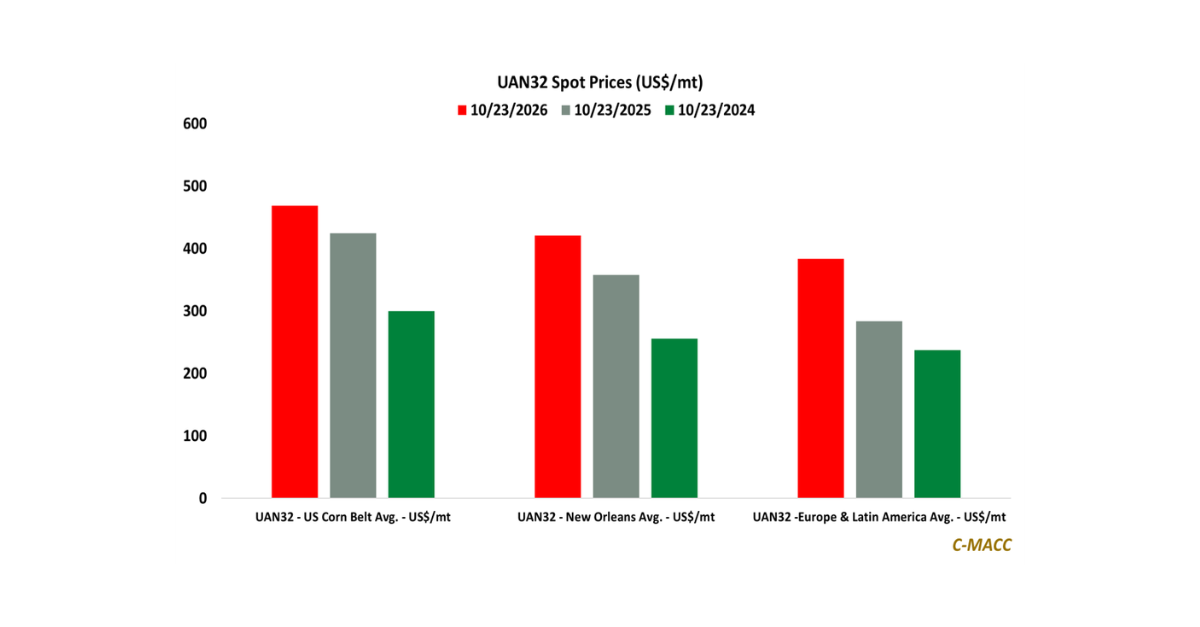
- Agriculture: US ammonia margins lift on strong US cornbelt pricing and lower US natural gas costs, yet looming demand erosion tempers optimism until structural tightening reshapes global markets post-2026, per our model.
- Refining & Biofuels: US ethanol margins hit 2025 highs on corn weakness and overseas support, outshining US refining gains, despite their also being at a 2025 high, as ethanol margins position for a relatively stronger 2H25.
Exhibit 1 – Chart of the Day: Brent crude oil and EU natural gas are at or near YTD highs relative to USGC natural gas.
Source: Bloomberg, C-MACC Analysis, August 2025
Client Login
Learn About Our Subscriptions and Request a Trial
Contact us at cmaccinsights@c-macc.com to gain full access and experience our services!