Polymer Global Analysis
Resin To Riches: Weekly Plastic Market Insights
- General Thoughts: Policy-driven displacement, entrenched oversupply, and tight spreads define global polymers, driving consolidation, advantaged feedstock dominance, and prolonged troughs until demand returns.
- Polyethylene (PE): Relentless PE oversupply, policy reshuffles, and structural feedstock advantages drive global rationalization and consolidation, prolong weak prices, and ensure the survival of low-cost integrated producers.
- Polypropylene (PP): Tight PP-to-PGP spreads, entrenched oversupply, and accelerating rationalization define global PP arbitrage, as surging Chinese exports and Europe/Turkey lows anchor markets until demand recovery.
- Polyvinyl Chloride (PVC): Tariff shocks, collapsing US export prices, and displaced volumes anchor PVC markets at pandemic-era lows, as India’s ADD-fueled premium underscores distorted trade flows and prolonged margin pressure.
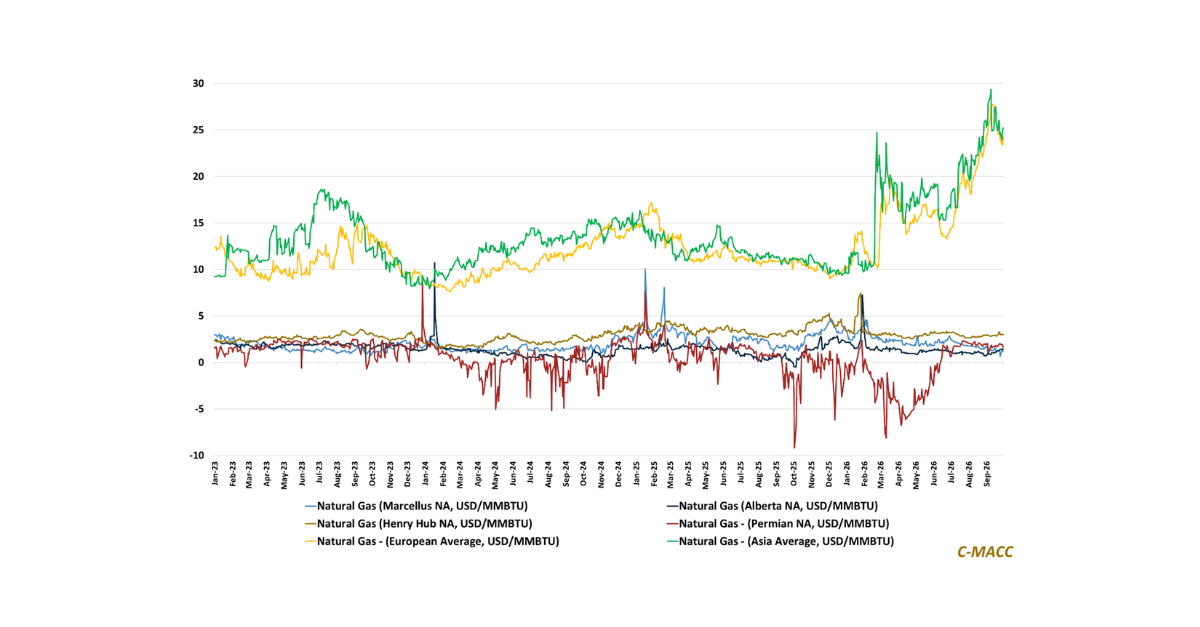
- Other Sector Developments: In recent weeks, US natural gas and ethane prices have risen relative to crude oil and Ex-US naphtha, keeping global polymer prices in check while pinching North American margins.
Exhibit 1 – Chart of the Day: Policy displaces China and US PVC into permissive hubs, setting the global clearing price.
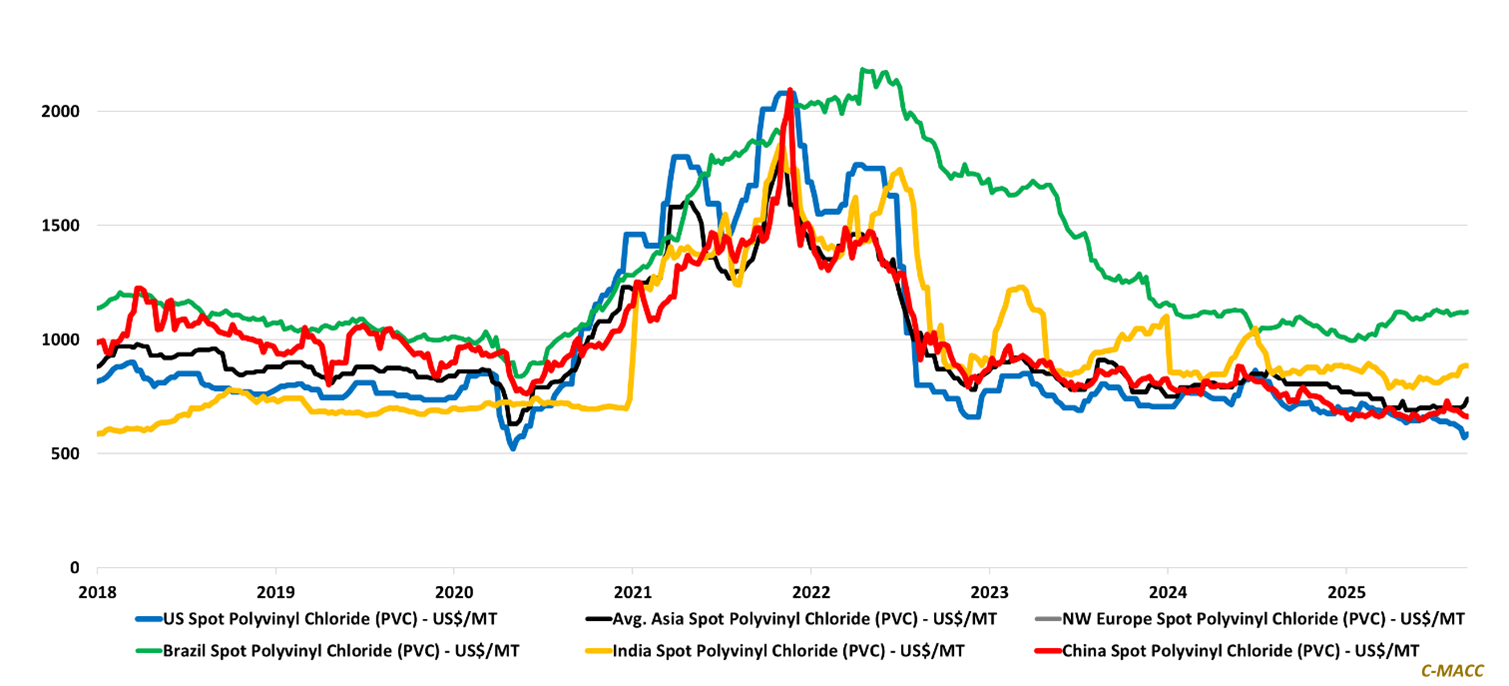
Source: Bloomberg, Company Reports, C-MACC Analysis, September 2025
Client Login
Learn About Our Subscriptions and Request a Trial
Contact us at cmaccinsights@c-macc.com to gain full access and experience our services!