Base Chemical Global Analysis
Global Weekly Catalyst No. 349
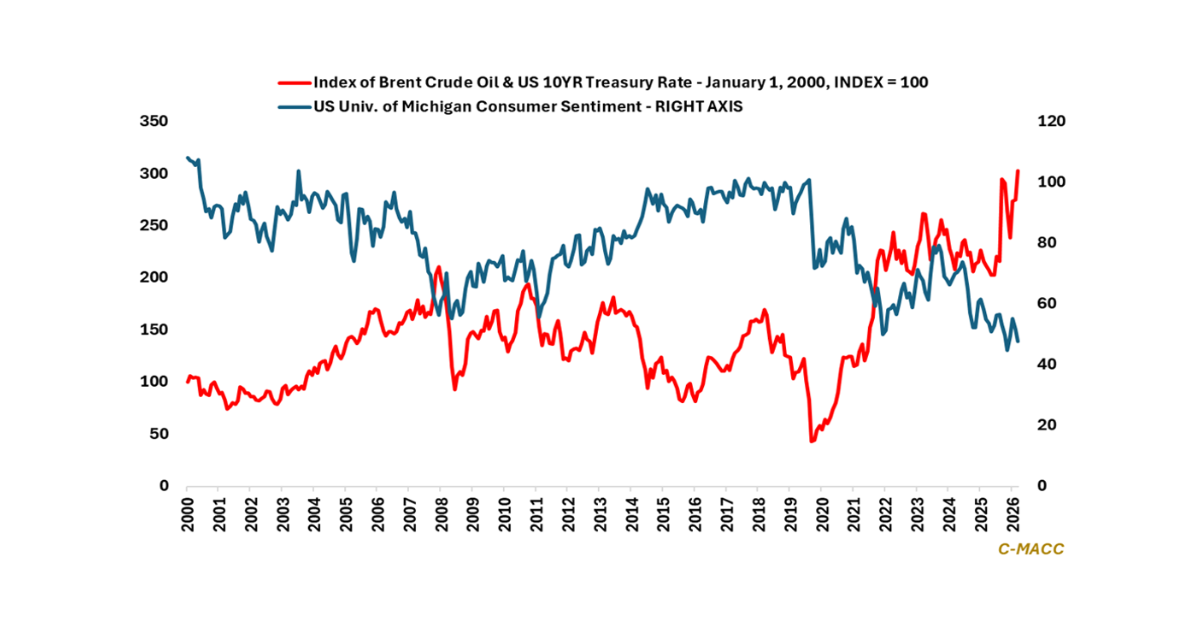
- General Thoughts: Softer crude and weak demand could encourage downstream customers to seek discounts before intermediate costs ease, leaving merchant producers to absorb the difference through lower margins.
- Feedstocks & Energy: Asian naphtha rose as crude eased, and Rhine freight threatens European savings, leaving delivered feedstock costs slow to reflect lower oil prices at exposed chemical plants.
- Olefins: October turnarounds could support Asian olefins until imports arrive; higher European co-product prices may sustain cracker output, delaying the ethylene supply cuts buyers might otherwise expect.
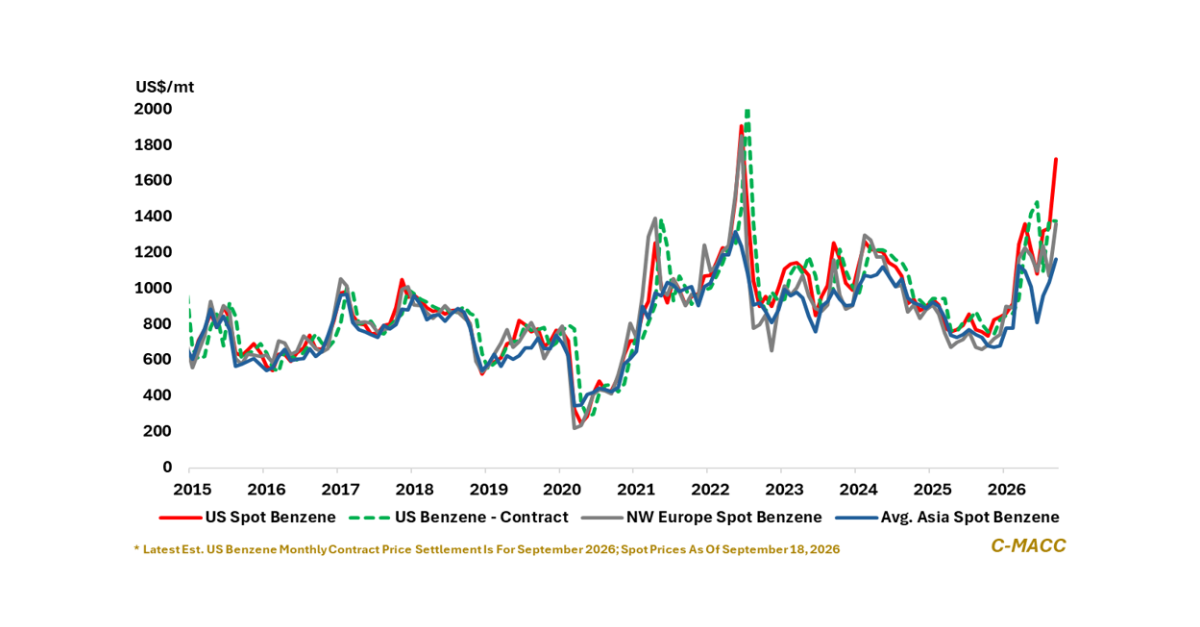
- Other Base Chemicals: US benzene gains squeeze styrene producers, methanol costs rise across regions, and European caustic could strengthen if elevated electricity costs force exposed producers to reduce their operating rates.
- Agriculture: Lower coastal ammonia prices offer growers limited relief as inland US prices hold firm, European natural gas costs favor imports, and expensive sulfur keeps phosphate production costs high.
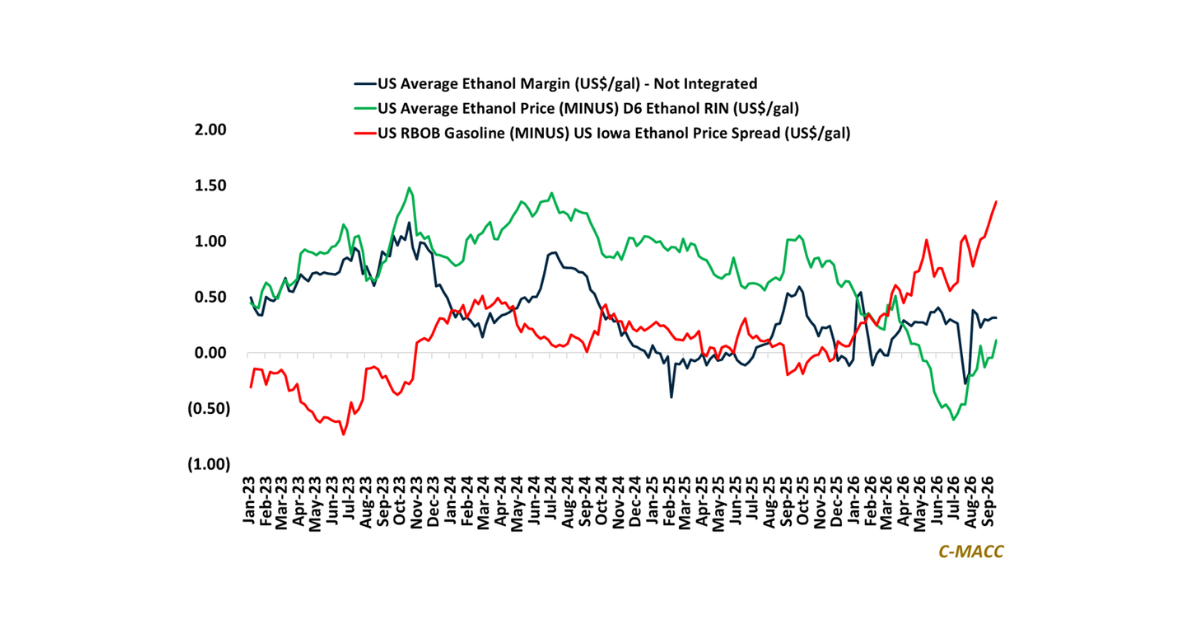
- Refining & Biofuels: Low US diesel stocks support refinery margins despite softer demand; California’s E15 law gives ethanol producers room to grow, provided fuel retailers start selling the higher blend.
Exhibit 1 – Chart of the Day: US Benzene’s Surge Tests Merchant Buyers’ Ability to Pass Through Higher Costs.
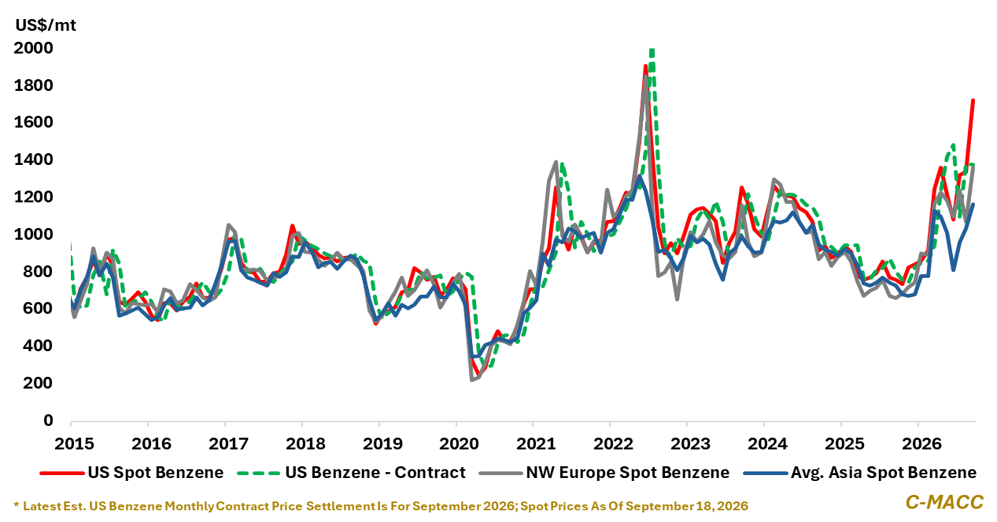
Source: Bloomberg, C-MACC Estimates, September 2026
Client Login
Learn About Our Subscriptions and Request a Trial
Contact us at cmaccinsights@c-macc.com to gain full access and experience our services!