Base Chemical Global Analysis
Global Weekly Catalyst No. 350
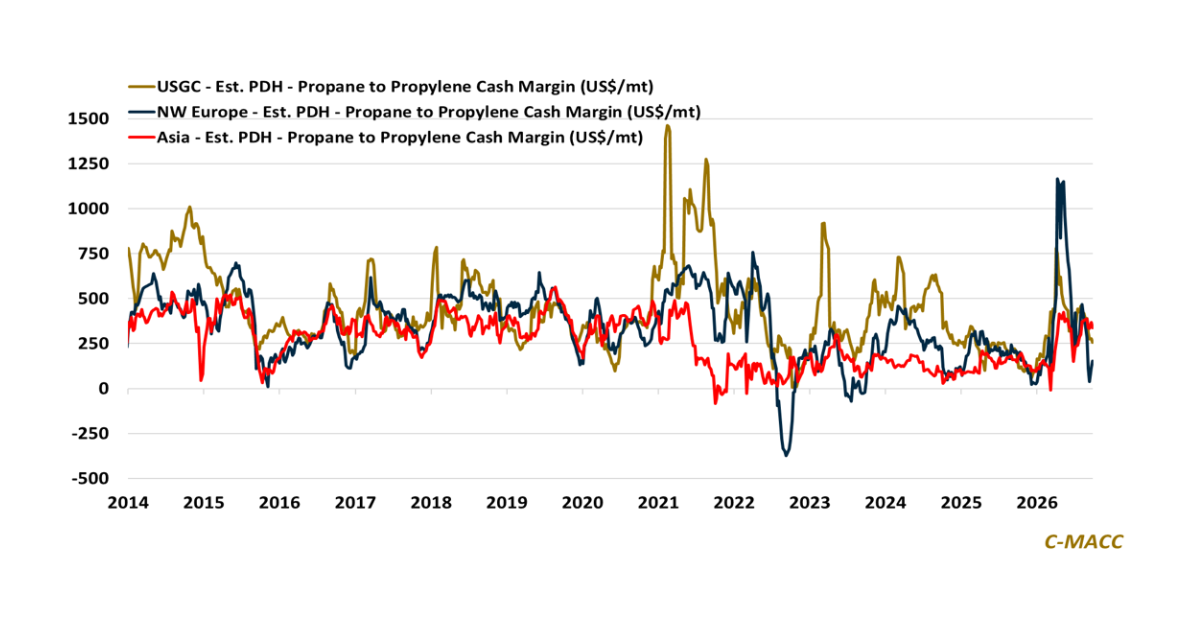
- General Thoughts: Regional advantage changes with the process and the buyer; rising propane and weaker PGP have put modeled US PDH margins below Asia, even as advantaged USGC ethane favors domestic crackers.
- Feedstocks & Energy: Asia’s naphtha premium widened despite flat weekly crude, but freight and cautious buyers limit arbitrage; USGC ethane retains its advantage, with export prices governing any incremental gains.
- Olefins: Asian olefin supply remains constrained, but cautious buyers limit gains; European ethylene and propylene rose as butadiene fell, and USGC spot ethylene and propylene prices moved lower.
- Other Base Chemicals: INEOS idling three UK chemical plants may increase European acetic acid imports and reduce local methanol use; US benzene’s premium is shaped by freight, and electricity shapes European chloralkali returns.
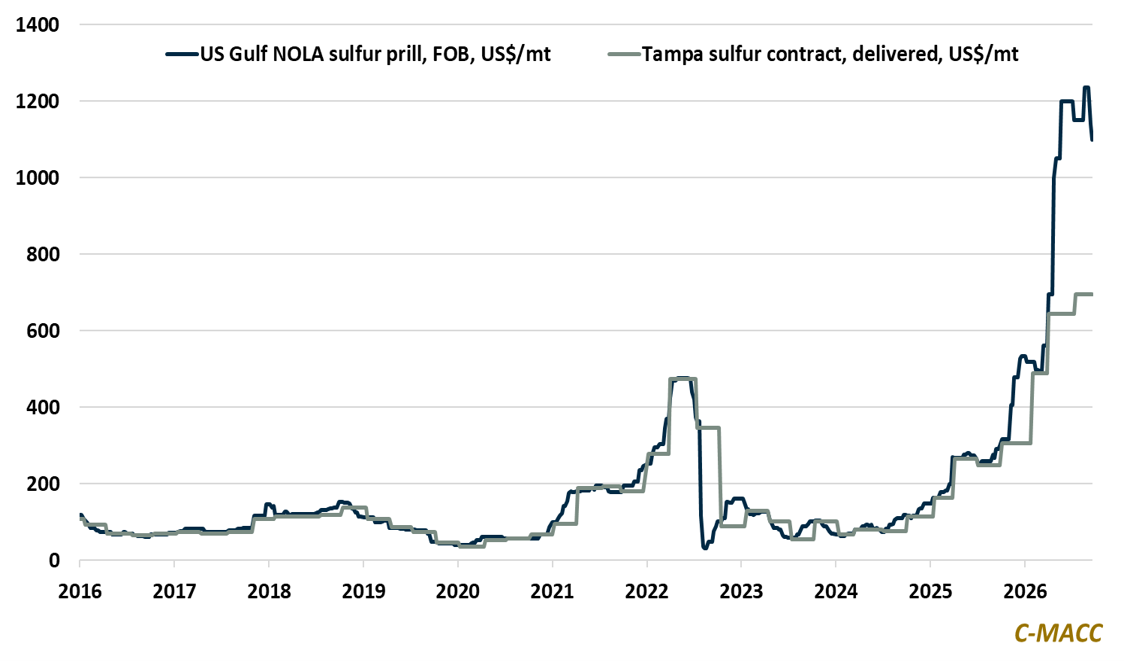
- Agriculture: India’s urea tender may reduce subsidy costs without lowering growers’ prices; European ammonia import growth requires operating fertilizer plants, and sulfur costs squeeze Indian phosphate producers.
- Refining & Biofuels: A US diesel export ban could fill storage, curb refinery runs and reduce gasoline output despite thin stocks; ethanol’s wider modeled margin faces a sales test if output recovers.
Exhibit 1 – Chart of the Day: Estimated US PDH Margins Fall Below Asia as Propane Rises and PGP Weakens
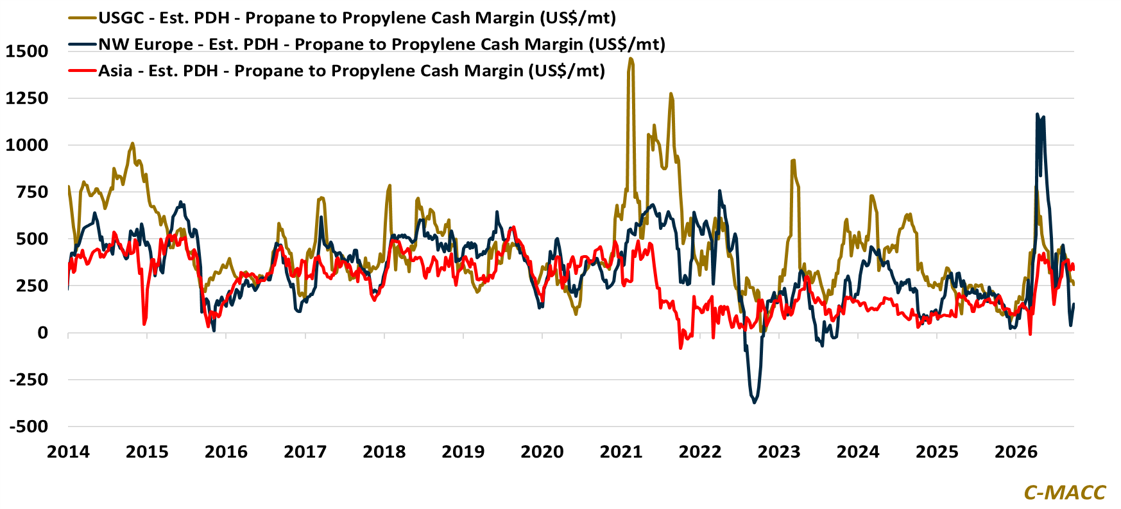
Source: Bloomberg, C-MACC Estimates, September 2026
Client Login
Learn About Our Subscriptions and Request a Trial
Contact us at cmaccinsights@c-macc.com to gain full access and experience our services!