Global Market Analysis
Closing Arguments: Better Chemical Portfolios Can Leave Oversupply Intact
Key Findings
- General Thoughts: Chemical restructuring can lift returns without tightening markets, as productivity gains can partly offset closures and asset sales change ownership without removing competing supply.
- Supply Chain/Commodities: Deferred Northern Hemisphere fertilizer buying raises the risk of a spring delivery squeeze even if consumption weakens, lifting the value of inventory positioned near farms.
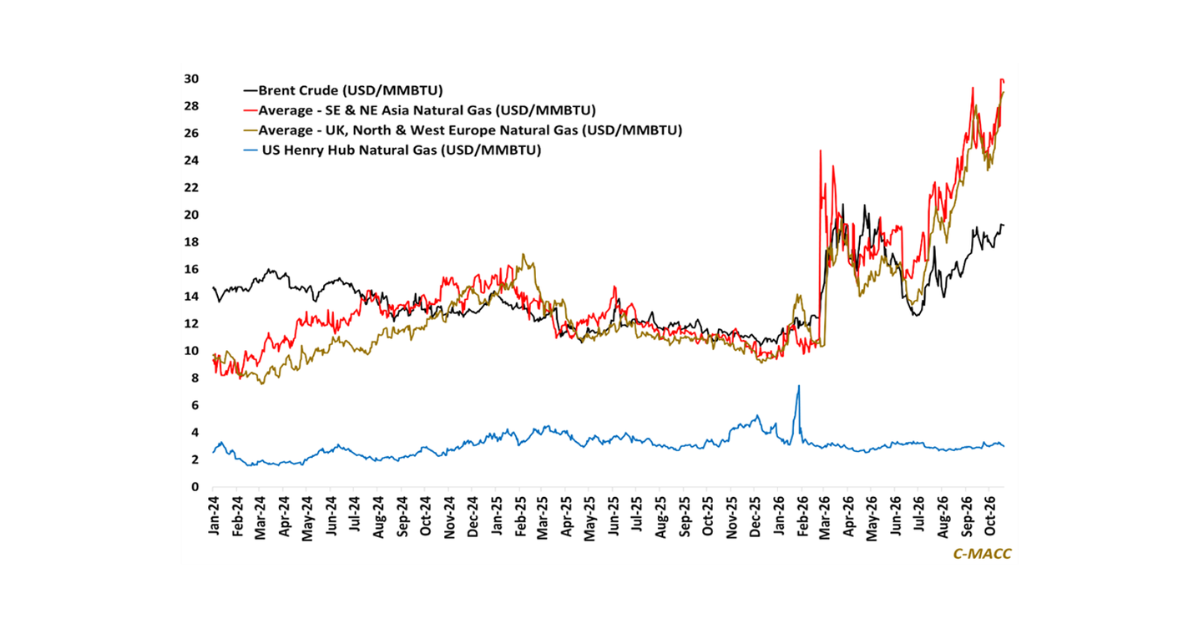
- Energy/Upstream: Higher natural gas costs risk intensifying ongoing restructuring in Europe and exposed Asian industries before announced closures and cost reductions deliver their intended benefits.
- Sustainability/Energy Transition: Grid investment can improve reliability and raise industrial costs; customer commitments and cost allocation determine whether networks support competitive manufacturing.
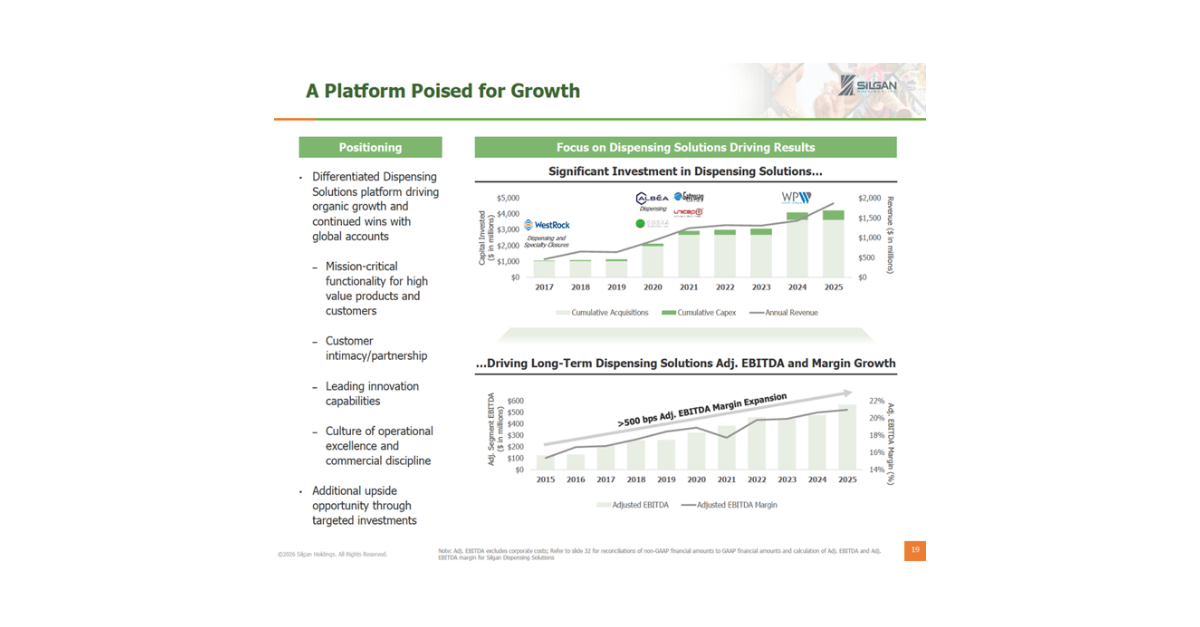
- Downstream/Other Chemicals: AI hardware complexity can lift chemical spending per device, giving suppliers embedded in customer production an advantage that cheap feedstock cannot readily replicate.
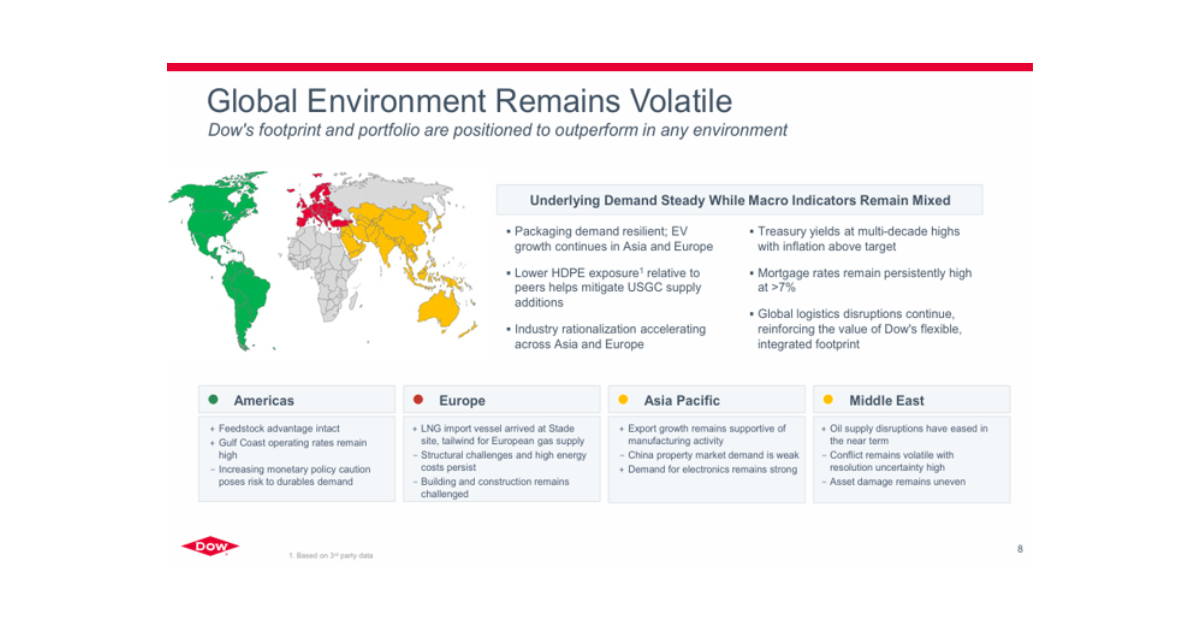
Exhibit 1: Diverging End Markets Favor Targeted Growth Over Betting on Broad Industrial Recovery
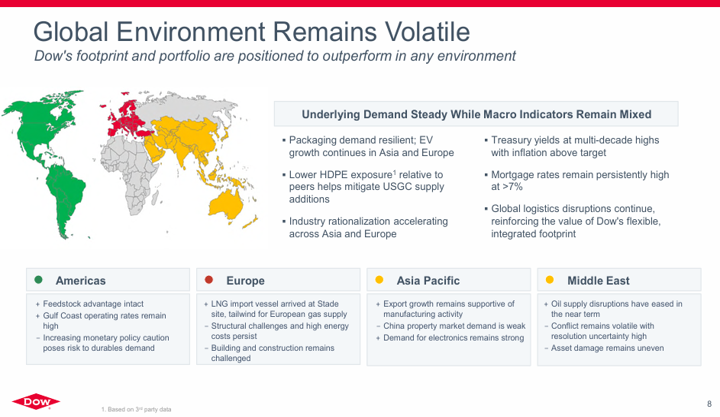
Source: Dow – 3Q26 Earnings Presentation
See the PDF below for all charts, tables, and diagrams
Client Login
Learn About Our Subscriptions and Request a Trial
Contact us at cmaccinsights@c-macc.com to gain full access and experience our services!