Base Chemical Global Analysis
Global Weekly Catalyst No. 354
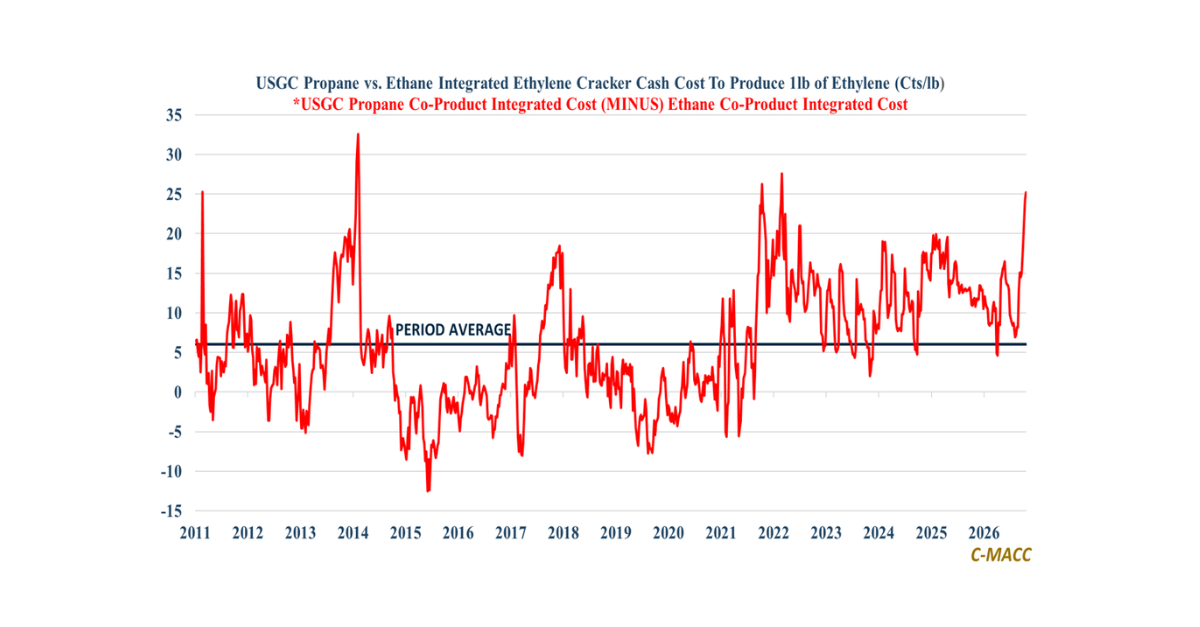
- General Thoughts: USGC ethane’s growing advantage continues to favor lighter cracking, limiting co-product supply and supporting selected chemical prices despite weak downstream demand and an uneven production recovery.
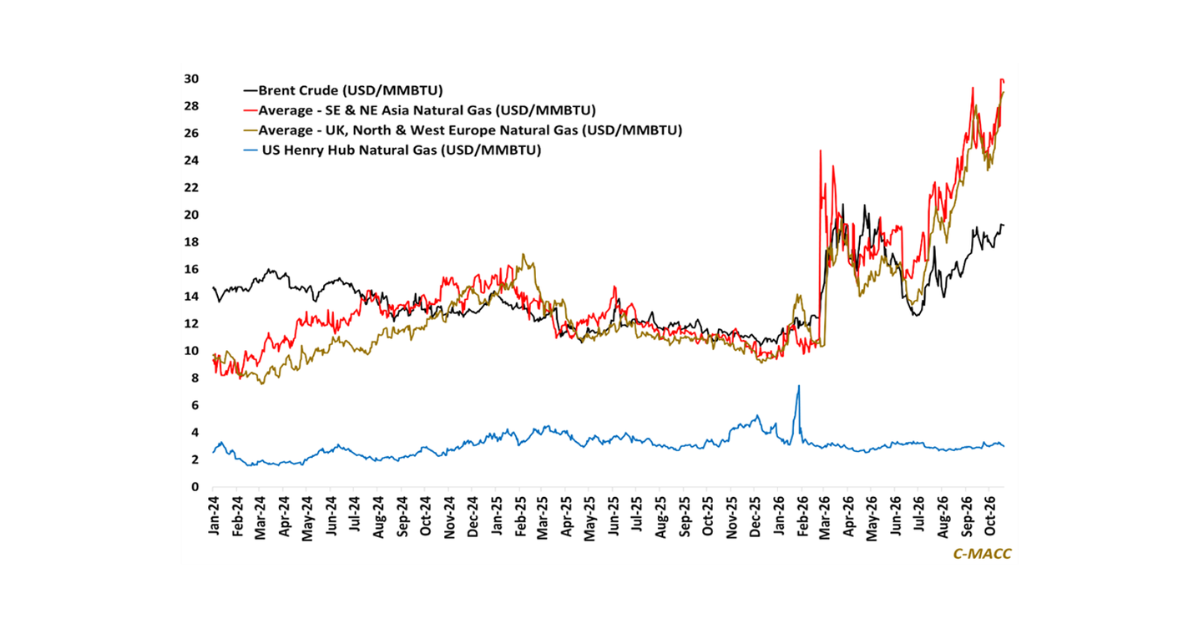
- Feedstocks & Energy: USGC feedstock advantages remain supported as Asian LPG rises above naphtha and Europe’s smaller LPG discounts provide less protection against expensive feedstocks and elevated ex-US natural gas costs.
- Olefins: Global olefin prices remain supported by uneven production and delivery shortages, but cautious derivative buying means tighter spot availability does not establish a broad recovery in underlying demand.
- Other Base Chemicals: Northeast Asian spot methanol rises despite weak MTO demand, benzene’s US premium contracts, and European chlor-alkali producers face rising electricity costs without higher combined selling values.
- Agriculture: European ammonia cuts support import demand, but sulfur shortages curb phosphate producers’ ammonia purchases, limiting ammonia suppliers’ price gains from global supply disruptions.
- Refining & Biofuels: US crude oil refining benchmarks fall further from 2026 highs, but cheaper corn lifts ethanol margins to a 2026 high despite lower ethanol prices and higher Midwest inventories.
Exhibit 1 – Chart of the Day: USGC Ethane’s Widening Advantage Could Tighten Cracker Co-product Supply
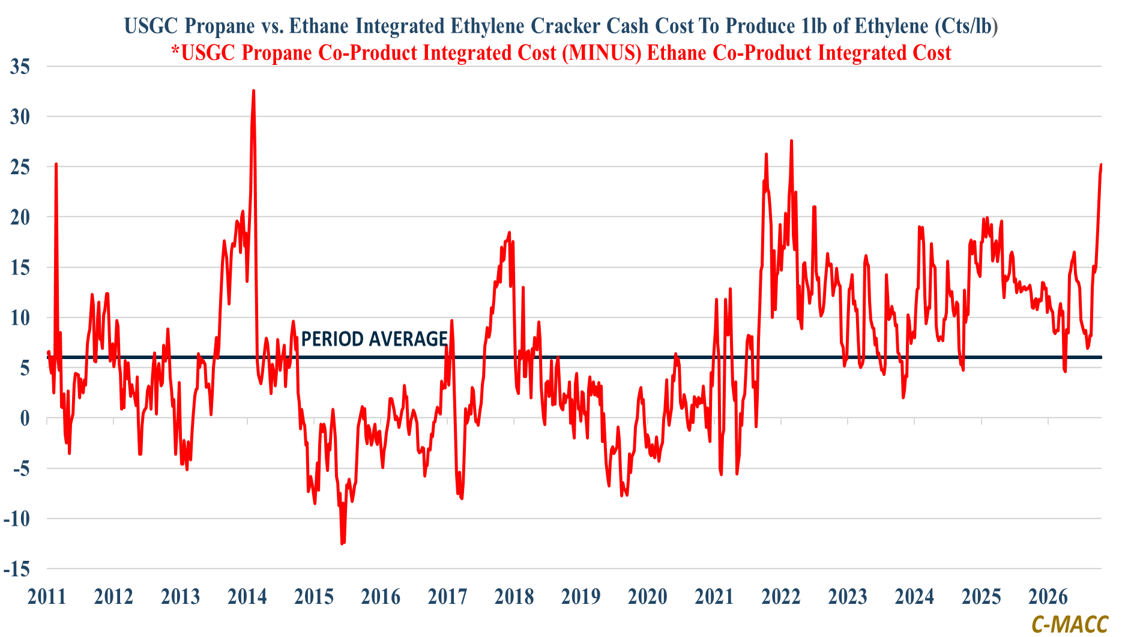
Source: Bloomberg, C-MACC Estimates, October 2026
Client Login
Learn About Our Subscriptions and Request a Trial
Contact us at cmaccinsights@c-macc.com to gain full access and experience our services!