Base Chemical Global Analysis
Global Weekly Catalyst No. 355
- General Thoughts: Higher output need not bring equal price relief, as coproduct values shape cracker economics and industrial nitrogen sales can absorb ammonia otherwise available for fertilizer production.
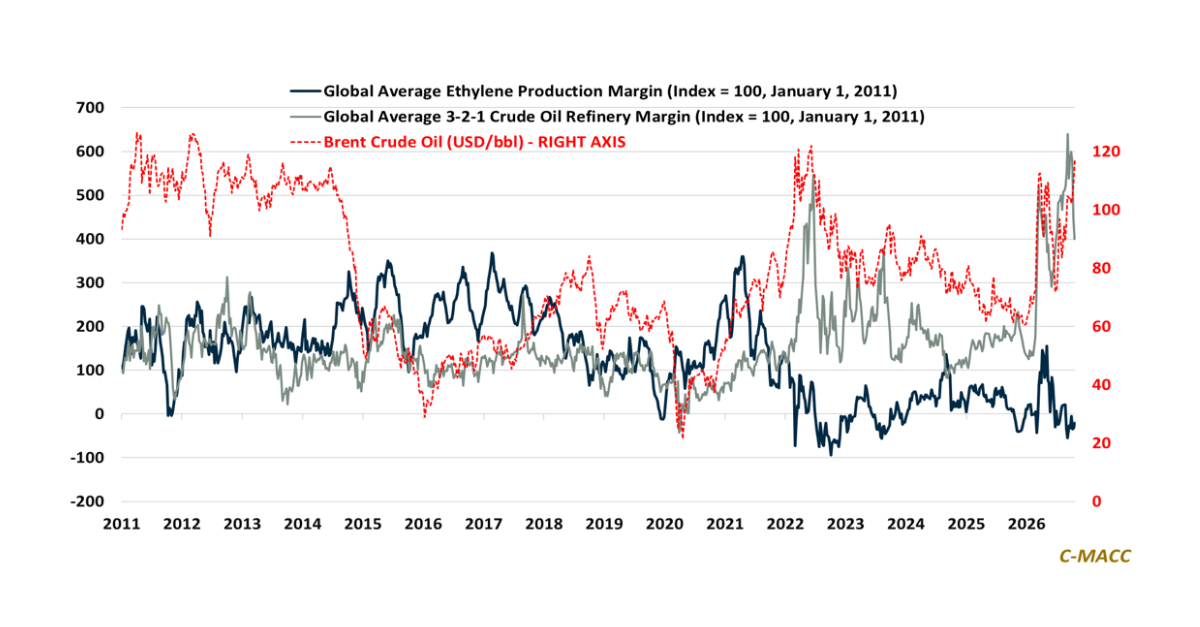
- Feedstocks & Energy: Asian LPG’s surge encourages naphtha substitution without requiring chemical demand growth, limiting savings from crude’s retreat and preserving the USGC cost advantage despite improved arrivals.
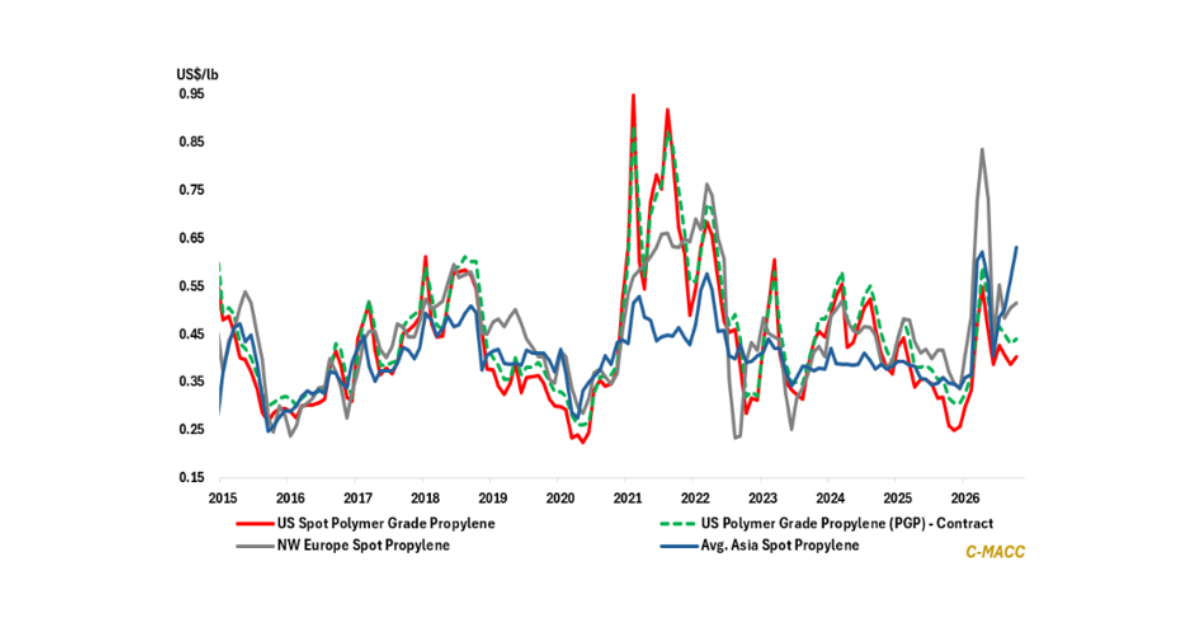
- Olefins: Asia’s propylene and butadiene prices support cracker economics, but weaker co-product revenues in Europe undermine ethylene cost recovery, limiting the response buyers can expect from European producers.
- Other Base Chemicals: Returning methanol supply could revive MTO buying, benzene’s shrinking US premium discourages new Asian shipments, and European production cuts could improve prospects for USGC caustic exporters.
- Agriculture: US ammonia output gains need not expand fertilizer supply proportionately as LSB favors industrial products and European producers increase import reliance in response to higher-cost local production.
- Refining & Biofuels: Renewed Russian refinery attacks could delay global diesel relief, and rising Midwest inventories threaten US ethanol margins despite lower corn costs and a recovery in domestic blending demand.
Exhibit 1 – Chart of the Day: Stronger propylene credits cushion Asian ethylene crackers’ naphtha cost disadvantage
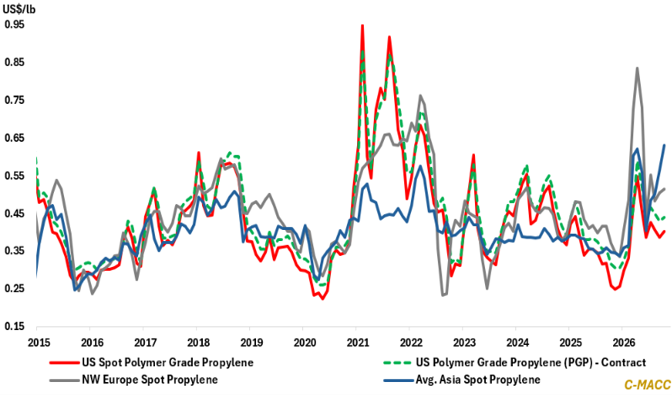
Source: Bloomberg, C-MACC Estimates, November 2026
Client Login
Learn About Our Subscriptions and Request a Trial
Contact us at cmaccinsights@c-macc.com to gain full access and experience our services!