Base Chemical Global Analysis
Global Weekly Catalyst No. 348
- General Thoughts: The current global energy shock is widening operating freedom across the value chain, allowing advantaged producers to stay active while weaker assets face earlier production cuts and rising import dependence.
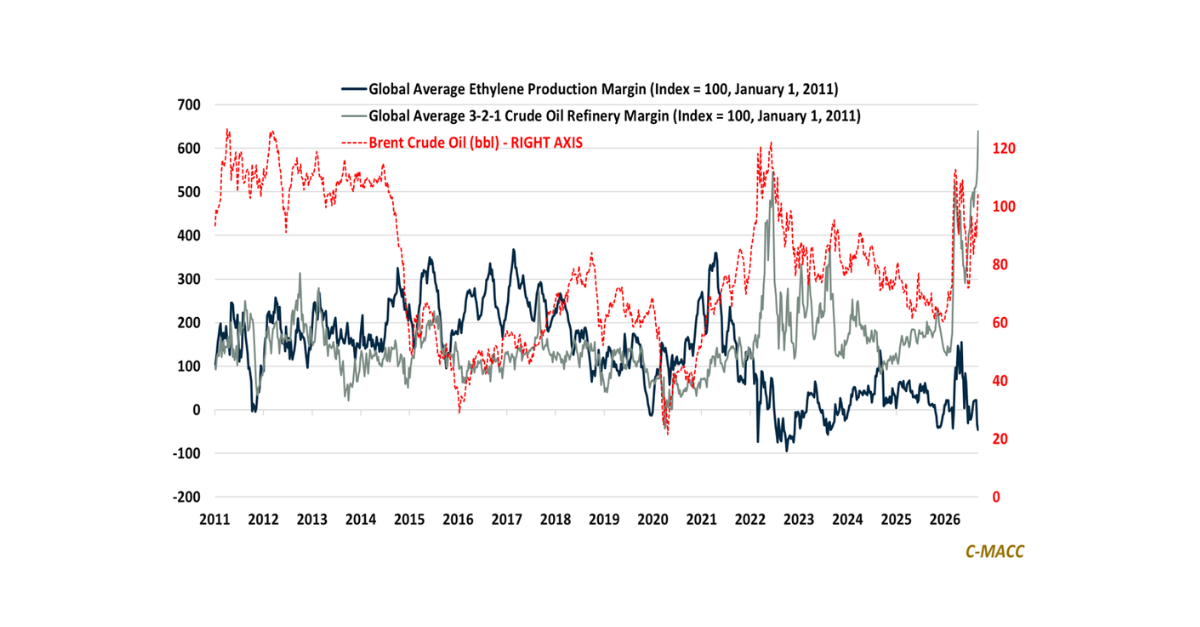
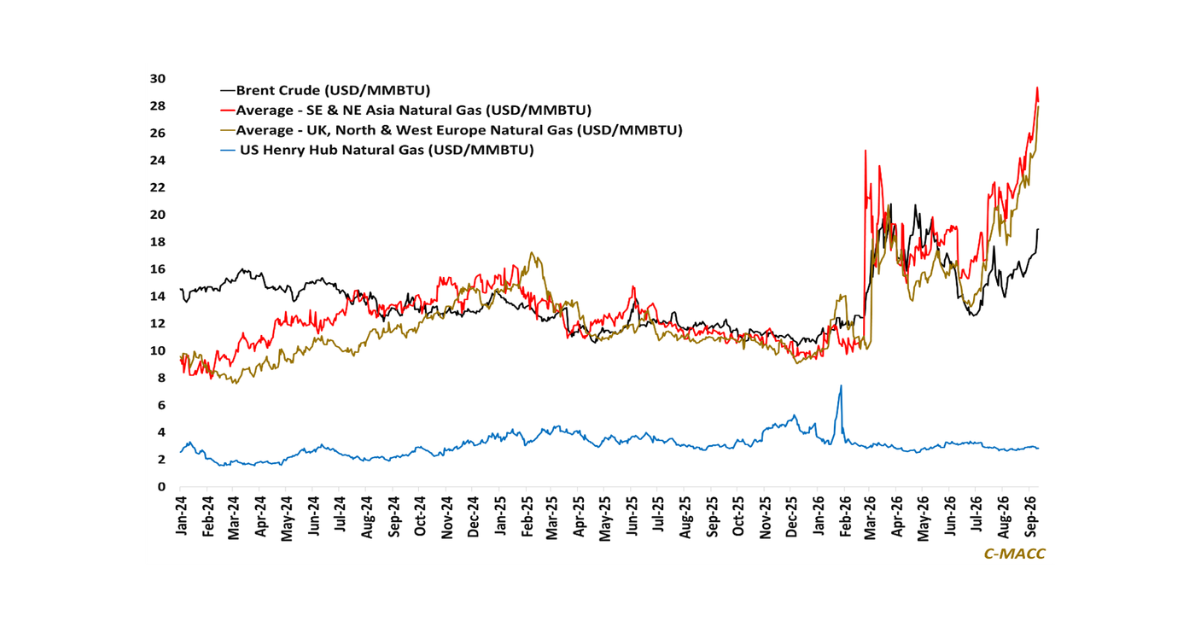
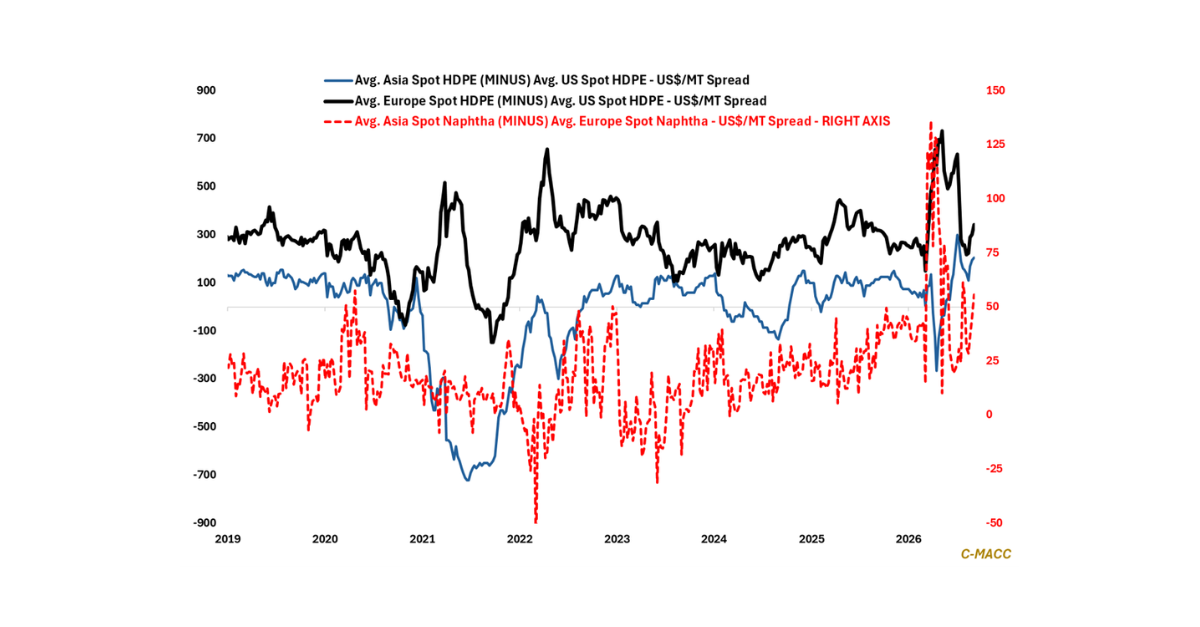
- Feedstocks & Energy: Crude inflation is deepening Asia’s naphtha disadvantage, while low-cost US natural gas and ethane provide operating room whose value rises when competitors must cut production first.
- Olefins: Ethylene remains supported by constrained cracker supply; rising Chinese PDH utilization should temper propylene gains; and ample butadiene inventories limit upside despite lower cracker co-product production.
- Other Base Chemicals: Asian benzene and methanol prices reflect constrained availability, while European energy costs shorten the operating runway for weaker plants and leave US chlor-alkali producers with greater flexibility.
- Agriculture: Nitrogen economics increasingly reward producers that can manufacture and deliver consistently, leaving US plants better positioned as European ammonia costs move closer to import-driven operating decisions.
- Refining & Biofuels: Limited spare refining capacity is converting distillate scarcity into earnings, while ethanol’s faster production response makes its current margin advantage materially less durable than refinery strength.
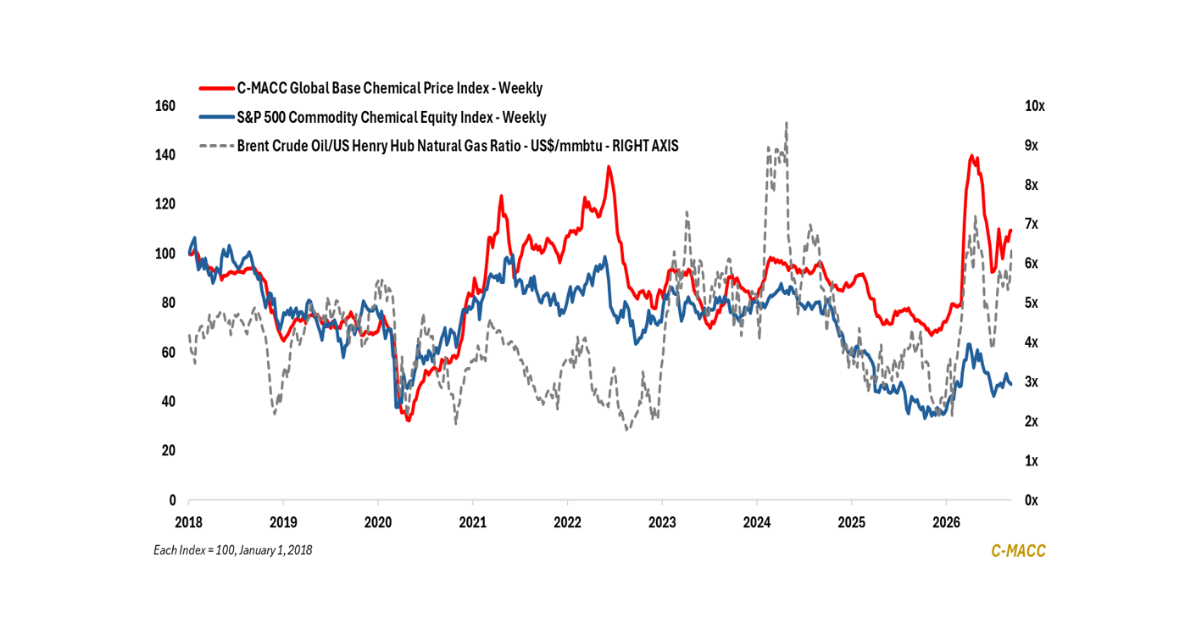
Exhibit 1 – Chart of the Day: Commodity Prices Rise While US Chemical Equities Discount Their Durability.
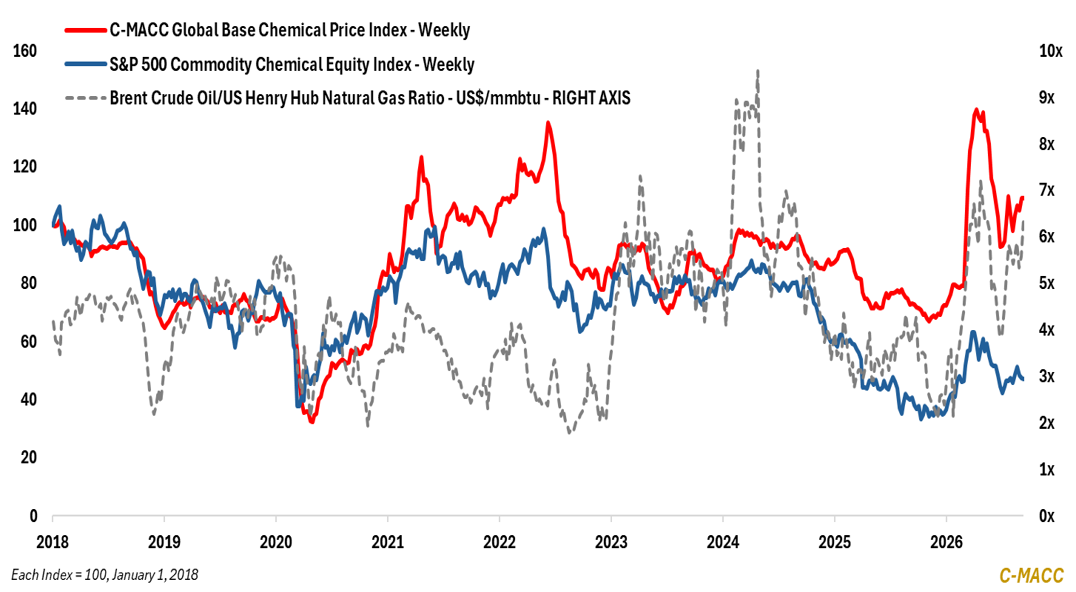
Source: Bloomberg, C-MACC Estimates, September 2026
Client Login
Learn About Our Subscriptions and Request a Trial
Contact us at cmaccinsights@c-macc.com to gain full access and experience our services!