Global Market Analysis
Freight Expectations: The Fuel Windfall Does Not Belong to Every Refiner
Key Findings
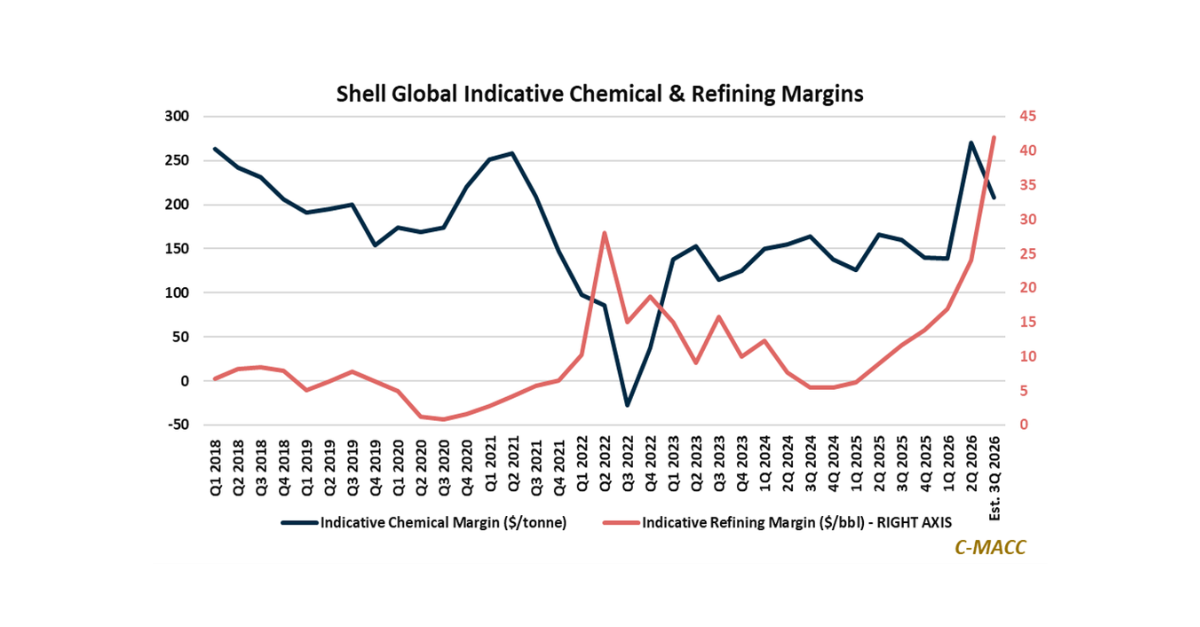
- General Thoughts: Record refining margins conceal uneven returns as freight raises replacement crude costs, favoring refiners near available supply and leaving distant buyers bidding away part of the fuel premium.
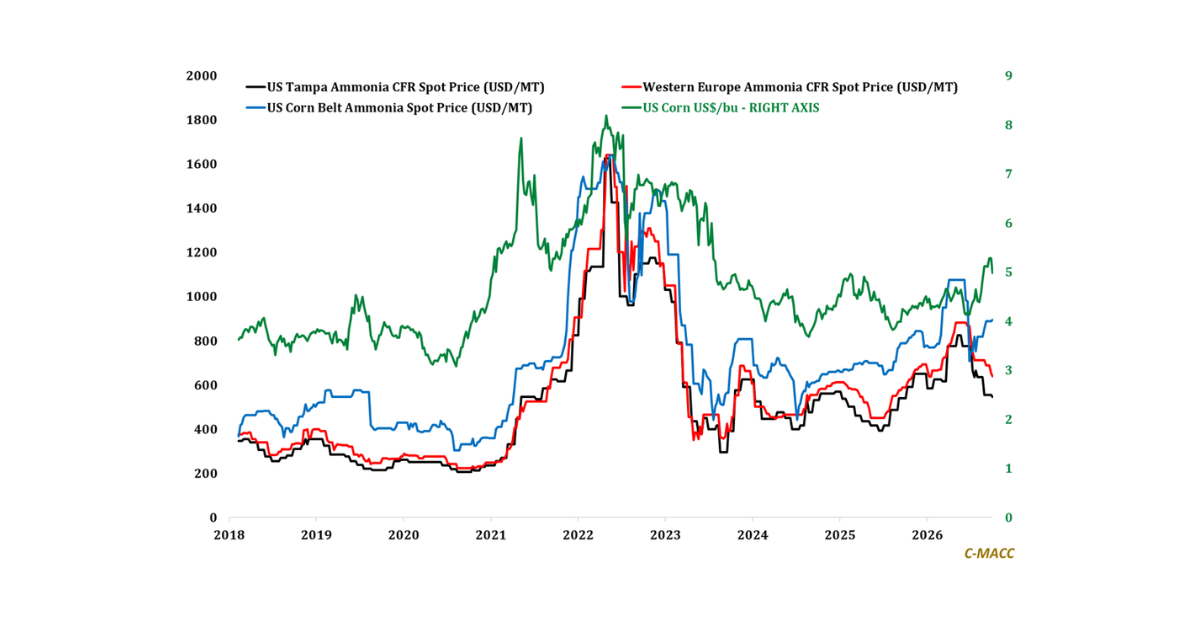
- Supply Chain/Commodities: Cheap US natural gas supports ammonia export competitiveness, but weak European offtake can limit replacement needs, making import share a poor proxy for demand growth.
- Energy/Upstream: Midstream acquisitions secure supply for domestic and export networks, creating integration value when acquired volumes improve returns across existing downstream infrastructure.
- Sustainability/Energy Transition: AGCO’s retrofits can lower the investment needed for farm efficiency, allowing verified sustainability benefits to accompany commercially attractive adoption.
- Downstream/Other Chemicals: Biofuel demand can strengthen local soybean bids despite soft weekly export bookings, but processor gains depend on meal economics as well as sustained oil demand.
Exhibit 1: Shell’s Refining Margin Indicator Surges As Chemicals Weaken, But Freight Tests Realized Returns.
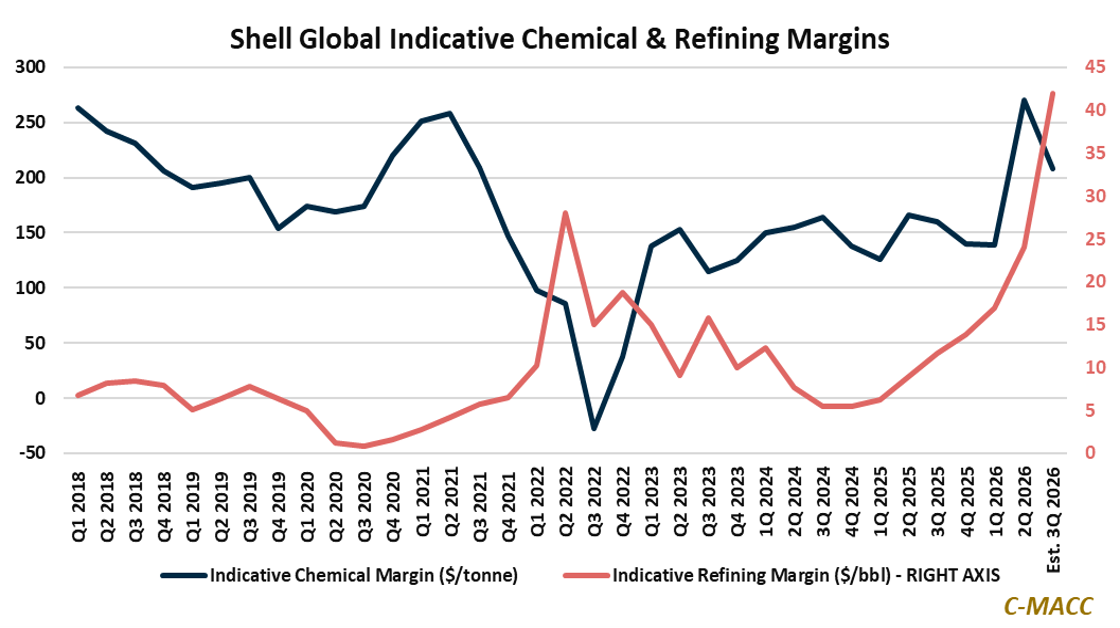
Source: Shell – 3Q26 Business Update, October 2026
See the PDF below for all charts, tables, and diagrams
Client Login
Learn About Our Subscriptions and Request a Trial
Contact us at cmaccinsights@c-macc.com to gain full access and experience our services!