Polymer Global Analysis
Resin To Riches: Weekly Plastic Market Insights
- General Thoughts: Polymer supply disruptions can open customer accounts to competing suppliers, potentially extending price pressure beyond delivery constraints and limiting broad pricing gains expected from plant closures.
- Polyethylene (PE): PE’s grade mismatch favors selective LDPE premiums, as planned US HDPE additions may compete for export customers without addressing delivery gaps that support prices for other PE grades.
- Polypropylene (PP): Weak PP demand can squeeze spreads even as propylene eases, leaving sustained inventory cuts more important than individual supplier outages for sustaining US industry pricing power through year-end.
- Polyvinyl Chloride (PVC): Europe’s PVC investigation targets supply from countries that gained share after earlier duties, making buyer substitution the key test of whether broader trade action strengthens domestic pricing power.
- Other Sector Developments: Ethane exports can strengthen overseas crackers without matching naphtha’s co-product output, making access to propylene and butadiene a separate risk from the price advantage available on ethylene.
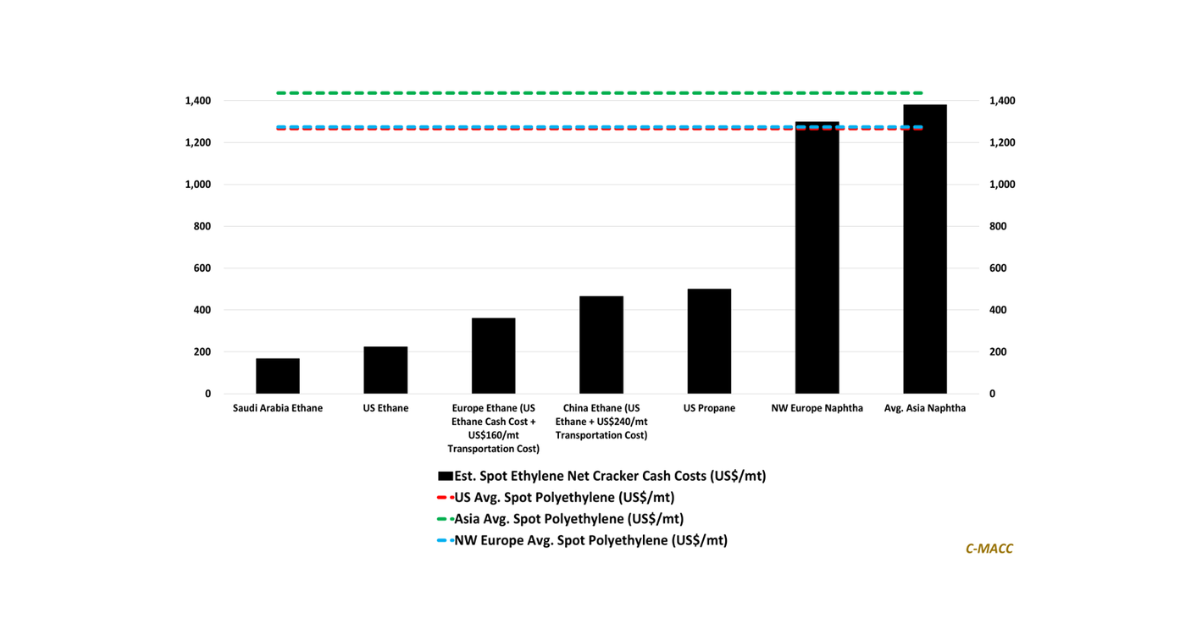
Exhibit 1 – Chart of the Day: Cracker Cost Gaps Explain Supplier Staying Power Better Than Polymer Pricing Potential.
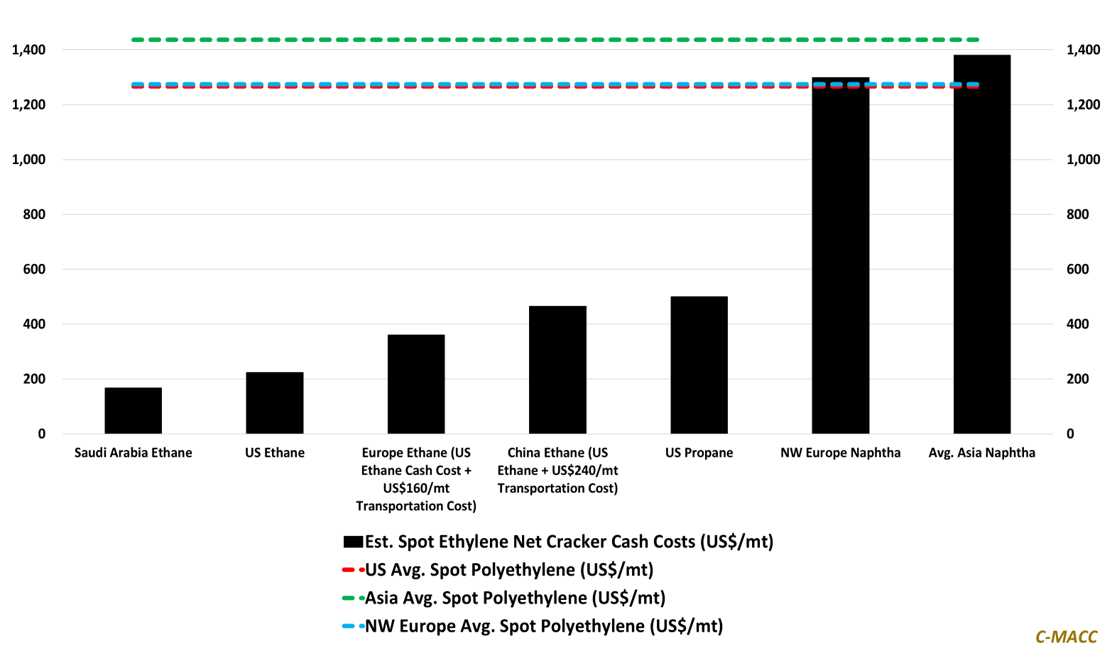
Source: C-MACC Analysis, Bloomberg, September 2026
Client Login
Learn About Our Subscriptions and Request a Trial
Contact us at cmaccinsights@c-macc.com to gain full access and experience our services!