Polymer Global Analysis
Resin To Riches: Weekly Plastic Market Insights
- General Thoughts: Analysts cutting 2026 estimates risk understating 2027 US PE and PVC earnings if supply assumptions overlook delayed capacity additions and prolonged Middle East disruption while US feedstock advantages persist.
- Polyethylene (PE): Asian converters struggle to pass higher PE costs to customers as Asian LDPE holds firm, while softer US spot prices challenge October increase nominations by giving buyers cheaper purchasing alternatives.
- Polypropylene (PP): US PP prices rose as PGP eased, improving quoted production economics, while Saudi offers widened the random copolymer premium only slightly despite substantial increases across both grades.
- Polyvinyl Chloride (PVC): China’s spot PVC jump contrasts with softer Asian pricing and less headroom for US shipments to Asia, while possible European duties could protect producers but weaken their converter customers’ competitiveness.
- Other Sector Developments: Overseas cracker closures can create openings for US suppliers, but asset sales can sustain competition, and downstream shutdowns threaten the scale and duration of import demand.
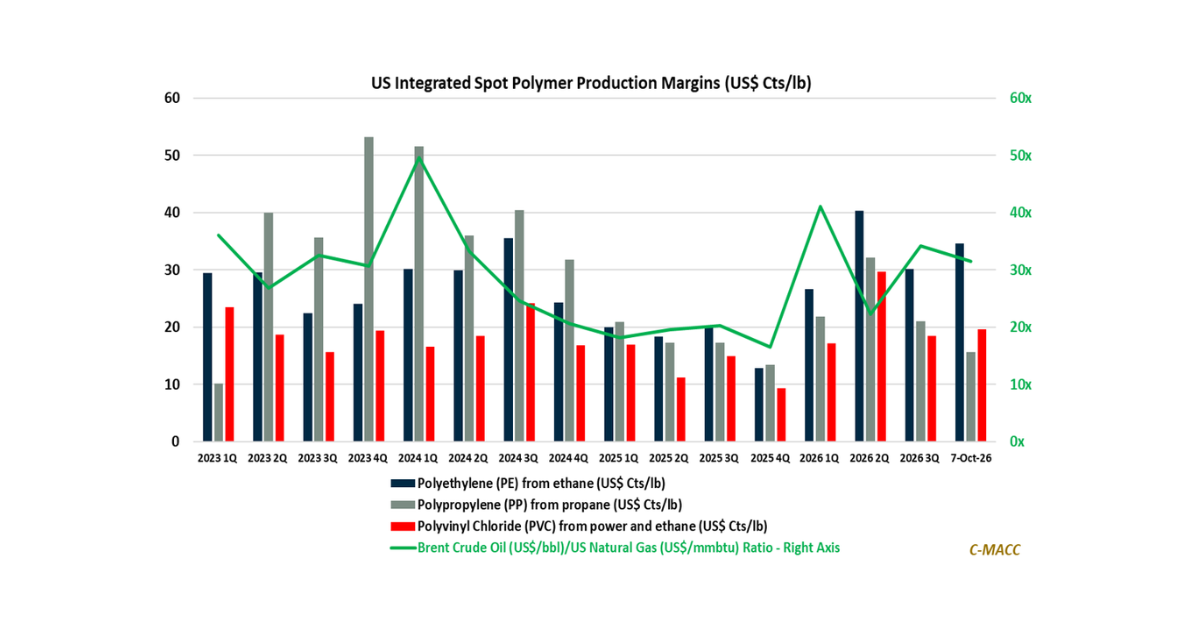
Exhibit 1 – Chart of the Day: US PE and PVC Margins Hold Above 2H25 Averages While PP Stagnates.
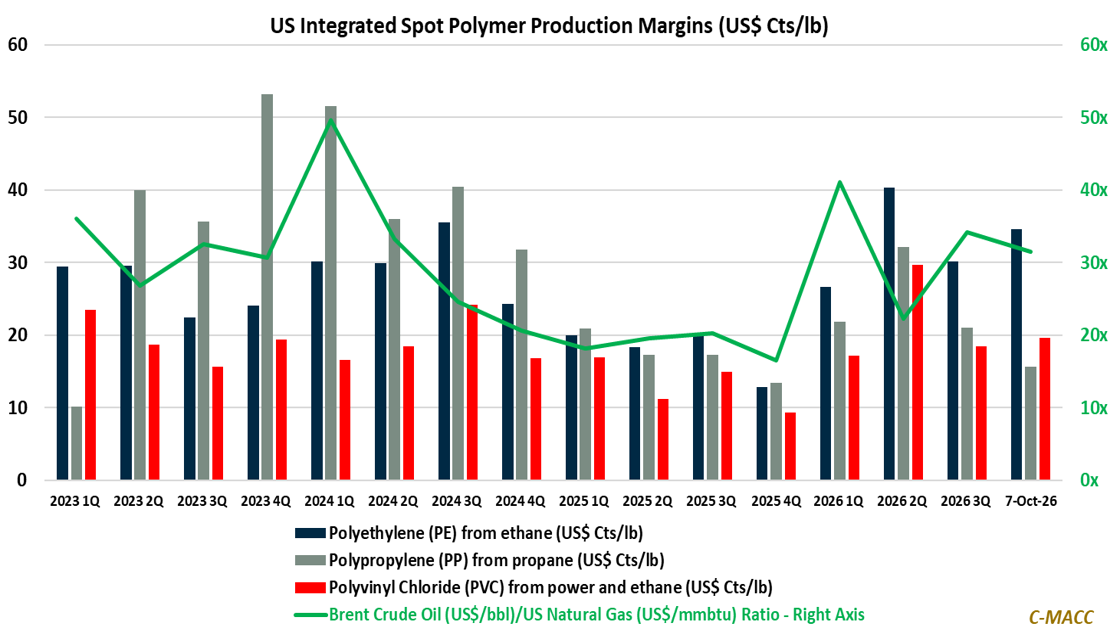
Source: C-MACC Analysis, Bloomberg, October 2026
Client Login
Learn About Our Subscriptions and Request a Trial
Contact us at cmaccinsights@c-macc.com to gain full access and experience our services!