Polymer Global Analysis
Resin To Riches: Weekly Plastic Market Insights
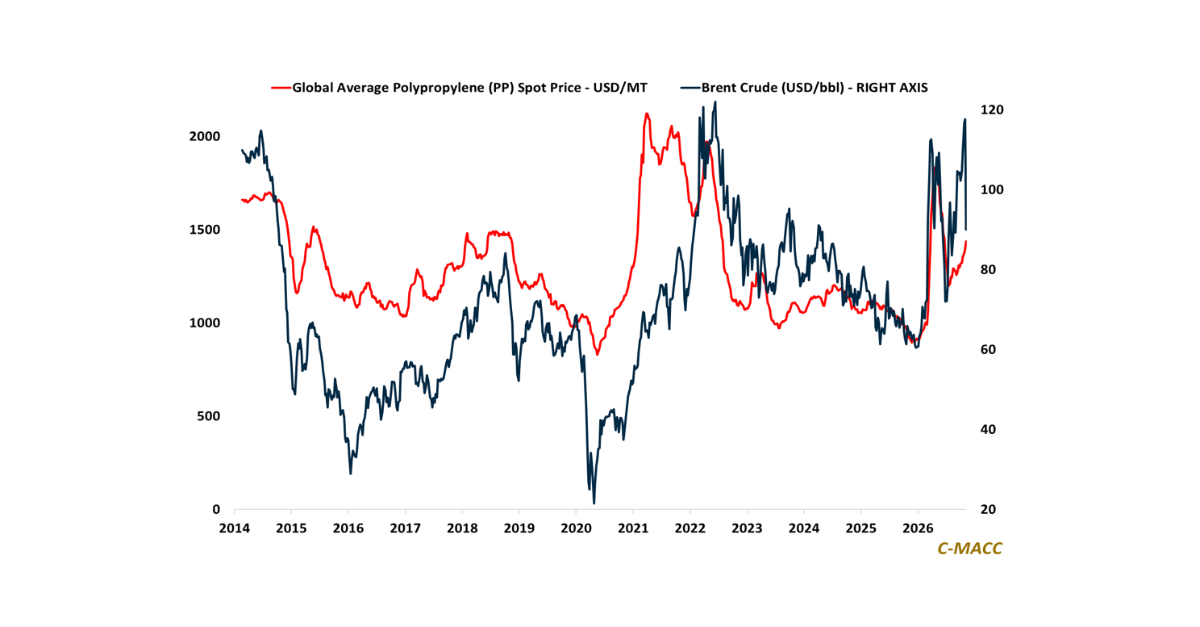
- General Thoughts: Brent crude oil’s decline should pressure polymer prices more than volumes where lean inventories limit December destocking, leaving buyers seeking cheaper offers without necessarily cutting manufacturing output.
- Polyethylene (PE): US PE sellers should find October’s gains harder to extend as Chinese discounts weaken Asian import demand and narrower price gaps limit export support for further domestic price increases.
- Polypropylene (PP): China’s PP discounts should spread across Asian markets and challenge European increases, as US producers face narrower conversion spreads and buyers weigh cheaper forward cargoes against prompt supply needs.
- Polyvinyl Chloride (PVC): Weak Indian buying should pressure Asian PVC offers, while European outages favor dependable local suppliers where duties and delivery times limit timely, competitively priced imports.
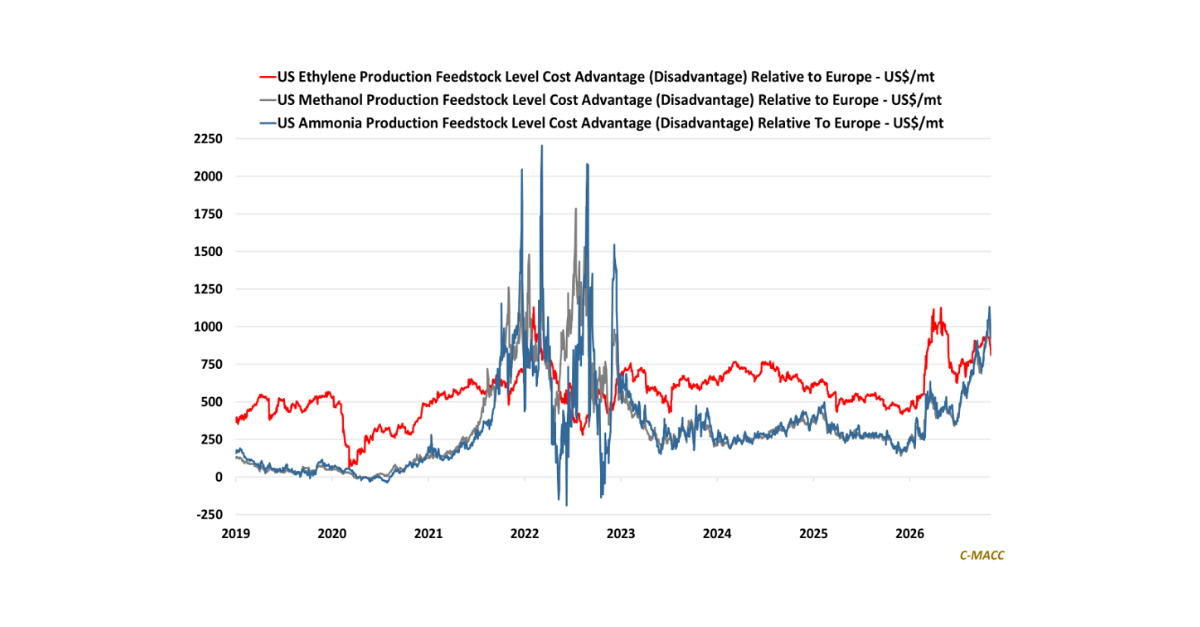
- Other Sector Developments: Cheaper overseas feedstocks should lift margins where selling prices hold, but subsequent price competition can narrow North America’s export advantage if US cost savings lag.
Exhibit 1 – Chart of the Day: Brent’s Decline Tests Whether Lean Inventories Can Sustain 2H26 Polymer Gains
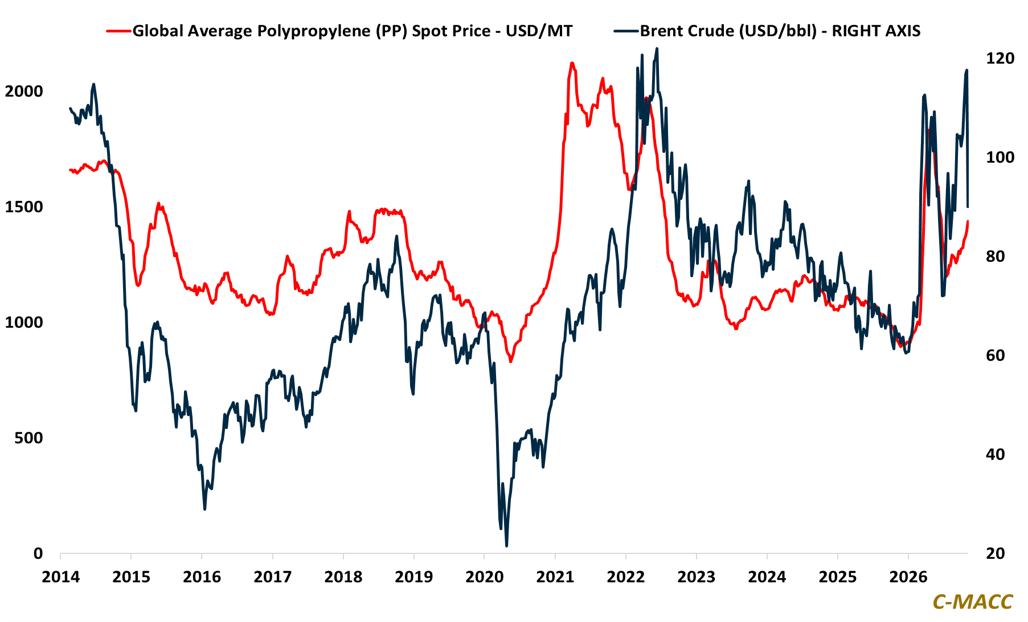
Source: Bloomberg, C-MACC Analysis, November 2026
Client Login
Learn About Our Subscriptions and Request a Trial
Contact us at cmaccinsights@c-macc.com to gain full access and experience our services!