Base Chemical Global Analysis
Global Weekly Catalyst No. 357
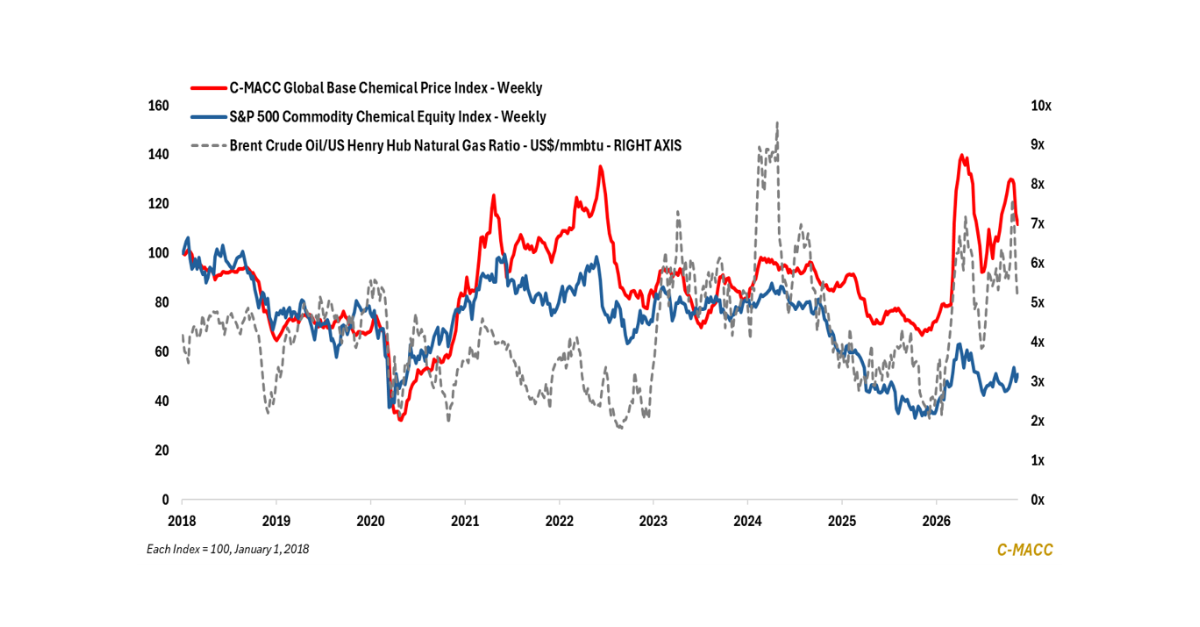
- General Thoughts: US commodity chemical equity valuations question earnings durability and growth, but cost advantages and constrained overseas restarts argue against resetting 2027 profitability to late 2025 levels.
- Feedstocks & Energy: USGC ethane export growth risks shifting value toward suppliers and transporters, exposing overseas crackers when resin prices respond faster to cheaper naphtha than their delivered ethane costs adjust.
- Olefins: Global olefin restructuring can preserve production as integrated expansions shift competition downstream, limiting pricing benefits from closures unless demand absorbs restored output and polymer supply.
- Other Base Chemicals: Global chemical supply constraints support selected markets but do not restore broad pricing power, as downstream losses curb consumption and price gaps reshape trade incentives rather than revive demand.
- Agriculture: Global fertilizer tightness does not assure earnings growth as ammonia strengthens, freight costs absorb part of producers’ price gains, and tight farm credit continues to restrain fertilizer purchases.
- Refining & Biofuels: Refinery margins can retreat before global diesel shortages clear as supply recovers, but positive ethanol cash margins can prolong inventory pressure by sustaining output despite softer fuel demand.
Exhibit 1 – Chart of the Day: US Cost Advantages and Overseas Constraints Challenge a Late 2025 Profitability Reset
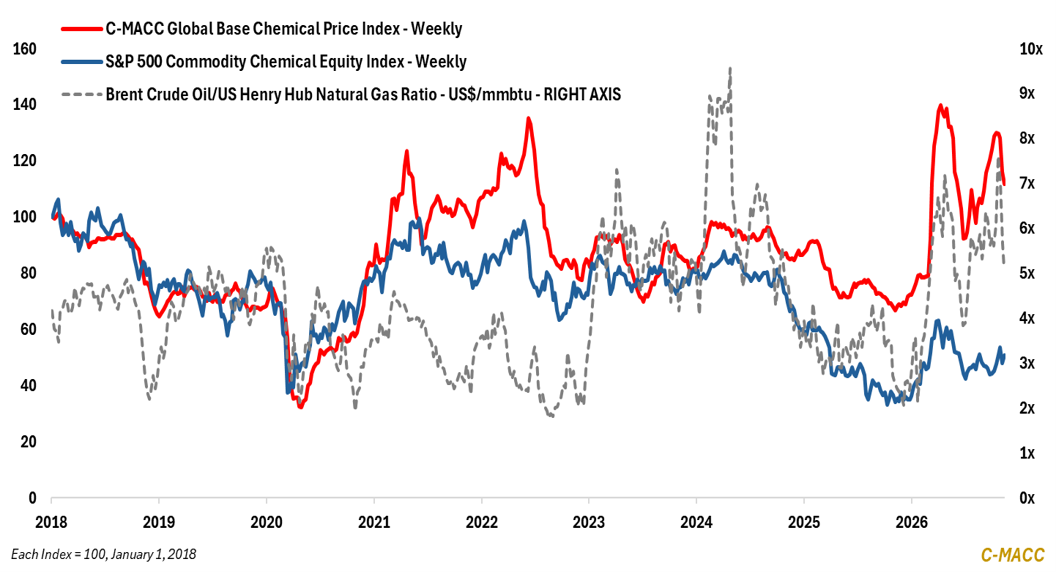
Source: Bloomberg, C-MACC Estimates, November 2026
Client Login
Learn About Our Subscriptions and Request a Trial
Contact us at cmaccinsights@c-macc.com to gain full access and experience our services!