Polymer Global Analysis
Resin To Riches: Weekly Plastic Market Insights
- General Thoughts: Data center infrastructure supports pipe demand despite weak housing, favoring qualified polymer suppliers and downstream integrated producers whose customer access helps secure funded project orders.
- Polyethylene (PE): PE’s wider HDPE export gaps largely reflect US discounts, while cautious buying and expected supply additions challenge broad price increases despite lower US inventories in October.
- Polypropylene (PP): European PP sellers are holding gains because imports stay costly and distant, but narrowing copolymer premiums and softer Asian offers weaken the case for broad increases as supply expands.
- Polyvinyl Chloride (PVC): Stable PVC prices conceal tighter conversion economics, while selective Asian concessions and Latin American import competition test whether producers can defend earnings without sacrificing volume.
- Other Sector Developments: North America’s feedstock advantage continues to support exports, but narrowing price gaps and overseas intermediate purchases complicate who captures the benefit of cheaper US inputs.
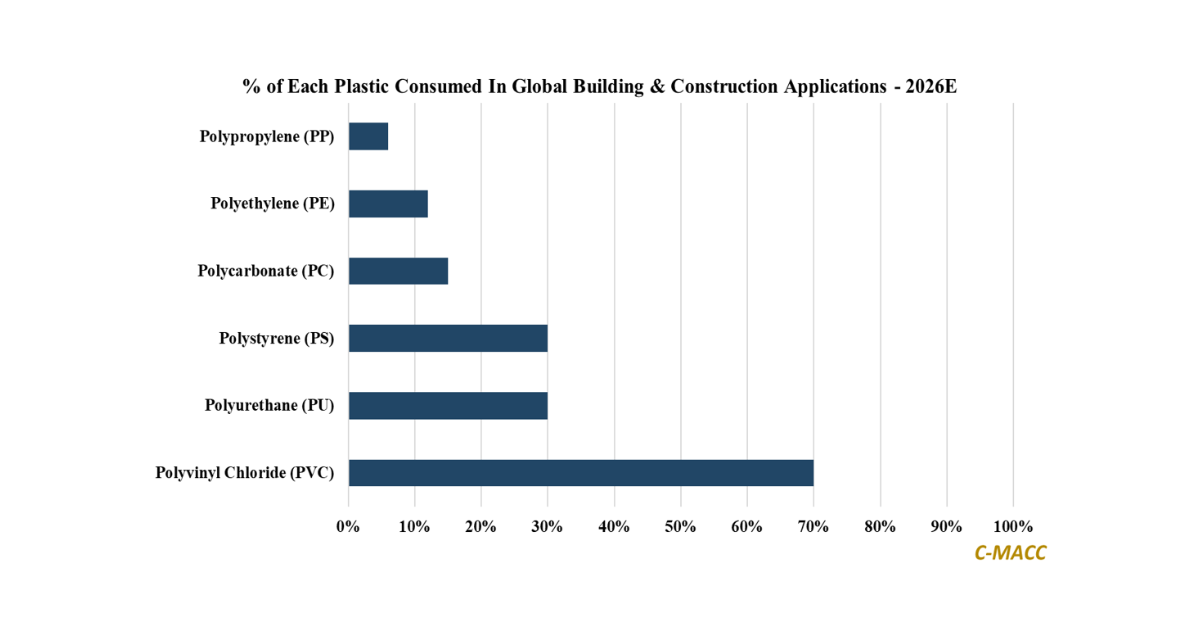
Exhibit 1 – Chart of the Day: Construction Dominates PVC Demand While PE Totals Mask HDPE Pipe Opportunities
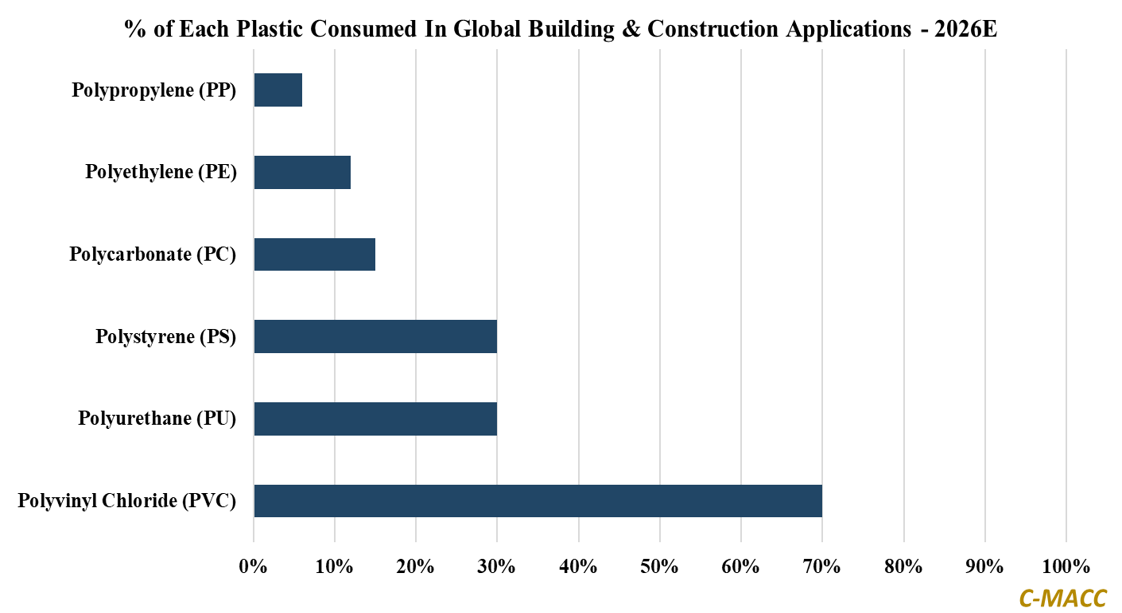
Source: C-MACC estimates, 2026E. Shares of each polymer’s global consumption by weight used in residential, commercial, infrastructure, and renovation applications. PE includes HDPE, LDPE, and LLDPE. PS includes EPS and the polystyrene used in XPS. PU includes polyisocyanurate (PIR) insulation. Figures are rounded; application classifications vary across sources.
Client Login
Learn About Our Subscriptions and Request a Trial
Contact us at cmaccinsights@c-macc.com to gain full access and experience our services!