Polymer Global Analysis
Resin To Riches: Weekly Plastic Market Insights
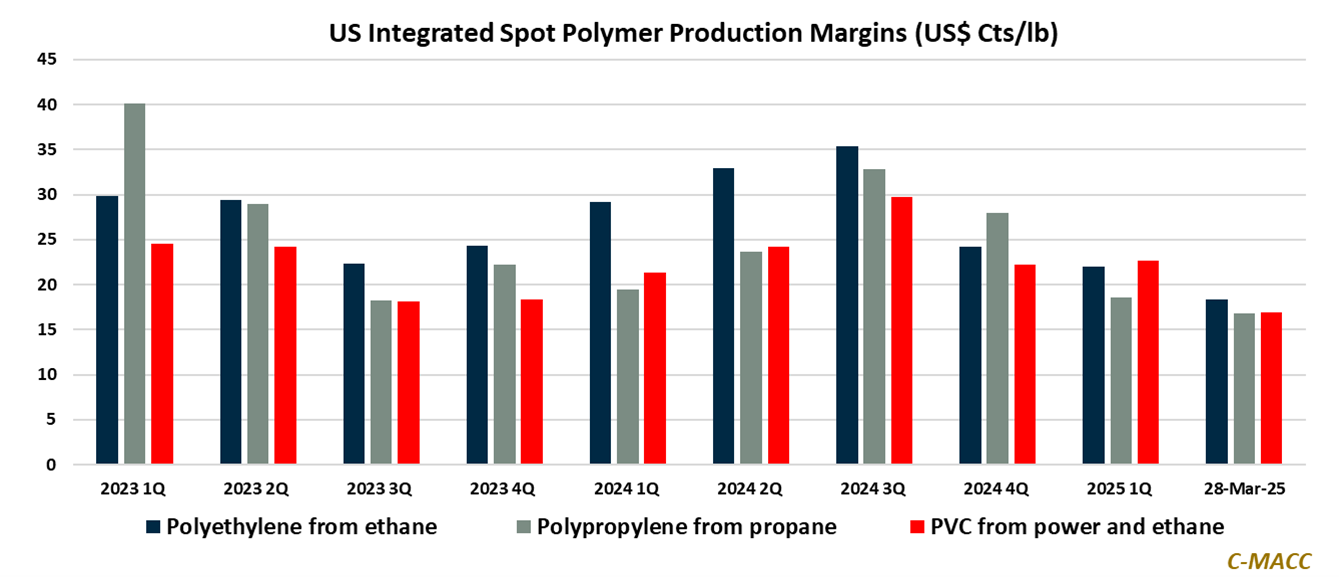
- General Thoughts: We estimate US integrated polymer margins broadly ended March below their 1Q25 average levels, and our production, feedstock, and demand outlook implies the rest of 2025 will remain challenging YoY.
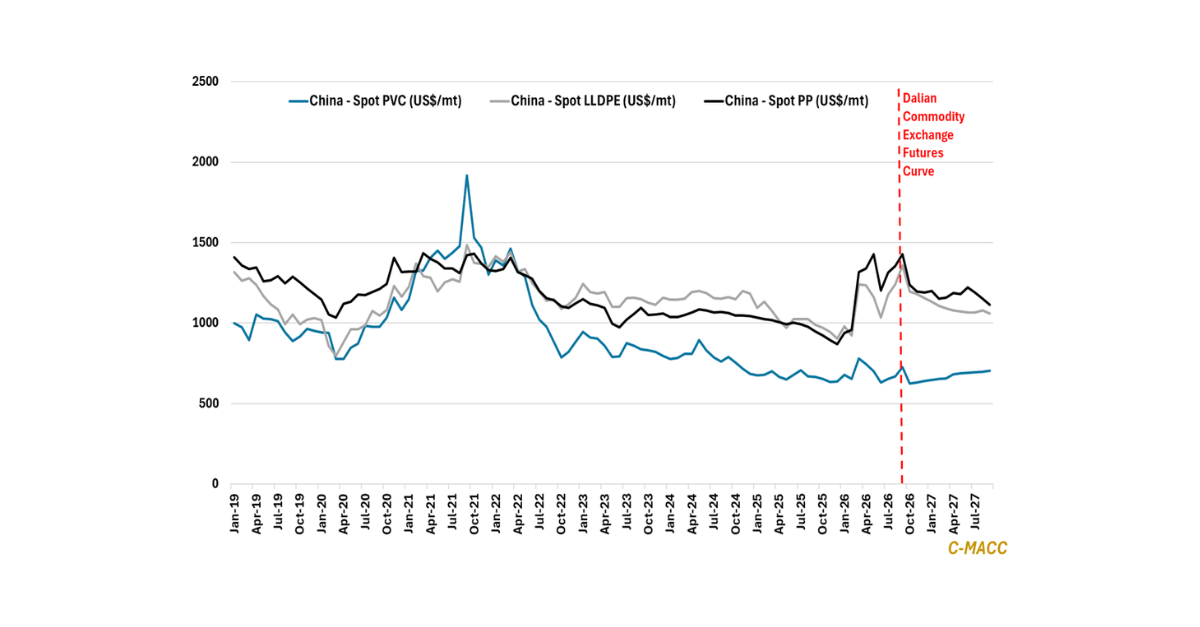
- Polyethylene (PE): Global spot PE prices rose into 2025, but the positive momentum reversed in 1Q25, and we see further price hikes are challenging to support unless oil prices surge higher or unplanned supply issues occur.
- Polypropylene (PP): European and US spot PP markets slide versus Asia amid ample supply and muted demand, signaling limited prospects for a global price rebound. Western premiums are likely to shrink further by year-end.
- Polyvinyl Chloride (PVC): Global spot PVC markets are pressured by sluggish demand, export hurdles from rising regional protectionism, and narrowing global cost advantages YTD – Asia Ex-China players reflect substantial risk.
- Other Sector Developments: Global chemical feedstock markets reflect a flatter polymer production cost curve relative to the 1Q25 average and each quarterly average in 2024, implying persistent 2025 US margin challenges.
Exhibit 1 – Chart of the Day: US spot polymer margins close 1Q25 at YTD lows; 2Q25 improvement looks challenging.
Source: Bloomberg, C-MACC Analysis, April 2025
Client Login
Learn About Our Subscriptions and Request a Trial
Contact us at cmaccinsights@c-macc.com to gain full access and experience our services!