Polymer Global Analysis
Resin To Riches: Weekly Plastic Market Insights
- General Thoughts: Global polymer markets have entered a high-stakes transition shaped by weak demand, rising protectionism, and structural resets, where scale, strategy, and adaptability determine who best performs into 2026.
- Polyethylene (PE): Global PE trade is realigning as North American exports shift from Brazil to potentially target Europe, positioning North American suppliers to dominate EU markets if tariff relief clears and demand stabilizes.
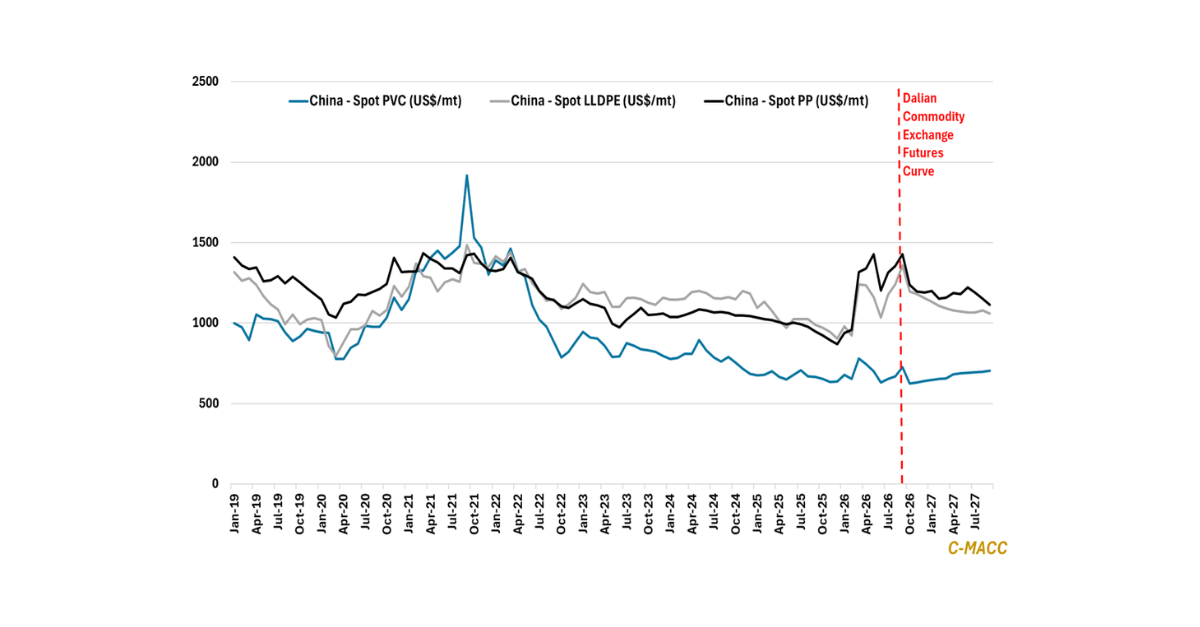
- Polypropylene (PP): Global PP markets are oversupplied and demand-constrained, with recovery delayed as new capacity outpaces consumption; realignment may not begin before mid-2026 without decisive supply discipline.
- Polyvinyl Chloride (PVC): Global PVC markets are fragmented and margin-stressed, with India’s protectionist pivot reshaping trade flows amid oversupply, weak construction demand, and rising pressure on uncompetitive producers.
- Other Sector Developments: US natural‑gas feedstock costs have rebounded from late August levels, while oil stayed flat, implying a flatter global polyolefin cost curve in late 3Q25, squeezing US integrated polymer margins.
Exhibit 1 – Chart of the Day: Global spot PP-to-PGP spreads will likely tighten in 2H25; US spreads face notable risk.
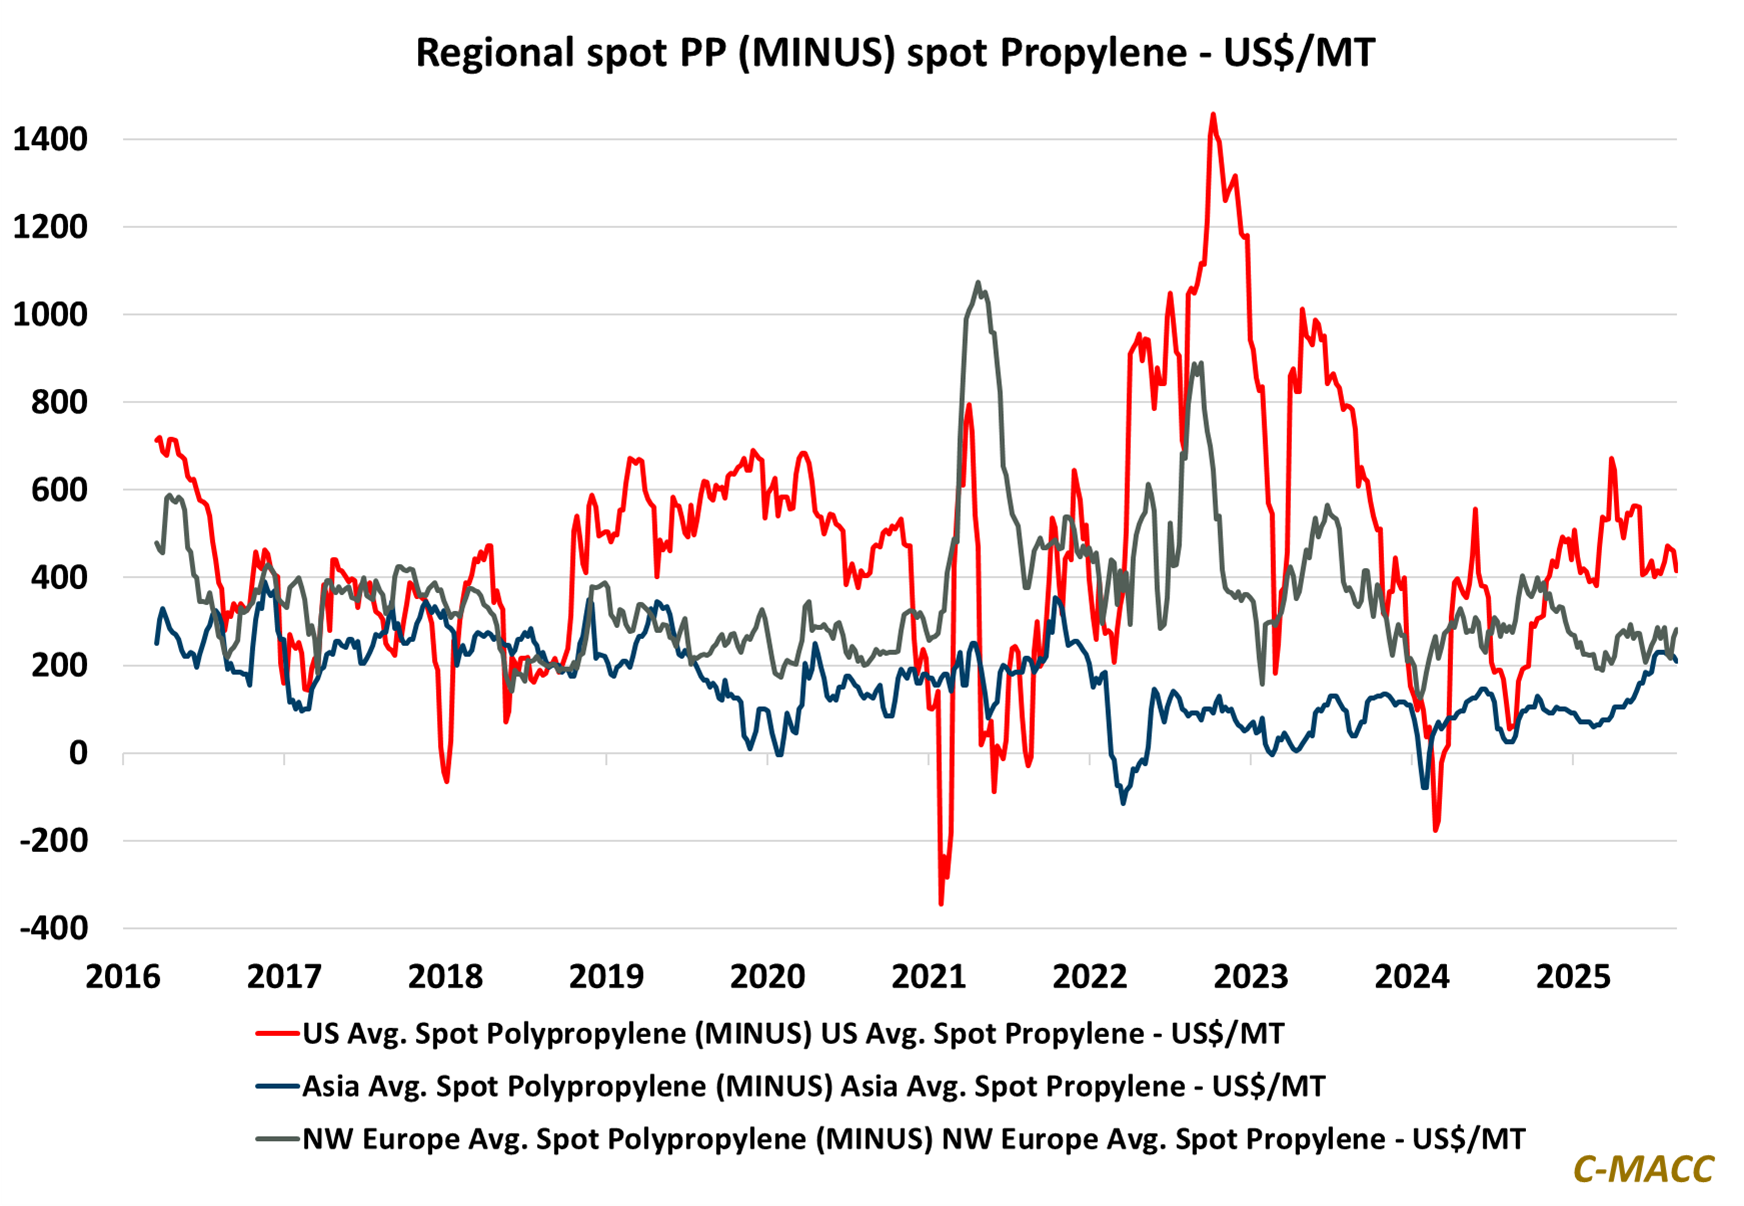
Source: Bloomberg, Company Reports, C-MACC Analysis, September 2025
Client Login
Learn About Our Subscriptions and Request a Trial
Contact us at cmaccinsights@c-macc.com to gain full access and experience our services!